
Digital download
Access the files immediately after checkout.
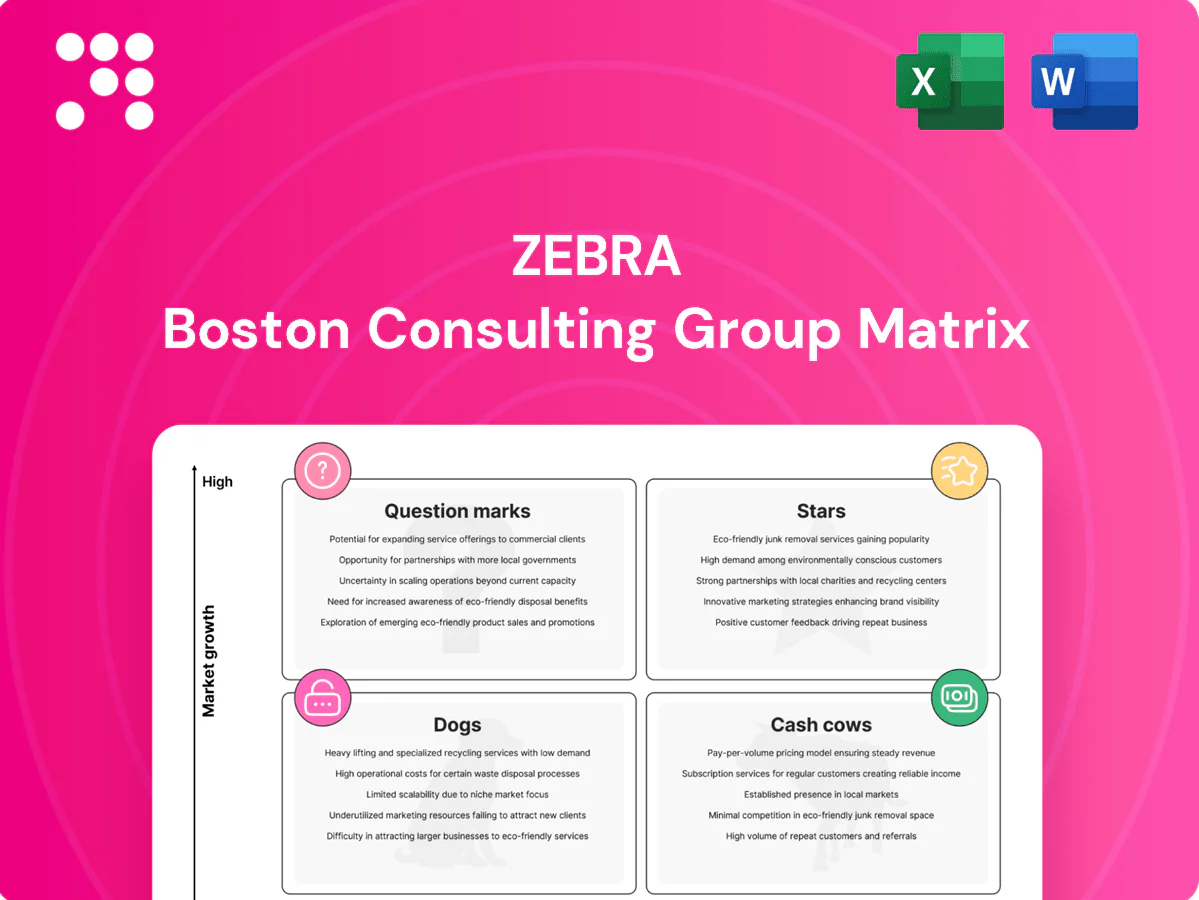
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Curious where Zebra’s products sit — Stars, Cash Cows, Dogs, or Question Marks? This preview's a taste; buy the full Zebra BCG Matrix for quadrant-by-quadrant placement, data-backed recommendations, and a clear roadmap for where to invest or cut losses. Purchase now and get a polished Word report plus an Excel summary you can edit and present immediately.
Zebra leads handhelds for retail and warehousing, where Android rugged mobile computers still see strong growth; Zebra reported roughly $6.0B in revenue in FY2024, with mobile computing a core driver. A large installed base in the millions, recurring upgrade cycles and sticky enterprise integrations keep share high. They spend heavily on channel incentives and refresh CAPEX, but the cash-generating flywheel moves these from Stars toward Cash Cow.
RAIN RFID readers & printer-encoders are perched as Stars in Zebra’s BCG matrix: item-level retail and logistics adoption surged in 2024, with apparel tagging reaching about 40% adoption, placing Zebra’s portfolio on the front edge. Their large installed base and reference customers give first call on new rollouts, and bundled hardware plus software/services keeps average deal sizes robust. Continued investment is essential to maintain leadership while the market sprints.
Barcode scanners in omnichannel ops remain a Star: e‑commerce sales reached about 6.4 trillion USD in 2024, keeping in‑store and DC scan volumes high, and Zebra—with FY2024 revenue near 5.3 billion USD—retains a leading share in scanners. The technology is mature but new use cases (BOPIS, returns, microfulfillment) drove faster‑than‑expected adoption in 2024. Promotions and retail placement still determine refresh wins, and as growth normalizes these units can shift into Cash Cow.
Specialty thermal printers (industrial & mobile) drive fulfillment speed—high‑throughput and mobile labeling are core operations and Zebra remains the spec brand on many floors; parcel and cold‑chain expansion kept category growth in 2024, with Zebra reporting roughly $5.7B revenue in FY2024. Ongoing channel, firmware and supplies lock‑in sustain aftermarket spend; slowing unit growth still yields steady free cash.
Bedside scanning and clinician handhelds are expanding as hospitals digitize workflows; 96% of US hospitals had certified EHRs by 2024, enabling tighter device integration. Zebra’s purpose-built, disinfectant-ready designs meet clinical infection-control standards and are widely deployed. Deals become sticky once integrated with EHR and meds management; hospital refresh cycles of 5–7 years sustain recurring demand.
Zebra’s Stars—handhelds, RAIN RFID, scanners and specialty printers—drove FY2024 share gains with mobile computing cited at roughly $6.0B and strong installed bases; apparel item‑level tagging hit about 40% adoption in 2024. E‑commerce volume (~$6.4T in 2024) kept scanner demand high while parcel/cold‑chain lifted printer growth; hospitals (96% EHR certified in 2024) expanded bedside device deployments.
| Category | 2024 metric | Impact |
|---|---|---|
| Handhelds | ~$6.0B FY2024 | High share, upgrade cycles |
| RAIN RFID | 40% apparel tagging | Frontline adoption |
| Scanners | $6.4T e‑commerce | Sustained scan volumes |
| Printers | Parcel/cold‑chain growth | Aftermarket cash |
 Detailed Word Document
Concise Zebra BCG Matrix review: quadrant-by-quadrant strategic guidance on investing, holding or divesting for each product unit.

 Customizable Excel Spreadsheet
One-page Zebra BCG Matrix that highlights cash cows and stars, easing portfolio prioritization for busy execs.
Legacy corded barcode scanners retain a solid share in a replacement-driven niche, with Zebra reporting steady scanner hardware demand in FY2024 as enterprises prioritize reliability. Ongoing volumes mean low incremental R&D and promotional spend now, while service and spare-parts sales sustain revenue streams. Durable margins persist given scale and reputation; milk and maintain service/support to defend the installed base.
In long-standardized factories and 3PLs growth for industrial thermal printers is modest but predictable, with the global market for industrial label printers growing roughly 3% CAGR through 2028. Zebra’s installed base of over 10 million devices and deep parts ecosystem keep competitors at bay, supporting high attach rates for service contracts. Service and spares add recurring margin, while optimizing manufacturing and keeping firmware updates lean reduces costs and return rates.
High-margin consumables (labels, tags, ribbons) deliver 60–70% gross margins in 2024 and are locked to printer specs, creating durable revenue. Volumes track the installed printer base more than market growth, making demand predictable. Low selling costs and strong cash conversion (cash conversion cycles often under 30 days) turn these into steady cash cows. Tighten the supply chain and keep quality unbeatable to protect margins.
Device management and support (OneCare) is a recurring, low-churn service as of 2024, with strong attach rates that scale directly with installed hardware fleets; it is cash-positive and requires minimal capex. The mature service play sustains steady margins while meeting SLAs and driving analytics upsell opportunities tied to device telemetry.
OEM print engines and modules are embedded in partner devices across stable niches, delivering recurring replacement demand with predictable 3–5 year cycles and contributing to Zebra Technologies fiscal 2024 revenue of about $4.9 billion. Engineering costs are amortized over long lifecycles, yielding strong cash conversion where Zebra holds high qualification share. Continuous cost-downs and lifecycle assurances (firmware, spare policies) preserve margin and cash flow.
Cash cows: legacy scanners, industrial printers, consumables and OneCare services yield steady, high-margin cash flows; consumables gross margins 60–70% in 2024; Zebra FY2024 revenue about $4.9B with installed base >10M devices; low capex, predictable replacement cycles 3–5 years.
| Metric | 2024 |
|---|---|
| Revenue | $4.9B |
| Consumables GM | 60–70% |
| Installed base | >10M |
The Zebra BCG Matrix you're previewing is the exact file you'll receive after purchase. No watermarks, no demo sections—just the fully formatted, analysis-ready report. It's crafted by strategy pros for clarity and quick decision-making. Once bought, the full document is instantly downloadable and editable for presentations or planning. No surprises—just plug and play.
Obsolete Windows/3G-era handhelds are a Dogs: post-Android transition (Android >70% global mobile OS share in 2024) and major carriers completed 3G sunsets by 2022, demand collapsed. Support costs linger while revenues erode, with installed-base declines exceeding 80% in many enterprise segments. Little strategic upside beyond contract wind-downs; sunset quickly and redeploy service capacity to Android/4G/5G devices.
Low-end commodity labelers face brutal price-war segments with thin differentiation and little loyalty; in 2024 the label/thermal-printing space grew only in low-single-digits, leaving markets flat and crowded. Cash gets tied up in inventory and R&D with minimal return as margins compress toward low single digits. Exit or narrowly focus on profitable micro-niches (value-added software, integrated solutions) only.
Standalone on-prem modules misaligned with modern SaaS roadmaps are maintenance-heavy and show low upsell potential, with legacy support often consuming ~20% of license spend annually. Customers are migrating off these systems—surveys in 2024 found a majority of enterprises accelerating cloud migrations. Migrate, bundle, or divest these assets to free resources and redirect spend to scalable SaaS offerings.
Older cradles, cables and specialty mounts lost relevance as fleets modernized through 2024; attach rates declined, demand dripped and inventory risk rose. Margins eroded on small batches, pushing SKU rationalization and aggressive tail clearance to protect gross margin.
Older fixed-mount scanners have become Dogs in Zebra’s BCG matrix as key use-cases have migrated to vision systems and RFID; installed-base share is low and product refresh cycles have effectively ended. Continued support traps cash with limited upside while maintenance and parts chew into margins. Retire SKUs and redirect customers to modern vision/RFID alternatives and subscription services to recapture value; 2024 deployments show visible shift toward camera- and RFID-first solutions.
Obsolete 3G/Windows handhelds and older fixed-mount scanners are Dogs: Android >70% mobile OS share in 2024, 3G sunsets done by 2022, installed-base declines >80% in many segments. Legacy on‑prem modules consume ~20% of license spend; low‑end labelers see low-single-digit market growth in 2024. Retire, bundle, or divest; redeploy to vision/RFID and Android devices.
| Asset | 2024 metric | Recommended action |
|---|---|---|
| 3G/Win handhelds | IB decline >80% | Sunset, migrate to Android |
| Low-end labelers | Growth ~<1-3% | Exit/ niche focus |
| On‑prem modules | Support ~20% license spend | Bundle/divest |
| Fixed‑mount scanners | Deployments falling | Retire→vision/RFID |
Autonomous mobile robots and orchestration sit in Zebra’s Question Marks quadrant as warehouse automation surges — the global warehouse automation market reached an estimated $27.9B in 2024, yet share is still being fought for. Winners will be decided by integration depth and clear ROI proof; many AMR programs are cash-hungry today but can become Stars tomorrow. Invest where customer lifetime value justifies the burn.
Machine vision & AI inspection sits as a Question Mark: high-growth market—global machine vision ~$11.7B in 2024 with ~8.9% CAGR to 2030—and competition remains fragmented. Zebra’s stack is forming but leadership isn’t locked; FY2024 revenue ~6.1B gives firepower but requires channel enablement, SDK love, and lighthouse wins. Push hard or partner up to accelerate scale quickly.
Real-time location systems (RTLS/UWB/BLE) saw accelerating demand in 2024, driven by healthcare, manufacturing and yard operations where asset/location visibility directly reduces labor and downtime. Adoption remains patchy across use-cases, with strong wins in repeatable workflows like sterile supply tracking and shop-floor WIP. Bundling hardware with platform subscriptions can materially improve unit economics and margins. Focus investments where workflows are proven and repeatable.
Computer vision for retail execution & analytics addresses hot 2024 pain points—shrink (~1.3% of sales), shelf compliance failures and rising self-checkout losses—facing fast-moving competitors; vendors show early traction with pilots but none dominate. Data models and store-ops integration form the moat; pilot fast, productize faster, scale with proof of savings and conversion uplift.
Cold chain sensors & condition monitoring sit as Question Marks for Zebra: global food and pharma traceability tightened in 2024, driving a cold chain market ~USD 260B and sensor demand growth >15% year-over-year; incumbent fragmentation keeps Zebra share low despite strong market expansion. Hardware-to-cloud bundles are the commercial unlock; prioritize end-to-end solutions to capture regulatory-driven wins in pharma serialization and cold-chain audits.
Zebra Question Marks: AMR/orchestration in a $27.9B 2024 warehouse automation market—needs ROI proof to become Stars. Machine vision ~$11.7B (2024) shows fragmented competition despite Zebra’s ~USD 6.1B FY2024 firepower. Cold-chain/condition monitoring sits in a ~$260B 2024 market; prioritize hardware-to-cloud bundles and repeatable workflows.
| Segment | 2024 market | Zebra status | Priority |
|---|---|---|---|
| AMR | $27.9B | Small share | Prove ROI |
| Machine vision | $11.7B | Fragmented | Scale SDKs |
| Cold chain | $260B | Low share | End-to-end |


