
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
Explore Zeon’s competitive edge, operational risks, and market opportunities in a concise SWOT snapshot that highlights core strengths like specialty elastomers and global supply links. Want deeper financial context, strategic recommendations, and scenario analysis? Purchase the full SWOT analysis for a research-backed, editable Word and Excel package to support investment decisions, planning, and presentations.
Zeon spans synthetic rubbers, high‑performance plastics and specialty chemicals, reducing reliance on any single product line and supporting resilience after consolidated net sales of ¥299.2 billion in FY2023. The breadth enables cross‑selling and solution bundling for complex customer needs across automotive, electronics and healthcare end‑markets. That portfolio mix tilts toward value‑added applications, helping sustain higher margins and buffering demand swings.
Zeon’s exposure to automotive, electronics and medical end-markets creates multiple growth vectors, underpinning its ¥238 billion consolidated sales in FY2024 and limiting dependence on any single sector. Cyclical weakness in one vertical can be partially offset by demand in others, while application-specific know-how enhances customer stickiness. This portfolio mix supports steadier cash flows across cycles.
An innovation-driven culture (Zeon, founded 1950 and listed on the Tokyo Stock Exchange) enables tailored materials with measurable performance advantages; R&D and application engineering teams across Japan, the US and Europe accelerate design-in and qualification with OEMs. Proprietary formulations create switching costs for customers, while continuous product improvements support pricing power and sustained differentiation.
Zeon’s tight process control and manufacturing discipline enable consistent delivery of high-spec materials, meeting the stringent demands of automotive and medical supply chains and supporting demanding certifications in those sectors.
This reliability secures long-term contracts and repeat business while lowering customers’ total cost of ownership through fewer failures, less warranty expense and predictable performance.
Co-development with key accounts embeds Zeon early in product lifecycles, securing visibility into future demand and detailed specifications and enabling design-for-performance tradeoffs. Solutions selling shifts conversations from unit price to lifecycle outcomes, increasing share of wallet and improving retention through performance guarantees and integrated support. This approach positions Zeon as a strategic partner rather than a commodity supplier.
Zeon’s diversified portfolio across synthetic rubbers, high‑performance plastics and specialty chemicals supported consolidated net sales of ¥299.2 billion in FY2023 and ¥238 billion in FY2024, reducing single‑product risk and enabling cross‑selling into automotive, electronics and medical sectors. Proprietary formulations and global R&D (Japan, US, Europe) drive switching costs and pricing power, while manufacturing discipline secures long‑term contracts.
| Metric | Value |
|---|---|
| FY2023 consolidated sales | ¥299.2 billion |
| FY2024 consolidated sales | ¥238 billion |
| R&D footprint | Japan, US, Europe |
 Detailed Word Document
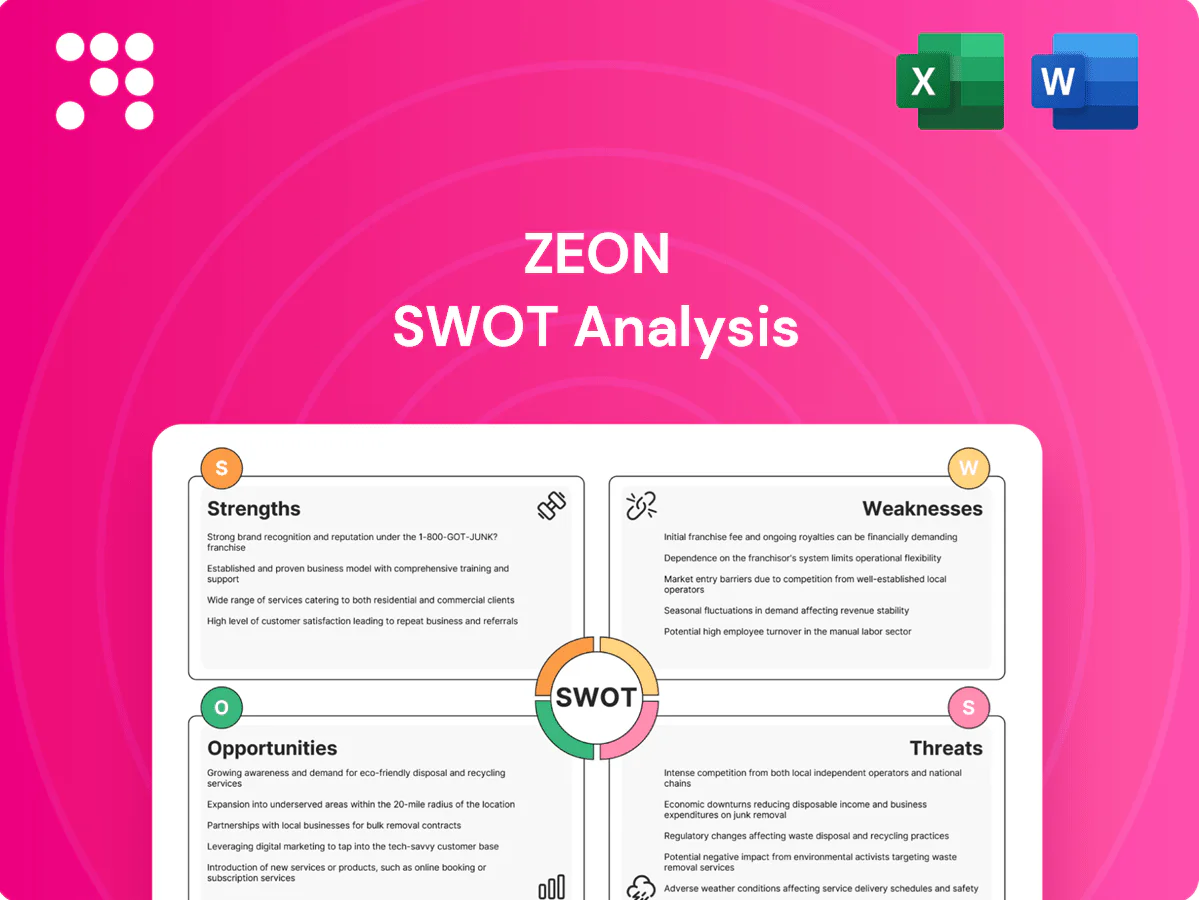
Provides a concise SWOT overview of Zeon, highlighting its core strengths, operational weaknesses, market opportunities, and external threats to assess strategic positioning and growth prospects.

 Customizable Excel Spreadsheet
Provides a focused SWOT matrix for Zeon that quickly highlights strategic risks and opportunities, streamlining stakeholder alignment and fast decision-making.
Zeon’s rubber and engineering plastics volumes closely track industrial production, autos, and electronics, making revenue highly cyclical. Downturns compress plant utilization and margins as fixed costs stay elevated. Electronics inventory corrections are often abrupt, amplifying short-term demand shocks. Volatile cycles increase planning complexity across procurement, production and working capital management.
Zeon's reliance on petrochemical feedstocks leaves input costs exposed to oil and naphtha price swings, with price spikes often passed through to customers only after a lag, compressing margins. High energy intensity in production magnifies this risk in regions with elevated power or gas prices. Financial hedging programs reduce volatility but cannot fully eliminate exposure, leaving earnings sensitive to sustained commodity rallies.
Specialty chemical plants require ongoing capex to sustain quality and capacity; Zeon budgeted about ¥25 billion in FY2024 capex to support elastomer and OLED material production, keeping asset bases heavy.
Safety and environmental compliance add fixed costs that compress margins, with compliance capex and operating costs often material year-to-year.
Long payback periods—commonly over 5 years—raise internal hurdle rates and limit flexibility versus asset-light peers.
Product-qualification rigidity: automotive PPAP cycles commonly take 6–18 months and FDA data shows 510(k) median review ~5.8 months vs PMA ~1,120 days, making approvals lengthy and costly. Once components are specified, design changes are hard, slowing portfolio refresh; qualification failures or delays can defer multi-million-dollar revenue and pull engineering capacity away from other initiatives.
Global operations expose Zeon to currency swings that compress reported earnings and margins across quarters; regional demand shocks and logistics constraints create inventory and supply imbalances; differing local regulations increase compliance costs and operational complexity; hedging and production localization mitigate but do not eliminate these risks.
Zeon faces high cyclicality as volumes track autos/electronics, squeezing utilization and margins in downturns. Feedstock and energy exposure leaves earnings sensitive to oil/naphtha rallies despite hedging. Heavy ongoing capex (¥25 billion in FY2024) and lengthy paybacks (>5 years) limit flexibility; long product-qualification timelines (auto 6–18 months; PMA ~1,120 days) slow time-to-market.
| Metric | Value |
|---|---|
| FY2024 capex | ¥25 billion |
| Payback | >5 years |
| Auto approval | 6–18 months |
| PMA | ~1,120 days |
This is the actual Zeon SWOT analysis you'll receive upon purchase—no placeholders or samples. The preview below is pulled directly from the full, editable report and reflects its professional structure and depth. Buy to unlock the complete document.
Electric drivetrains require heat-, chemical- and flame-resistant elastomers and polymers for motors and power electronics; global BEV sales reached about 14 million units in 2023 (IEA), expanding demand for such materials. Battery packs and charging systems need sealing, insulation and lightweighting; typical pack sizes are ~60 kWh, increasing material intensity. Zeon can target higher-spec grades with premium ASPs and early design-ins to lock multi-year volumes.
Rising demand for ultra-clean, low-outgassing materials in chipmaking and 5G/AI hardware positions Zeon to supply specialty elastomers and coatings; global semiconductor sales were $556.8 billion in 2023 (SIA). High-frequency and thermal-management roles favor specialty polymers with low dielectric loss and high thermal conductivity. Supplying consumables and precision components can create recurring revenue streams. Tight specs reward quality leadership and premium pricing.
Biocompatible elastomers and plastics position Zeon to serve a medical device market estimated at about USD 520 billion in 2024, spanning devices, diagnostics and wearables. Aging populations and a shift to outpatient care—ambulatory services growing roughly 6% CAGR—support steady demand. Regulatory approvals create durable barriers protecting qualified suppliers, while bespoke formulations can deepen customer integration and margin capture.
Sustainable and circular solutions position Zeon to meet rising ESG demand: low-VOC, solvent-free, and recyclable materials support customer targets while bio-based inputs and mass-balance certification (increasingly adopted by OEMs through 2024) can differentiate product lines and command price premiums supported by lifecycle performance data.
Strategic alliances and M&A let Zeon shorten time-to-market through joint development with OEMs and startups, while targeted acquisitions can add niche chemistries or regional sales channels to accelerate growth and diversification.
Zeon can capture rising BEV polymer demand (14M BEVs 2023 IEA), semicap growth ($556.8B 2023) and a ~$520B 2024 medical device market via high-spec, low-outgassing and biocompatible grades, plus premium ESG products as >80% of OEMs disclosed net-zero plans by 2024; targeted M&A/R&D partnerships accelerate design-ins and recurring revenues.
| Market | 2023/24 Size |
|---|---|
| BEV sales | 14M (2023) |
| Semiconductors | $556.8B (2023) |
| Medical devices | $520B (2024) |
Intensifying competition sees global majors and agile regional players chasing the same specialty niches, forcing Zeon into price and innovation battles that can erode margins; the global specialty chemicals market was roughly USD 720 billion in 2024. Chinese suppliers—accounting for nearly 50% of global chemical capacity—undercut costs in standard grades, making continual product differentiation and R&D refresh essential to protect pricing and share.
Supply disruptions from geopolitical tensions or port bottlenecks can curtail Zeon’s output, with global container freight rates in 2024 still roughly 50% above 2019 levels, raising landed costs. Feedstock shortages ripple through specialty lines, forcing customers to dual-source—industry surveys in 2024 show increased multisourcing. Expedited logistics inflate costs and squeeze profitability.
Stricter environmental rules can raise compliance costs or phase out chemistries—REACH now covers over 22,000 substances, forcing reformulations and testing. REACH-like regimes in China and Korea plus US TSCA updates are expanding globally, increasing dossier and testing burdens. Carbon pricing (EU ETS averaged ~90 €/t CO2 in 2024) and risks of fines or customer loss can disproportionately hit Zeon’s energy‑intensive plants.
Large OEMs and Tier-1s concentrate procurement power, imposing annual cost-downs often in the 3–5% range that can outpace supplier productivity gains.
Vendor rationalization by customers reduces the supplier base to strategic partners, threatening Zeon’s share if it is not a top performer on quality, cost and delivery.
Long-term contracts can lock Zeon into unfavorable pricing and margin erosion, reducing flexibility to respond to market shifts.
New materials, additive manufacturing and novel composites threaten to displace incumbent elastomers and plastics; the global additive manufacturing market was about 17 billion USD in 2023 and is driving specification shifts in parts and materials. Rapid shifts in battery chemistries—Li‑ion still >90% of cells in 2024 but heavy investment in solid‑state—change needed polymer properties; lagging R&D risks obsolescence for Zeon.
Intensifying competition and Chinese low-cost overcapacity (~50% global capacity) pressure margins; global specialty chemicals ~USD 720B (2024).
Logistics and feedstock risks (container rates ~+50% vs 2019) and stricter regs (REACH >22,000 substances; EU ETS ~90 €/t CO2 in 2024) raise costs.
Tech shifts (AM ~USD 17B 2023; Li-ion >90% cells 2024) risk product obsolescence without sustained R&D.
| Risk | 2024/23 metric |
|---|---|
| Market size | USD 720B |


