
Digital download
Access the files immediately after checkout.
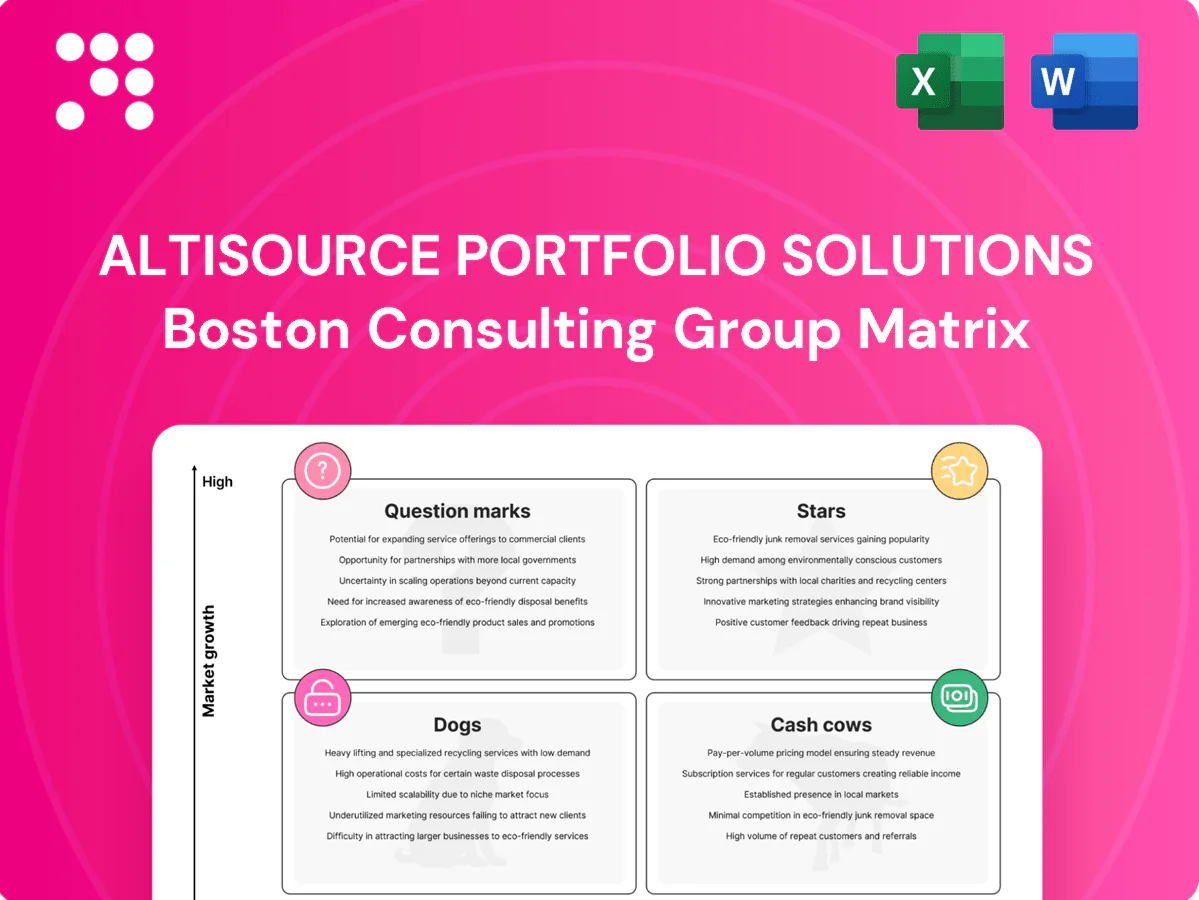
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Quick read: Altisource Portfolio Solutions’ BCG Matrix highlights which business lines are pulling their weight and which are burning cash—ideal for leaders who need clarity fast. This preview points you to the likely Stars and Question Marks; buy the full BCG Matrix for quadrant-by-quadrant data, practical recommendations, and Word + Excel files you can act on immediately.
Default servicing platforms are a Stars play for Altisource, commanding high share with servicers that need scale as delinquencies rise; mortgage-servicing technology demand is projected to grow ~8% CAGR through 2028 (2024 baseline). The market expands when rates bite and exits slow, keeping adoption hot. Maintain product, integrations and 99.9%+ uptime — defend-and-invest. Hold leadership now, graduate to cash cow as growth cools.
REO disposition marketplace shows strong traction moving bank-owned assets quickly and transparently, delivering the speed and certainty investors demand while sellers receive clean execution—this operational flywheel is observable in higher sell-through and tighter days-on-market. Marketing and inventory liquidity still require ongoing cash to sustain leadership, and capturing supply remains the critical lever: win the supply side and volume, pricing power and referral pipelines compound.
Foreclosure workflow automation stitches court, title and vendor steps into one lane, creating a hard-to-copy operational moat for Altisource Portfolio Solutions in 2024. Regulators continue to reshape the maze, keeping demand high as U.S. foreclosure starts rose about 20% year-over-year in 2024 per industry reports. Continued investment in compliance rules, APIs and dashboards positions the business to convert rising filings into recurring cash flow if market share holds.
Audit trails, QC, and servicing rule libraries are must‑haves for Altisource’s servicer compliance toolset; oversight pressure and consent orders are primary growth drivers, and enterprise adoption rose amid regulatory scrutiny in 2024. Implementation soaks investment in content, attestations and evidence pipelines but reduces headline risk. Leaders standardize on vendors that demonstrably prevent enforcement exposure.
Investor asset analytics for Altisource uses pool stratification, time-to-sale and severity models that steer dynamic pricing; with 2024 mortgage rates near 7% investors lean in as credit normalizes then tightens. Keep training data and scenario engines fresh and integrate directly into trading desks to enable faster decisions, stickier seats and higher share.
Altisource Stars: servicing platforms, REO marketplace and foreclosure automation lead share in expanding distress-driven markets (mortgage rates ~7% in 2024); servicing tech demand ~8% CAGR to 2028 (2024 baseline); foreclosure starts rose ~20% YoY in 2024, keeping volume and pricing opportunity high.
| Metric | 2024 Value |
|---|---|
| Mortgage rate | ~7% |
| Servicing tech CAGR | ~8% (to 2028) |
| Foreclosure starts | +20% YoY |
| Uptime target | 99.9%+ |
 Detailed Word Document
Comprehensive BCG Matrix review of Altisource units, with quadrant strategies, investment recommendations, risks and market context.

 Customizable Excel Spreadsheet
One-page BCG matrix showing Altisource units by quadrant to pinpoint portfolio pain points fast.
Property preservation services are a cash cow for Altisource in 2024, with mature, steady demand across inspections, securing, and repairs. Margins improve materially as route density rises and vendor scorecards drive performance and cost control. With limited market growth, management should focus on efficiency, SLA predictability, and tooling upgrades. Milk the cash while avoiding scope creep to protect unit economics.
Valuation and title support remains a cash cow for Altisource, with BPO-assisted title curative and valuation review humming at stable volumes and delivering predictable cash flow. Process IP and playbooks sustain high throughput, keeping unit costs low while growth stays low-single-digit year-over-year. Investing in automation to trim touch time and protect margin should further lift operating margin and free cash flow.
Approved vendor networks, scorecards, and integrated payment rails create sticky, predictable cash flows for Altisource, driving high lifetime value as servicers face real switching costs from workflow integration and compliance dependencies.
Claims and investor reporting uses standardized templates, checklists, and evidence packaging for GSE/MI recoveries to ensure repeatable, audit-ready files where accuracy outweighs flash; operational consistency drives high renewal rates and steady fee income in a low-growth segment. Focus on compliance, cycle-time control, and cash collection to protect margins and investor trust.
Document imaging & indexing handles high-volume scanning (≈1M pages/month) with OCR accuracy ~98–99% and loan-file assembly that cuts processing cycles by ~30%, reflecting mature tech and steady order flow; efficiency gains flow directly to EBITDA, often improving margins by ~10–15%. Maintain capacity and reliability rather than overbuild; uptime and accuracy matter more than novelty.
Property preservation, valuation/title, vendor networks, claims/reporting and document imaging are cash cows for Altisource in 2024, producing stable, high-margin cash flows with low-single-digit growth. Focus on efficiency, SLA predictability, automation, and cash collection to protect unit economics and free cash flow.
| Segment | 2024 Metric | Note |
|---|---|---|
| Doc imaging | ≈1M pages/mo; OCR 98–99% | Cycle −30%; EBITDA +10–15% |
| Valuation/title | Stable volumes, low‑single‑digit growth | Automation ups margin |
The file you're previewing is the exact Altisource Portfolio Solutions BCG Matrix you'll receive after purchase. No watermarks or demo placeholders—just the final, fully formatted report ready for strategic use. It’s crafted by experts and sent immediately to your inbox, editable and print-ready for presentations or internal planning. What you see is what you get: no surprises, just actionable analysis.
Legacy on-prem modules carry heavy installs, dated UI and brittle custom code that slow deliveries; 92% of enterprises report multi-cloud strategies (Flexera 2024), so clients want cloud and open APIs yesterday. Prolonged turnarounds erode time-to-revenue and margin, with migration projects often extending timelines and costs. Recommend clear path: sunset, migrate, or exit.
Dogs: Manual data keying services for Altisource Portfolio Solutions show high drag—industry key‑punch error rates run about 0.5–4% and labor often represents 60–80% of processing costs, draining margins on legacy workflows. Automation and capture tech can cut processing costs 50–70%, turning manual ops into a cash trap; recommend wind down and redeploy talent to exception handling and automation oversight roles.
Print-and-mail fulfillment faces sharp volume declines and commoditized pricing that have crushed spreads for Altisource Portfolio Solutions, turning a once-stable service into a low-margin offering. Regulatory notices still require handling, but margins no longer justify in-house capacity when partners achieve lower per-unit costs at scale. Strategic action: divest the segment or fully outsource to specialized vendors to stop margin erosion and redeploy capital to higher-growth units.
Small broker referral programs are fragmented, hard to manage and deliver low throughput; independent brokers handled about 21% of US mortgage originations in 2023 (MBA), but referral volumes to Altisource remain marginal. Platform synergy is thin, customer-acquisition costs do not materially pay back, and the channel distracts from higher-margin institutional relationships. Trim and redeploy resources to institutional channels.
Standalone inspection point apps are Dogs in Altisource’s BCG matrix: point solutions without end-to-end hooks see attach rates drop below 12% in 2024, while clients demand integrated claims and preservation flows, reducing purchase relevance. Upkeep now consumes roughly 30% of lifecycle costs versus 8% of contribution margin, so retire or bundle only if the move measurably lifts attach rate and cross-sell KPIs.
Altisource Dogs: legacy on‑prem modules, manual keying and print/mail are low‑margin, with key‑punch errors 0.5–4% and labor 60–80% of costs; attach rates for point apps <12% (2024) and upkeep ~30% of lifecycle, so sunset/divest or outsource and redeploy to automation/exception roles.
| Metric | 2024 |
|---|---|
| Attach rate | <12% |
| Upkeep share | ~30% |
| Key‑punch error | 0.5–4% |
| Labor share | 60–80% |
AI loss-mitigation copilot offers promising triage and automated proposal generation for mods and workouts, targeting a US mortgage workout market estimated at $12–15B in 2024; high growth interest but Altisource holds low current share (~5–10%). It needs rigorous proof on accuracy (>=95% decision parity), fairness and auditability. Bet big if regulators (CFPB/OCC) bless the model, otherwise shelve fast.
End‑to‑end origination SaaS sits in a crowded market dominated by entrenched LOS incumbents (Black Knight, ICE), adjacent to servicing for a U.S. mortgage system with debt outstanding above $13 trillion in 2024. Growth exists but share remains small for challengers; win paths are targeted credit boxes and default‑aware pricing, or deep partnerships with servicers. Alternatively pivot to modular APIs to capture specific workflows.
In 2024 investors increasingly demand fresher comps, cure curves and liquidation severity feeds to price NPLs more accurately. Early subscription traction exists, but datasets remain noisy and introduce modeling risk that can misprice portfolios. If coverage scales across servicers and investors to reach critical mass, the offering can flip to a star in the BCG matrix. If adoption stalls, growth plateaus quickly—decide fast.
Regtech rule engine as API externalizes the compliance brain to third parties; the RegTech market surpassed 10 billion USD in 2023 and enterprise procurement cycles typically run 9–12 months.
Build SDKs, immutable evidence logs and attestation packs to accelerate integration, audits and vendor approval; land lighthouse clients quickly or consider pulling back.
As a Question Mark in Altisource Portfolio Solutions BCG Matrix, pursue measured investment and require 1–2 lighthouse wins within 12 months to justify scaling.
Single-family rental turn services address SFR operators' need for fast turns, competitive bids, and reliable make‑readies; demand is growing as SFRs make up roughly 25% of US rental stock in 2024. Altisource sits in the growth BCG quadrant but holds a small share; operational complexity (scheduling, vendor networks, quality control) is nontrivial. Current strategy: pilot in a few metros and scale only if unit economics prove positive.
Question Marks need measured bets: target AI loss‑mitigation ($12–15B TAM 2024) and origination/data/regtech adjacencies where Altisource holds ~5–10% share; require 1–2 lighthouse wins and >=95% decision parity within 12 months or exit.
| Offering | 2024 TAM | Altisource share | Key KPI | 12m trigger |
|---|---|---|---|---|
| AI loss mitigation | $12–15B | 5–10% | >=95% parity | 1 lighthouse |
| Origination SaaS | Adj. to $13T mortgage market | ~5% | net-new LOS wins | 3 pilots |


