
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
See how the whole operating model connects.
Link the offer to segments, channels and relationships.
Review revenue streams, costs, resources and partners.
Dive into Altisource Portfolio Solutions’ strategic playbook with our concise Business Model Canvas—three to five clear sentences mapping value propositions, revenue streams, and key partners. Perfect for investors and strategists, the full downloadable canvas (Word/Excel) gives the detailed, actionable breakdown you need to benchmark and scale—purchase now to unlock every section.
Anchor partnerships with national and regional servicers secure steady volume across origination, servicing, default, and disposition workflows, tapping into a U.S. mortgage servicing base exceeding $12 trillion UPB in 2024. Joint process design aligns SLAs and compliance, reducing handoff defects and cycle time. Multi-year MSAs stabilize demand and enable deeper API and workflow integrations, while co-marketing and case studies demonstrate quantifiable ROI for adjacent prospects.
Curated networks of licensed agents, appraisers, inspectors, and preservation vendors provide local execution at scale, supported by performance scorecards, coverage mapping, and dynamic routing to optimize turn-times and quality. Partner portals streamline orders, documentation, and payments while capacity planning maintains resilience during default spikes.
Integrations with LOS, servicing platforms (MSP), CRM and e-sign systems reduce friction for enterprise clients and streamline workflows. Partnerships with credit, title, valuation, property and compliance data vendors enrich decisioning. APIs using OAuth 2.0 and TLS 1.2+ (industry standards in 2024) ensure secure, reliable data flows, while co-innovation accelerates roadmap delivery and market differentiation.
Legal and compliance firms specializing in default, foreclosure, bankruptcy, and eviction law ensure jurisdictional compliance across Altisource Portfolio Solutions operations, standardizing panels to harmonize processes and timelines.
Continuous 2024 regulatory monitoring and audits reduce enforcement risk, while joint training and playbooks keep field teams aligned with evolving federal and state rules.
Tie-ups with whole-loan, NPL/RPL, and REO buyers increase take-out certainty and enhance pricing by aligning disposition strategies and commitments across portfolios, while auction and listing marketplaces expand demand and liquidity for assets. Data-sharing improves buyer qualification and reduces fall-out, and preferred relationships shorten disposition cycles and boost recovery per-asset outcomes.
Anchor servicer partnerships secure steady volume from a U.S. mortgage servicing base >$12 trillion UPB in 2024, with multi-year MSAs and API integrations (OAuth 2.0, TLS 1.2+) reducing cycle time and defects. Licensed vendor panels, jurisdictional law panels and buyer tie-ups increase execution scale, compliance and take-out certainty, supported by continuous 2024 regulatory monitoring.
| Partner | 2024 Metric |
|---|---|
| Servicers | >$12T UPB |
| APIs/Security | OAuth 2.0, TLS 1.2+ |
 Detailed Word Document
A concise, pre-written Business Model Canvas tailored to Altisource Portfolio Solutions’ mortgage servicing, asset management and tech-enabled vendor services, covering customer segments, channels, value propositions and revenue mechanics across the 9 BMC blocks. Ideal for presentations and investor discussions, it includes SWOT-linked insights and competitive advantages for strategic decision-making.

 Customizable Excel Spreadsheet
Condenses Altisource Portfolio Solutions’ strategy into a digestible one-page Business Model Canvas, quickly identifying core components and relieving the pain of scattered operational insights for faster decision-making and team alignment.
Design, build, and maintain integrated software supporting origination, servicing workflows, default management, and REO disposition, prioritizing security, scalability, and API-first architecture to operate in a market with roughly $14 trillion mortgage debt outstanding in 2024. Release management aligns with client roadmaps and regulatory deadlines to reduce compliance lag. Continuous UX improvements drive adoption and aim for 20–30% workflow time savings.
Manage order intake, assignment, QA and completion across valuation, title, field services, legal and brokerage with centralized workflows and SLA-driven routing to balance speed and quality. Analytics forecast capacity and control costs, feeding routing rules and staffing plans to reduce bottlenecks. Defined escalation paths resolve exceptions and high-risk cases quickly. Altisource Portfolio Solutions S.A. trades as NYSE: ASPS.
Monitor federal, state, and investor guidelines across the mortgage lifecycle, embedding controls, checklists, and evidence capture into workflows to ensure traceability. Conduct internal audits and support client and vendor examinations, including SOC and regulatory reviews. Maintain certifications such as SOC 1, SOC 2, and ISO 27001, plus documented policies and annual training to meet client and regulatory standards.
Altisource aggregates multi-source loan, title, and property datasets to power pricing, prioritization, and exception handling; as of 2024 these pipelines support near-real-time decisioning and portfolio-level monitoring. Predictive models estimate cure likelihood, time-to-sale, and vendor performance, with continuous validation to prevent drift and bias. Dashboards and alerting deliver actionable insights to clients and internal teams.
Design and operate API-first origination/servicing/default software to serve a $14 trillion 2024 mortgage market, targeting 20–30% workflow time savings. Run SLA-driven order intake, QA, and vendor management with analytics for capacity and cost control. Embed regulatory controls, maintain SOC1/SOC2/ISO27001, and deliver implementations, training, and quarterly business reviews to close the feedback loop.
| Metric | 2024 Value |
|---|---|
| Mortgage market | $14T |
| Workflow savings target | 20–30% |
| Certifications | SOC1/SOC2/ISO27001 |
| Ticker | NYSE: ASPS |
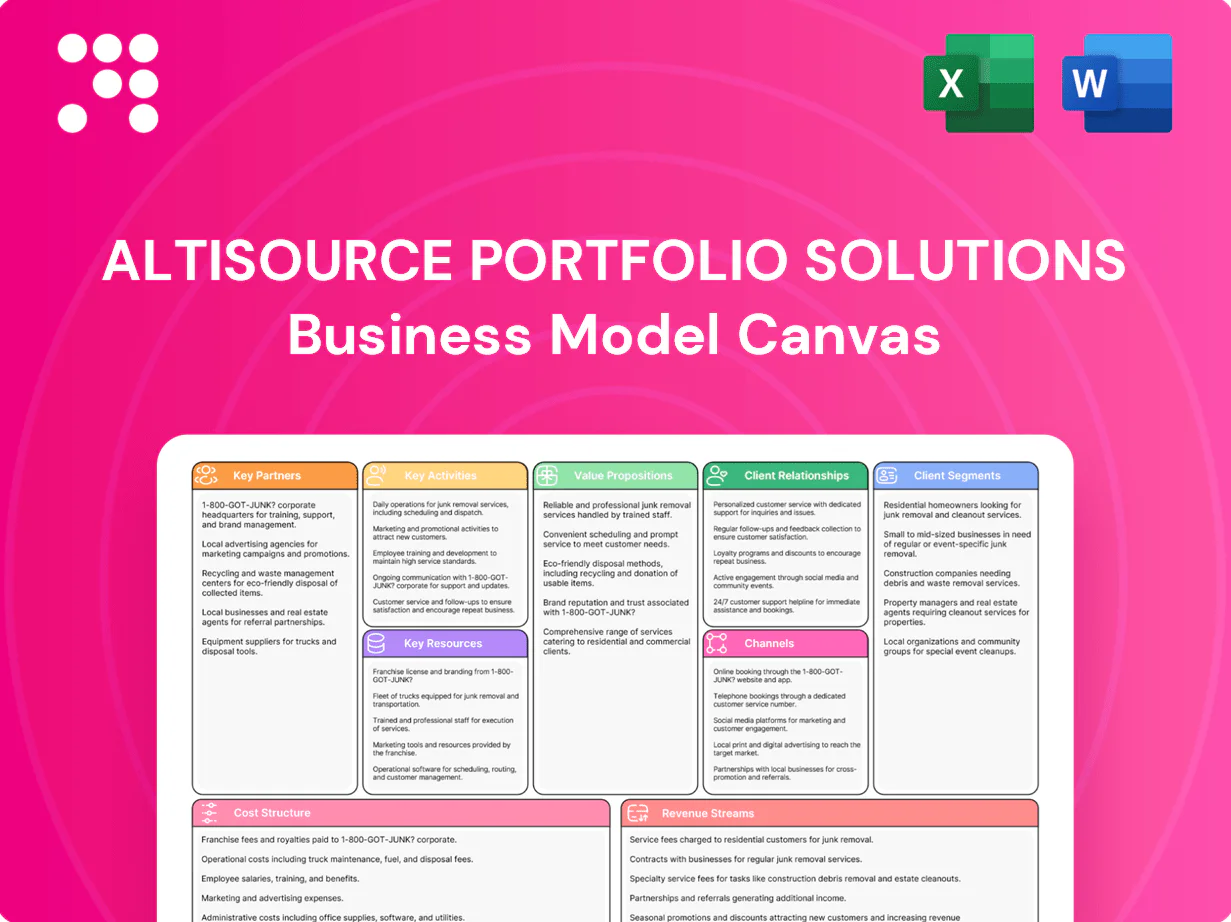
The Business Model Canvas for Altisource Portfolio Solutions shown here is the actual deliverable, not a mockup—what you preview is the same file you’ll receive after purchase. Upon completing your order you’ll get the complete, editable document formatted exactly as shown, ready for presentation or analysis. No placeholders, no separate sample—this is the real Canvas.
Named teams oversee strategy, delivery and performance for each enterprise client, with dedicated resources for account strategy, implementation and operations.
Regular QBRs are held quarterly to align goals and surface improvement areas, using actionable KPIs and SLA reviews.
Executive sponsors provide C-suite escalation to unblock issues rapidly, while client health scores tracked on a 0–100 scale monitor satisfaction and portfolio risk.
Contracted SLAs cover turn-times, quality, and compliance metrics, with Altisource reporting 95% SLA adherence in 2024 across core portfolio services. Joint steering committees meet monthly to review trends and root causes, reducing repeat issues by an estimated 12% year-over-year in 2024. Continuous improvement plans target KPI uplift of 5–15% through process redesign and tech enablement. Transparent reporting, including real-time dashboards, improved client trust scores and renewal rates in 2024.
Solutions engineers and product teams co-develop APIs and custom workflows, leveraging Postman 2024 data that 85% of organizations treat APIs as strategic assets. Sandbox and UAT environments accelerate deployment, cutting time-to-production ~30% per 2024 DevOps surveys. Transparent backlog visibility aligns expectations with stakeholders, and post-go-live monitoring maintains uptime and stability.
Structured onboarding, role-based training, and searchable knowledge bases accelerate adoption and reduce time-to-productivity for Altisource Portfolio Solutions users.
Multi-channel support handles tickets and escalations across phone, email, and portal workflows to maintain SLA-driven resolutions.
Regular release notes and webinars prepare users for product changes while closed feedback loops feed prioritized enhancements into the roadmap.
Long-term, sticky partnerships rely on multi-year contracts and embedded processes that raise switching costs and create predictable revenue streams, with performance incentives aligning supplier fees to measurable value creation.
Case studies and pilots systematically expand share-of-wallet while mutual planning between client and Altisource reduces operational uncertainty and improves retention.
Dedicated named teams, executive sponsors and joint steering committees drive account strategy, quarterly QBRs and SLA-backed operations, with 95% SLA adherence reported in 2024. API co-development, sandbox/UAT and transparent backlogs cut time-to-production ~30% and align roadmap with client feedback; repeat issues fell 12% YoY in 2024. Multi-year contracts plus performance incentives and case-study expansion sustain retention and predictable revenue.
| Metric | 2024 Value |
|---|---|
| SLA adherence | 95% |
| Repeat issues YoY | -12% |
| API strategic adoption | 85% |
| Time-to-production reduction | ~30% |
Account-based selling targets top servicers, lenders, and investors, focusing resources on named accounts where over 97% of B2B marketers report higher ROI from ABM as of 2024. Solution demos and quantified ROI cases drive conversion by proving cost-per-file reductions and recovery uplifts. Executive outreach and customer references accelerate cycles, while procurement navigation supports complex RFPs and multi-million-dollar contracts.
Participation in industry RFPs and procurement platforms captures large programs, with 70% of mortgage servicers using e-procurement in 2024 to source vendor networks. Standardized responses emphasize compliance and scale, shortening review cycles by up to 30% on average. Comprehensive security and due diligence packages accelerate approvals, while tiered pricing frameworks accommodate volumes from single portfolios to enterprise programs.
In 2024 Altisource’s placement in LOS and servicing app stores and partner catalogs eases adoption by meeting buyer procurement workflows. Pre-built connectors shorten implementation cycles and lower integration costs. Joint marketing with platform partners amplifies visibility and lead flow. Technical certifications provide an objective quality signal to institutional clients.
Conferences, panels, and sponsorships target senior decision-makers and, per Bizzabo 2024, 84% of event marketers say live events are critical for demand generation, boosting lead quality and deal velocity. Thought leadership at these venues builds credibility and media pick-up, while networking and workshops convert conversations into pipeline, partnerships, and product demonstrations that shorten sales cycles.
Digital marketing and content drive Altisource Portfolio Solutions inbound pipeline: case studies, whitepapers and benchmarks attract targeted interest, webinars and demos educate stakeholders, SEO and targeted campaigns reach niche roles, and nurture programs keep prospects engaged; content marketing historically costs 62% less and can deliver ~3x more leads.
Account-based selling, demos and executive outreach focus on top servicers and investors, with ABM delivering higher ROI for 97% of B2B marketers in 2024. RFPs and e-procurement capture large programs as 70% of mortgage servicers used e-procurement in 2024, while events and thought leadership (84% say events are critical) accelerate deals. Digital content and webinars lower acquisition costs (62% less) and can deliver ~3x leads.
| Channel | 2024 Metric |
|---|---|
| ABM | 97% higher ROI (B2B) |
| e-Procurement/RFPs | 70% servicers use |
| Events | 84% critical for demand |
| Content/Inbound | 62% lower cost; ~3x leads |
Mortgage servicers and subservicers are core buyers seeking efficiency and compliance across default, loss mitigation, and REO, often managing portfolios within the US mortgage market that had about 13.8 trillion dollars outstanding in 2024 (Federal Reserve). Typically enterprise-scale, many handle hundreds of thousands to millions of loans and require complex system integrations and ongoing SLAs with transparent reporting. They prioritize regulatory rigor and closely monitor cost per loan to protect margins and avoid compliance penalties.
Originators and correspondent lenders require upfront verification, title, valuation and closing support to hit purchase and refinance cycle targets of roughly 30–45 days. They prioritize cycle time and pull-through rate, with integrations to LOS and POS systems shown to boost pull-through by up to 20% in workflow pilots. Volume patterns are seasonal and rate-driven, with originations swinging materially when rates move. Altisource positions modular services to capture these variable flows.
Institutional investors and asset managers acquire whole loans, NPL/RPL and REO portfolios at scale, often targeting multi-market pools and cross-jurisdictional assets. They prioritize speed-to-resolution and aim for recovery rates typically in the 50–70% range on stressed mortgage pools. These buyers demand robust analytics, chain-of-title transparency and standardized reporting. Their mandates are highly data-intensive, driving investments in valuation and workflow platforms.
Government agencies and GSE-aligned programs require strict compliance, SSAE 18/SOC 1 documentation and detailed audit trails; standardized processes and recurring audits are mandatory. These customers supply large, stable volumes with rigorous oversight—combined GSE guarantees exceeded 6 trillion USD in 2024—so they value partners with proven controls and measurable KPIs.
Mortgage servicers: enterprise-scale, 13.8T US mortgage stock (2024), focus on compliance and cost per loan.
Originators: need 30–45 day cycle, integrations raise pull-through ~20%.
Investors: buy NPL/REO, target 50–70% recovery, need analytics.
GSE/agencies: ~6T guarantees (2024), require SSAE18/SOC1.
| Segment | Metric |
|---|---|
| Servicers | 13.8T |
| Originators | 30–45d |
| Investors | 50–70% recov. |
| GSEs | ~6T |
Technology development and infrastructure for Altisource Portfolio Solutions centers on engineering, product, QA, and DevOps to build and scale the portfolio management platform, typically representing the largest line-item in R&D spend. Cloud hosting, data storage, and security controls drive recurring OPEX—Flexera’s 2024 State of the Cloud found ~32% of cloud spend is wasted, emphasizing optimization. Third-party tools and licenses (SaaS, analytics, middleware) plus ongoing maintenance and roadmap investment sustain feature velocity and regulatory compliance.
Vendor payments cover broker/appraiser/inspector fees (2024 industry medians roughly $300–$800 per engagement), preservation crews ($200–$1,000/property) and law firms ($500–$2,500 per matter), plus performance incentives and rush premiums (typically 5–20%). Network management overhead runs ~3–7% of vendor spend, with redundancy/reserve arrangements adding ~10–15% to maintain full geographic coverage.
Compliance, legal, and audit costs cover continuous regulatory monitoring, policy management, and maintaining certifications (heightened in 2024 after intensified CFPB and SEC guidance), internal audits and third-party assessments, legal counsel for contracts and disputes, plus ongoing training and documentation upkeep to preserve audit readiness and reduce remediation exposure.
Operations and service delivery centers incur case management, QA, and exception-handling labor costs driving throughput and SLAs; client onboarding and support require dedicated teams and ramp-up costs tied to average onboarding times. Data processing and reconciliation are intensive—leveraging automation reduces per-file costs—while travel and equipment remain variable overheads. In 2024 the global BPO market was estimated at about $270 billion, highlighting scale economics.
Sales, marketing, and G&A costs for Altisource Portfolio Solutions center on enterprise sales teams, RFP support, targeted promotions, and sponsorships to drive portfolio win rates and client retention; thought leadership and event sponsorships subsidize brand positioning and lead generation while corporate finance, HR, and administrative functions sustain operations; insurance and corporate overhead cover compliance, D&O, and facility costs.
Technology and cloud (R&D + hosting) are the largest costs; ~32% cloud waste per Flexera 2024. Vendor payments median $300–$2,500 per engagement; network management adds 3–7% and reserves ~10–15%. Compliance, legal, audits and operations (case management, onboarding) are material recurring costs; 2024 global BPO market ≈ $270B.
| Category | 2024 Metric |
|---|---|
| Cloud waste | ~32% |
| Vendor median fees | $300–$2,500 |
| Network overhead | 3–7% |
| BPO market | $270B |
Platform subscription and licensing drives recurring SaaS fees for access to workflow modules and analytics, sold via tiered pricing by users, features, or transaction volumes to align with servicer scale. Contracts emphasize multi-year terms with annual escalators to protect margin and convert one-time project work into predictable ARR. Modular add-ons for premium capabilities—advanced analytics, API integrations, and compliance tooling—boost ARPU and upsell potential.
Per-transaction service fees are charged per unit for valuations, title, inspections, preservation and document services, with 2024 industry guidance showing typical inspection fees near $75 and valuation/title ranges varying widely by market. Volume-based discounts commonly scale with client size, often 10–25% in 2024 agreements. Rush and complexity surcharges frequently add 20–50% to base fees. Transparent 2024 rate cards enable predictable budgeting.
Success-based and marketplace commissions tie contingent fees to REO sales, auctions, or resolution outcomes, aligning Altisource’s incentives with proceeds and timeline targets. Buyer premiums and seller fees diversify income streams and reduce reliance on fixed fees. Detailed performance reporting, including transaction-level metrics and timelines, validates value to sellers and buyers and supports fee structures.
Data and analytics offerings provide access to dashboards, benchmarks, and predictive insights tied to portfolio performance, referencing the 2024 Global Datasphere estimated at 149 ZB to convey data scale. API data feeds enable advanced users and system integrations. Custom analytics projects are scoped per portfolio, with subscriptions or usage-based pricing models.
Recurring SaaS subscription and licensing (tiered, multi-year with annual escalators) drives predictable ARR. Per-transaction fees (inspections ~75 in 2024; volume discounts 10–25%; rush/complexity +20–50%) provide variable revenue. Success-based commissions, professional services and data/analytics subscriptions diversify and upsell ARPU.
| Revenue Type | 2024 Benchmark | Pricing Model |
|---|---|---|
| SaaS | Multi-year contracts | Tiered/subscription |
| Transactions | Inspection ~$75; discounts 10–25% | Per-unit, volume tiers |
| Success/Services | Rush +20–50% | Commission, T&M, fixed |
| Data/Analytics | Global Datasphere 149 ZB | Subscription/usage |


