
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
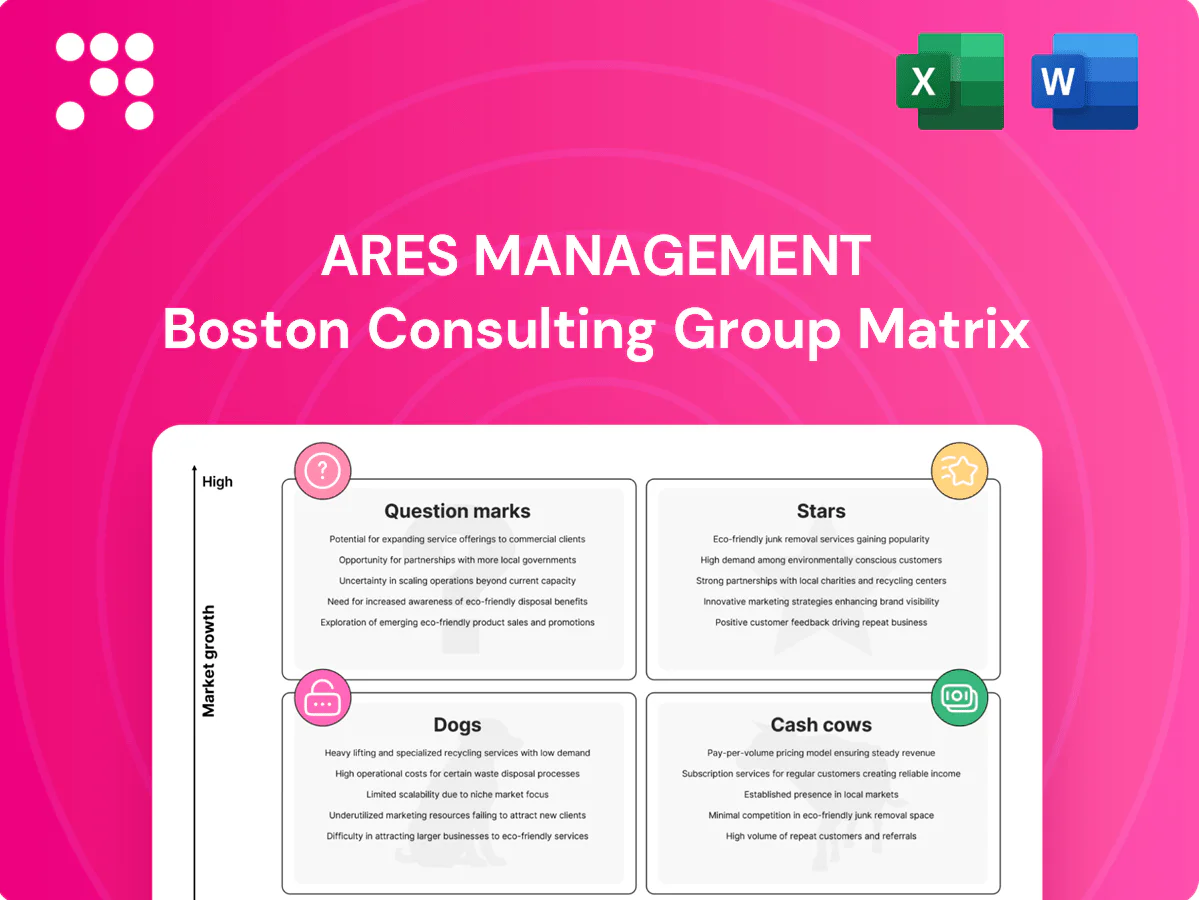
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Curious where Ares Management’s businesses sit—Stars, Cash Cows, Dogs, or Question Marks? This preview sketches the map; the full BCG Matrix gives you quadrant-by-quadrant clarity, data-backed recommendations, and tactical next steps tailored to Ares’ market dynamics. Purchase the complete report for a ready-to-use Word analysis plus a high-level Excel summary and skip the guesswork—make smarter allocation and investment decisions today.
Ares sits at the front of private credit, reporting $421 billion AUM as of 6/30/2024 and capturing a leading share as the private credit market topped $1.2 trillion in 2024. High visibility and steady deal flow make it a Stars-position asset, but sustaining leadership requires relentless origination, underwriting muscle and global distribution. The strategy soaks up capital to stay ahead; continued reinvestment compounds into a long-term engine.
Europe’s private credit adoption curve is steep and Ares’s momentum and brand pull position it as a Star: global private credit AUM surpassed $1 trillion by 2023, and Ares’s credit platform is a top-tier competitor with growing European share versus peers. Rising borrower demand and strong origination mean it behaves like a textbook Star. It requires boots-on-the-ground local sourcing and robust currency/risk frameworks. Feed it now to mature into a cash-rich franchise.
Dislocation fuels special situations and opportunistic credit as restructurings and complex capital needs create mispricings; Ares’ credit platform manages over $200 billion (2024), giving scale and structuring credibility to capture share of a growing opportunity set. These transactions demand heavy origination time and risk capital, yet Ares’ track record and platform concentration let its edge compound as cycles repeatedly generate complexity.
Infrastructure debt for energy transition is a Stars segment as massive capex chases decarbonization, grid expansion and storage: IEA 2024 notes ~$1.8 trillion invested in clean energy in 2023 with needs near $4 trillion/yr by 2030. Ares can underwrite at scale and act fast, winning mandates, but deals are capital‑intensive and relationship‑heavy, consuming cash to plant flags across sponsors and developers; growth tailwinds remain durable.
LP-led and GP-led secondaries volume climbed in 2024 as liquidity remained constrained, and Ares Management’s recognized platform captures chunky, repeat flow in this high-growth lane with rising market share. Sourcing, proprietary data and underwriting depth form the moat, requiring continuous investment to scale. Backed, the platform delivers influence and deal flow across sponsor relationships.
Ares’ Stars: $421B AUM (6/30/2024), dominant private credit share as the $1.2T+ market (2024) fuels high-growth, capital‑intensive franchises across private credit, special situations, infrastructure debt and secondaries; scale and originations sustain leadership but require ongoing cash reinvestment and local execution.
| Metric | 2024 |
|---|---|
| AUM | $421B |
| Credit platform | $200B+ |
| Market size | $1.2T+ |
 Detailed Word Document
Ares BCG Matrix maps funds and platforms into Stars, Cash Cows, Question Marks and Dogs, advising where to invest, hold or divest amid market trends.

 Customizable Excel Spreadsheet
One-page Ares BCG Matrix highlighting portfolio pain points for fast strategic fixes and clear C‑suite decisions.
Flagship direct lending and BDC fee streams deliver steady management and performance fees, anchored in mature segments where Ares’ consolidated AUM was about 378 billion in 2023 and Ares Capital provided a dividend yield near 9% in 2024. Market share is entrenched and growth is slower, but cash conversion and distributable yield remain strong. Modest promotions, strict underwriting discipline, and reliable yields are milked to fund new growth platforms.
Liquid corporate credit and CLO platforms are well-established mandates at Ares with scale economics and sticky institutional relationships; Ares reported roughly $379 billion of assets under management as of mid-2024, underscoring distribution reach. Margins benefit from repeat issuance and servicing efficiency, with CLO fee stacks and ongoing servicing driving predictable fee revenue. Not hyper-growth but consistently cash-generative; optimize ops, protect spreads, and keep the machine humming.
Income-focused real estate debt remains a go-to for institutions seeking structured yield; Ares, with $381 billion AUM at 12/31/2024, leverages deep lender-borrower relationships and underwriting to retain share in this mature niche. Lower growth, high repeatability and durable fees make returns dependable; tighten costs and let the coupons flow.
North America flagship private equity buyouts deliver steady management fees and periodic realizations from mature sectors, anchoring Ares Managements cash flow as growth remains incremental rather than exponential. Operational playbooks and entrenched sourcing networks improve cash efficiency and shorten hold-to-exit timelines, preserving IRR through disciplined deal selection. Maintain strict style discipline to protect the franchise and recurring fee base.
Permanent vehicles and long-dated mandates at Ares generate steady fee-related earnings, lowering churn and amplifying operating leverage; Ares reported approximately $335 billion AUM in 2024, underpinning recurring fees that require relatively light promotion and fund advertising.
That steady cash finances R&D into credit, private equity and alternatives while covering corporate costs; protecting fee terms, deepening allocator relationships and keeping the base dense preserves margin and funds new strategy incubations.
Flagship direct lending, BDC and CLO fee streams generate steady cash; Ares reported $381bn AUM at 12/31/2024 and Ares Capital yielded ~9% in 2024. Mature credit, real estate debt and buyouts have low growth but high fee conversion, funding new strategies. Protect spreads, limit promotions, deepen allocator relationships to sustain distributable cash.
| Metric | Value |
|---|---|
| Total AUM | $381bn (12/31/2024) |
| BDC yield | ~9% (2024) |
The file you’re previewing is the exact Ares Management BCG Matrix you’ll receive after purchase—no watermarks, no demo notes, just the polished, fully formatted report. This is the final deliverable: market-backed insights, clear visuals, and ready-to-use recommendations for strategic planning. After buying, the same document is yours to download, edit, print, or present immediately. No surprises, no extra edits required—just plug it into your workflow and run with it.
Older vintages near end-of-life tie up attention but add little growth; legacy runoff portfolios represent roughly 3% of Ares Managements $378 billion AUM as of mid-2024 (≈$11 billion), creating cash traps that neither burn nor earn much. Minimal upside left and extensions rarely justify the effort; prioritize orderly exits, recover capital, and redeploy investment and operating talent into higher-return strategies.
Where Ares lacks scale or a clear edge—segments representing sub-scale strategies that account for a small share of total AUM—growth is flat and market share remains thin; Ares reported total AUM of $427 billion as of June 30, 2024. Competing on price or speed alone erodes fees and margins, shrinking fee-related earnings per asset. Turnarounds in these niches routinely consume resources with low ROI. Trim, partner, or exit to redeploy capital to core, higher-return businesses.
Non-core geographies without sourcing depth stall where Ares lacks lender or sponsor ties, yielding low market share, slow pipelines, and higher adverse selection. Building relationships from scratch often produces ROI below firm benchmarks and strains origination economics; private credit AUM topped $1 trillion in 2024 (Preqin), concentrating competition in hubs. Shrink the footprint or prioritize key regional hubs where sourcing density and win rates are proven.
Legacy real estate equity in challenged office is a Dogs position for Ares given secular headwinds and value uncertainty, with U.S. office vacancy near 18.5% in 2024 and softening effective rents; not enough growth, not enough liquidity, and too much management noise make it a persistent drag. Expensive fixes rarely change the math; manage down exposure and harvest remaining cash flows carefully.
Tactical, hedge-like credit moves sit outside Ares’ underwriting DNA and erode edge quickly; private credit competition and low-growth pools (global private debt AUM ~1.2 trillion in 2024) compress differentiation and market share. Performance whiplash in 2022–24 fundraising cycles traps capital and management focus; refocus on structural advantages—origination, sponsor relationships, portfolio construction.
Ares Dogs are low-growth, low-share assets—legacy runoff (~3% of $378B AUM ≈ $11B mid-2024), sub-scale strategies, non-core geographies, and challenged office—tying up capital with minimal returns. Private credit competition (global private debt ≈ $1.2T in 2024) and U.S. office vacancy (~18.5% 2024) compress upside. Prioritize orderly exits, harvest cash, and redeploy into core origination-led businesses.
| Metric | Value |
|---|---|
| Legacy runoff | ~3% AUM ≈ $11B (mid-2024) |
| Total AUM | $427B (6/30/2024) |
| Private debt | ≈ $1.2T (2024) |
| U.S. office vacancy | ~18.5% (2024) |
Infrastructure equity build-out spans energy transition, digital infra, and transport where 2024 global spend signals real growth; Ares, with AUM ~$410bn (2024), has brand strength but market share for marquee platforms is still forming. Winning platforms consumes capital, talent, and multi-year time; focus deployments where rights and pipelines are defensible, or pivot quickly to protect IRR and redeploy capital.
Insurers are shifting into private credit for higher yields with strict risk controls; global insurance assets total about $33 trillion (2024), making this a fertile lane. Ares, with roughly $378 billion AUM (2024), has the product toolkit but mandates and scale for ALM mandates are still ramping. Distribution, duration matching and regulatory fluency are the commercial unlocks; decide to invest to win anchor relationships or pass.
Borrower demand in APAC is rising amid a fragmented market where relationships drive origination; global private credit AUM topped $1.3 trillion in 2024 with APAC under 10% (~$120bn), indicating early-stage share and high growth potential. Success requires on-the-ground teams, legal fluency across jurisdictions, and robust currency risk frameworks. Ares should commit selectively to beachheads that promise repeat deal flow.
Question mark: Wealth/retail alternatives face a high-growth investor base but require heavy lifts in education, liquidity design and client service; Ares’ scale (AUM ~USD 377bn in 2024) and brand help, yet market share remains contested and outcomes hinge on distribution partnerships and product UX.
Real assets transition platforms (renewables, storage) face undeniable secular tailwinds—US IRA provides about 369 billion in clean energy support through 2031 and global battery storage additions reached ~23 GW in 2023—yet competition and policy risk compress returns. Ares’ share is emerging with lumpy pipelines and high upfront cash burn for origination and technical diligence. Double down on advantaged sponsors and proprietary pipelines, otherwise redeploy.
Question marks (wealth/retail, APAC credit, real-assets transition) show high growth but need heavy distribution, product UX, local teams and cap to win; Ares AUM ~410bn (2024) helps but market share is nascent. Prioritize channels with defensible pipelines, partner distribution, or redeploy capital fast if scale/profitability lags.
| Segment | 2024 metric | Implication |
|---|---|---|
| Wealth/Retail | High growth | Needs distribution + UX |
| APAC Credit | ~120bn AUM | Onshore teams required |
| Real Assets | IRA 369bn | Favor proprietary pipelines |


