
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
Ares Management faces intense rivalry and discerning institutional clients that push for fee transparency and performance differentiation. Supplier influence is moderate—capital providers and distribution partners matter, while scale and regulatory expertise raise barriers to entry. Alternative asset classes and fee compression are notable substitute threats. This brief snapshot only scratches the surface. Unlock the full Porter's Five Forces Analysis to explore Ares Management’s competitive dynamics, market pressures, and strategic advantages in detail.
Access to proprietary transactions is limited and coveted, giving sponsors, banks and intermediaries leverage; Ares offsets this through scale across Credit, PE, Real Estate and Infrastructure that deepens origination channels. In 2024 global private capital dry powder exceeded $2 trillion, and in hot markets competitive auctions push entry multiples higher and compress spreads, increasing supplier power.
Experienced investment professionals and sector experts are key inputs with meaningful bargaining power; Ares manages about $400 billion of AUM as of mid-2024, making talent retention critical to performance.
Retention requires competitive cash pay and the industry-standard 20% carried interest, which can compress fee margins and distributable earnings.
Ares’ multi-asset platform and cross-strategy career mobility reduce flight risk, but top performers still command outsized packages from rivals and new platforms.
Prime brokers, lenders and arrangers set leverage, covenant terms and funding costs for Ares’ deals, constraining structuring flexibility. Tight 2024 credit conditions—Fed funds at 5.25–5.50% and the Fed’s SLOOS showing tighter bank lending standards—increased counterparties’ pricing power. Ares’ large private credit franchise provides internal funding alternatives that partially offset bank dependence. Still, market-wide liquidity shifts can rapidly reprice financing across strategies.
ESG data, analytics, custody and admin providers are largely commoditized but switching costs and integration create frictions; vendor concentration in mission-critical tools can push fees and deepen lock-in. Ares’ 2024 scale (~$378bn AUM) enables multi-vendor sourcing and stronger pricing leverage, yet integration complexity preserves supplier negotiation power.
In co-invests, club deals and sponsor-to-sponsor sales portfolio operators and GPs can set timelines and terms, and when high-quality assets are scarce sellers extract premiums and tighter covenants; cycle peaks in 2024 increased seller leverage across credit and real estate. Ares’ diversified sourcing and roughly $350 billion AUM (2024) helps bypass crowded auctions, moderating supplier power but not eliminating it.
Ares faces moderate-to-high supplier power: talent (20% carry, competitive pay), prime lenders (Fed funds 5.25–5.50% in 2024), and sellers in >$2tn private capital market extract premiums; Ares scale (~$378bn AUM 2024) and internal credit reduce but do not eliminate pressure.
| Supplier | Power | Ares offset |
|---|---|---|
| Talent | High | Cross-asset mobility |
| Lenders | High | Internal credit |
| Sellers/GPs | Moderate | Diversified sourcing |
 Detailed Word Document
Uncovers key drivers of competition, customer influence, and market entry risks for Ares Management, evaluating buyer/supplier bargaining power, rivalry among asset managers, threat of substitutes and new entrants, and identifying disruptive forces that could erode fees or market share.

 Customizable Excel Spreadsheet
A one-sheet Porter's Five Forces for Ares Management that instantly clarifies competitive pressures with a customizable spider chart—ready for pitch decks or boardroom slides, requires no macros, and easily integrates into broader reports or dashboards.
Pension funds, sovereign wealth funds (global SWFs held about 11.4 trillion USD in 2024), and large insurers are sophisticated, high-ticket fee payers whose multi-hundred-million commitments command negotiation leverage on fees and co-invest access.
Ares mitigates pressure via differentiated performance, sector specialization and multi-product cross-selling across credit, private equity and real assets.
Ongoing LP consolidation, with larger allocators growing share, structurally elevates buyer power despite Ares’ defenses.
Industry-wide pressure has pushed median private equity management fees down to about 1.5% while carried interest largely remains at 20%, with scaled separate mandates often negotiating lower effective fees. LPs increasingly benchmark terms across top managers, forcing fee concessions and breakpoints. Ares’ strong performance and niche strategies justify premium pricing versus peers, but marginal products and first-time funds face stricter fee scrutiny.
Ares Management reported AUM of $377 billion as of June 30, 2024, while LPs increasingly push for co-investments and separate managed accounts to cut fee drag, shifting economics away from commingled funds and raising operational complexity. Ares leverages platform deal flow and scale to meet demand and defend blended margins, yet large LPs can still insist on preferential economics.
Wealth platforms diversify Ares’ $382 billion AUM (as of March 31, 2024) but exercise strong due‑diligence and shelf‑access power; product structuring, liquidity features and trail economics regularly compress net fees. Scale distribution reduces advisor/broker‑dealer concentration risk, while education and brand support pricing but do not eliminate buyer leverage.
Allocation pacing and re-ups hinge on net returns versus peers; Ares faces intense buyer scrutiny where underperformance rapidly tightens fundraising and elevates LP demands. Strong, consistent realizations shrink available capacity and blunt buyer power, while 2024 market drawdowns and elevated Preqin dry powder of about $2.1 trillion heightened LP risk aversion and delayed commitments.
Pension funds, SWFs (global SWFs ≈ 11.4 trillion USD in 2024) and large insurers exert high bargaining power, pressing fees, co-invest access and bespoke mandates. Ares (AUM $377B as of June 30, 2024; $382B as of Mar 31, 2024) defends via performance, sector scale and cross‑product selling, but LP consolidation and dry powder (~$2.1T in 2024) sustain pressure.
| Metric | 2024 Value |
|---|---|
| Global SWFs | 11.4T USD |
| Preqin dry powder | 2.1T USD |
| Median PE fee | ≈1.5% |
| Ares AUM | 377B / 382B USD |
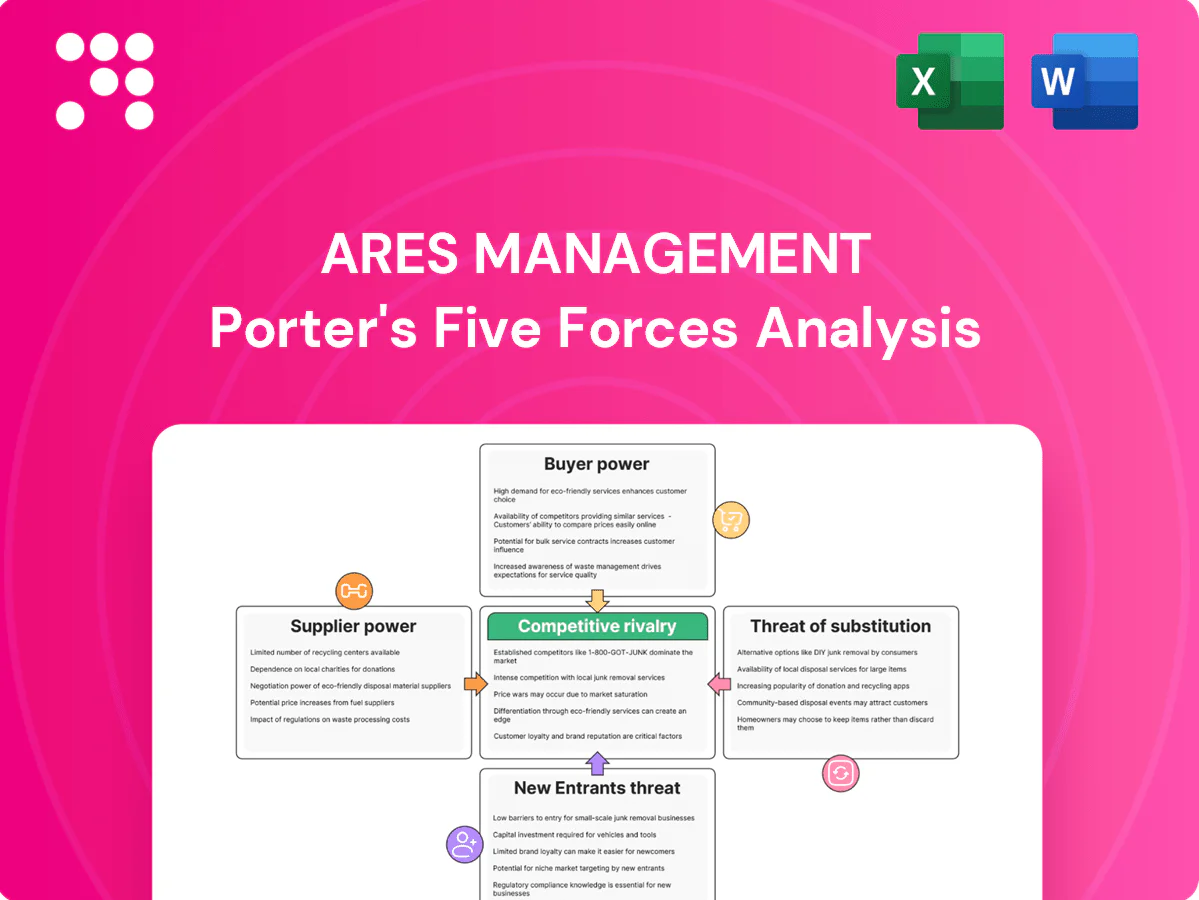
This preview shows the exact Ares Management Porter’s Five Forces analysis you'll receive upon purchase—fully formatted and complete. It provides a detailed assessment of competitive rivalry, buyer and supplier power, and threats of entry and substitution specific to Ares. You’ll get immediate access to this identical file after checkout.
Blackstone, KKR, Apollo, Brookfield and Carlyle aggressively compete across asset classes, collectively managing over $4 trillion of AUM (Blackstone ~$1.6T, Brookfield ~$700B, Apollo/KKR/Carlyle each several hundred billion) and driving highest overlap in private credit, real estate and infrastructure. Scale players bid up assets and compress spreads; private credit yields have tightened ~200–400bps versus 2019 levels. Ares (AUM ~$370B) differentiates via credit leadership and flexible solutions.
Ares’ one-stop platform and reported AUM of $378 billion (June 30, 2024) intensify rivalry as managers compete to be LPs’ core partner across credit, PE, real estate and infrastructure. Breadth boosts wallet share but draws head-to-head battles with Blackstone, KKR and Brookfield for mandates. Pricing, capacity allocations and co-invest rights serve as key competitive weapons.
Performance history drives mandate wins and retention; Ares’ track record — backed by $378 billion AUM reported in 2024 — underpins client confidence and renewal. Top-quartile status across private credit is contested and often decided by narrow spreads, fueling intense competition for allocations. Ares’ scale in private credit enhances origination leverage and tighter terms. Sustained outperformance across cycles is required to defend and grow market share.
Regional and thematic specialists undercut on fees or offer concentrated alpha, intensifying rivalry in niches such as infrastructure adjacencies and opportunistic credit. Ares reported roughly $378 billion of AUM as of June 30, 2024 and counters with dedicated sector teams and thematic funds to protect deal flow and pricing. Specialists still win when differentiation is clear and capacity is scarce.
Rivals aggressively recruit star teams to seed new funds or expand strategies, intensifying talent wars as top-originators can bring institutional relationships and deal flow.
Compensation escalation—base plus signing bonuses and carried-interest sweeteners (carry commonly 20%)—raises fixed costs and rivalry intensity across private markets.
Ares’ scale (total AUM reported at approximately $378 billion in 2024), integrated platform, carry economics, and clear career paths aid retention, yet poaching rises as capital raises accelerate.
Ares faces intense rivalry from Blackstone, KKR, Apollo, Brookfield and Carlyle as scale players (combined >$4T AUM) compress spreads in private credit and real assets; private credit yields tightened ~200–400bps vs 2019. Ares (AUM $378B, Jun 30, 2024) leverages credit depth and thematic teams to defend wallet share and talent.
| Firm | AUM 2024 | Key pressure |
|---|---|---|
| Blackstone | $1.6T | scale bidding |
| Ares | $378B | credit specialization |
LPs can shift to liquid equities and bonds for lower fees and instant liquidity; global ETF assets topped $10 trillion in 2024 and median ETF expense ratios sit near 0.20% versus typical private equity fees of 1.5% management plus 20% carry. In risk-on periods public beta can rival private returns, pressuring Ares' value proposition. Ares leans on illiquidity and complexity premia, but allocation committees may reweight to publics when cross-sectional dispersion narrows.
Large pensions and sovereigns, notably Norway's GPFG (~$1.3tn) and CalPERS (~$470bn), have expanded in-house private markets teams to avoid manager fees and increasingly co-lead or disintermediate managers in core sectors. These direct programs now execute multibillion-dollar deals, posing a credible substitute for sophisticated LPs. Ares, with ~ $425bn AUM in 2024, remains relevant through sourcing, complex structuring and governance expertise.
When banks loosen underwriting, borrowers shift toward cheaper bank financing, pressuring private credit spreads and deal volumes; Preqin reported global private debt AUM near $1.5 trillion in 2024, highlighting the scale at stake. Ares mitigates through bespoke structures, covenants and faster execution, protecting spreads and market share. Regulatory changes that tilt advantages back to banks, such as capital relief measures, would heighten substitution risk.
Hedge fund strategies offering similar return/risk with better liquidity pose a substitution threat; hedge fund industry AUM was about 4.5 trillion in 2024 (HFR). Wealth channels favor daily‑liquidity products in volatile markets, driving reallocations. Ares emphasizes complexity, control and illiquidity premiums to justify private strategies, yet some clients rotate to liquid alts during drawdowns.
Listed infrastructure, REITs and commodities offer liquid proxies that surged in demand when NAV discounts widened to mid-teens in 2023–24; tactical allocators may pivot to these listed substitutes. Ares, with $339 billion AUM (3/31/2024), differentiates via control, operational value creation and bespoke structuring, but faces substitution risk from liquid, lower-cost listed vehicles.
Liquid publics and ETFs (global ETF assets $10T, median expense ~0.20% in 2024) and hedge funds (AUM ~$4.5T in 2024) offer lower‑cost, more liquid substitutes; private debt (~$1.5T) and direct sovereign/pension programs erode fee pools. Ares (~$425B AUM in 2024) defends via control, structuring and illiquidity premia but faces rotation risk in risk‑on or stress liquidity runs.
| Substitute | 2024 metric | Impact |
|---|---|---|
| ETFs | $10T; 0.20% median fee | Liquidity/fee pressure |
| Hedge funds | $4.5T AUM | Liquid alpha alternative |
| Private debt/Direct | $1.5T; large direct deals | Fee disintermediation |
LPs prioritize long, consistent performance histories, which new firms lack, giving established managers like Ares — with roughly $378 billion AUM reported in 2024 — a substantial moat. New entrants struggle to raise flagship funds at scale; industry fundraising shows top 10 managers capture the lion’s share of capital. Seeded spin-outs still face multi-year (typically 3–5 year) validation periods before earning LP trust and significant allocations.
Raised capital hinges on deep LP relationships and a global salesforce; Ares leveraged roughly $385 billion AUM in 2024 and a broad distribution network to secure deals. Building equivalent institutional and wealth-channel coverage is costly and slow, giving Ares a cross-selling edge that deters newcomers. New managers typically accept smaller, niche fund sizes initially, limiting scale competition.
Compliance, risk, valuation and reporting infrastructures require large upfront investment and ongoing expense, and retail-access vehicles introduced in 2024 add significant regulatory hurdles and disclosure demands. New entrants face high fixed costs and complex compliance before reaching profitability. Ares’ operating platform spreads these costs across an over $300 billion AUM base in 2024, lowering per-unit costs as scale increases.
Proprietary capital and warehousing lines let Ares seed deals and show live pipelines, preserving speed and credibility that new managers lack; Ares reported approximately 372 billion dollars of AUM as of mid‑2024, enabling cross‑strategy commits that accelerate closes. Without these resources entrants face slower deployment, weaker pricing leverage and extended hold periods. Ares’ ability to commit capital reduces execution risk and strengthens negotiation outcomes.
Attracting proven teams requires carry economics and brand promises; Ares leverages scale, deep deal flow and a realized track record to offer both — reported $378 billion AUM at 12/31/2024 — making it hard for newcomers to match economics and access. New entrants must either overpay proven teams or accept less experienced teams, reducing their ability to win mandates versus incumbents.
LPs demand long track records and scale; Ares’ $378B AUM (12/31/2024) creates a durable moat, making it hard for new managers to win large allocations. High fixed costs for compliance, reporting and distribution plus 3–5 year LP validation windows raise entry costs and slow growth. Proprietary capital, warehousing and deep sales coverage let Ares seed deals and close faster than entrants.
| Metric | 2024 |
|---|---|
| AUM | $378B |
| LP validation | 3–5 years |
| Entrant scale | Typically small/niche |


