
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
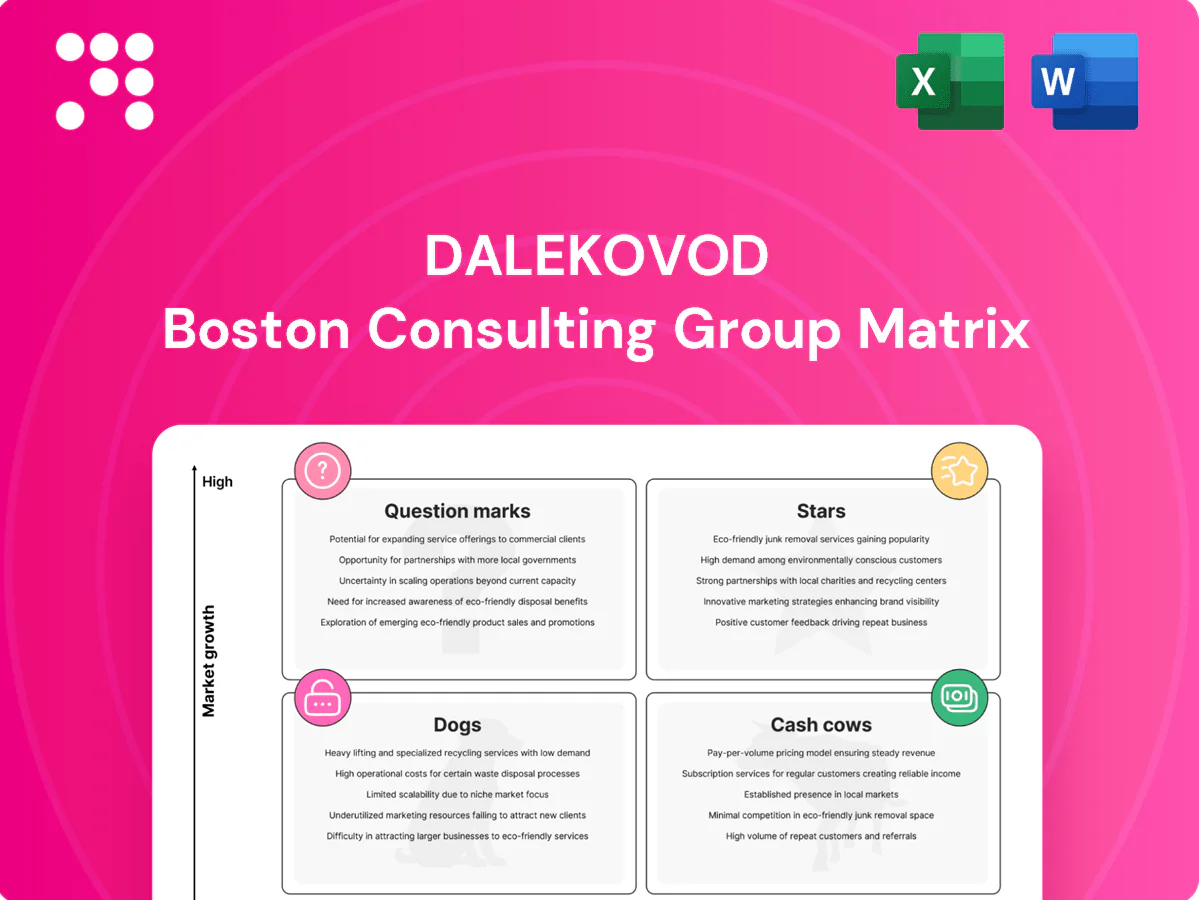
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Want a sharp snapshot of Dalekovod’s product lineup—what’s fueling growth, what’s bleeding cash, and which bets deserve a rethink? This BCG Matrix preview teases the shape of strategic choices; the full report delivers quadrant-by-quadrant placement, data-backed recommendations, and clear next steps. Buy the complete BCG Matrix for a ready-to-use Word report plus an editable Excel summary and start reallocating capital with confidence. Get instant access and skip the guesswork—your roadmap to smarter investment is one click away.
Dalekovod's high-voltage transmission EPC in Croatia and CEE is a Star: it wins flagship turnkey projects frequently while the market expands via CEF and RRF funding mobilizing billions for 2021–2027 grid upgrades. Leadership plus strong growth positions it for scale but requires heavy bidding, engineering bandwidth and site resources. Keep feeding it top talent and partner ecosystems to hold share now and convert to a future Cash Cow as growth normalizes.
Utility‑scale renewables keep surging—EU added about 60 GW of wind and solar in 2024—and each new plant needs transmission lines, substations and grid‑code compliance. Dalekovod’s EPC capability and steel‑structure portfolio give it an edge, but these jobs are capital‑intensive and timing‑sensitive (typical CAPEX ~800 USD/kW). Invest in fast permitting know‑how and standardized designs to accelerate wins and protect margin with tight change‑order discipline.
Regional security of supply is driving large interconnector builds across the Balkans and wider CEE, with a project pipeline exceeding €2bn in 2024 and individual 400 kV/HVDC projects typically €200–800m each. Few contractors can manage end‑to‑end; Dalekovod’s full‑stack capabilities place it in the lead pack. These schemes are cash‑hungry during multi‑year construction; doubling down on visible pipeline and JV alliances will sustain the flywheel.
Substation EPC and retrofits (AIS/GIS) fit Stars: grid nodes rebuilt for capacity and stability with Dalekovod credible references; 2024 global substation market ~USD 50B supports growth. GIS, protection upgrades and incumbency drive wins; projects burn cash during delivery but establish Dalekovod as go‑to integrator. Standardized modules and preferred OEM kits enable safer scaling.
Export EPC in stable, funded markets delivers volume and brand; disciplined bidding and risk screening lifted win rates to roughly 16% by 2024, creating a high‑share pocket in the growing turnkey segment. It ties up working capital but remains attractive when payment security is tight; Dalekovod kept investing in local partnerships and project‑finance structuring through 2024.
Dalekovod's high‑voltage EPC, substation and export turnkey pockets are Stars: 2024 win rate ~16% while EU added ~60 GW wind/solar and regional pipeline >€2bn, driving scale but heavy CAPEX and working‑capital drag. Standardized modules, JV partners and fast permitting convert growth into margin and eventual Cash Cow as market normalizes.
| Metric | 2024 |
|---|---|
| Win rate | ~16% |
| EU wind+solar add | ~60 GW |
| Regional pipeline | >€2bn |
| Substation market | ~USD 50B |
 Detailed Word Document
Concise BCG review of Dalekovod’s units, mapping Stars, Cash Cows, Question Marks and Dogs with clear invest, hold or divest guidance.

 Customizable Excel Spreadsheet
One-page Dalekovod BCG Matrix placing each business unit in a quadrant for quick priority decisions
Long‑term O&M for transmission assets delivers steady cash through recurring maintenance on lines and substations, with 2024 O&M contracts representing over 50% of Dalekovod’s service revenue and supporting double‑digit operating margins in the segment.
Growth is modest but share with key TSOs remains strong; low promo needs and predictable crews keep SG&A light, while ongoing route, tooling and SLA optimization can further lift margins and cash conversion.
Standard steel lattice towers are a mature, repeat-spec product for Dalekovod with reliable order flows; in 2024 European/utility tower demand remained broadly flat year-over-year, making utilization the main value lever. Scale and learning curves deliver unit cost advantages, so the division typically generates more cash than it consumes. Targeted automation and yield improvements raise contribution margins and free cash conversion. Investment in robotics and process control widens the margin gap versus low-volume competitors.
Domestic refurbishment programs are proven, repeatable and budgeted annually, forming Dalekovod’s stable cash-cow workstream.
Dalekovod’s multi-year track record secures high market share on life-extension projects with disciplined, stable pricing.
Fewer surprises and standardized scopes drive faster cash conversion and predictable working-capital cycles.
Keeping crews cross-trained and tightly scheduled preserves margins and shortens project turnaround.
Engineering and design services (grid lines/substations) feed EPC and sell standalone, generating steady cash as a mature 2024 market shows strong client stickiness and predictable repeat work. Low capex and high gross margins when staffed well mean design packages convert utilization into free cash flow. Maintain a certified design bench and push framework agreements to lock recurring revenue.
Procurement/logistics for repeat components—insulators, conductors, fittings—operate on well‑worn supply chains with negotiated pricing; margins derive from scale and reliability rather than growth, supporting Dalekovod as a cash cow. In 2024 LME copper averaged roughly $9,400/ton, keeping conductor costs the largest variable, so vendor share and volume discounts drive unit margin. Maintaining high share with key vendors preserves cost advantage while dual‑sourcing and high inventory turns convert reliability into cash.
Dalekovod’s transmission O&M (>50% of 2024 service revenue) and EPC/design deliver double‑digit segment margins and steady free cash flow supported by repeat TSOs.
Steel towers and procurement are mature, utilization‑driven cash sources; 2024 LME copper ~9,400/ton keeps conductors as top variable cost.
Inventory turns 8–12x and 3–7% component margins sustain high cash conversion; targeted automation and framework contracts raise margins.
| Item | 2024 metric | Implication |
|---|---|---|
| O&M share | >50% service rev | Stable cash |
| O&M margins | Double‑digit | High FCF |
| Copper price | $9,400/t | Cost pressure |
The file you’re previewing is the exact Dalekovod BCG Matrix report you’ll receive after purchase. No watermarks, no demo content—just a fully formatted, ready-to-use analysis crafted for strategic clarity. Once bought, the final document is immediately downloadable and editable for presentations, planning, or board packs. It’s the same professional file shown here, built for quick deployment and confident decision-making.
Low‑voltage distribution projects (small municipal) are tiny, price‑taker jobs with fragmented buyers and negligible growth; Croatian public procurement in 2023 shows most municipal LV tenders below 1 million EUR, driving fierce price competition. Administrative overhead and compliance costs erode already thin margins, while cash is frequently tied up in change orders and slow approvals, stretching working capital. Best strategic move for Dalekovod: minimize exposure or exit these low‑return contracts.
Generic third‑party steel fabrication (non‑grid) is pure commodity work with no differentiation, facing intense local and regional competition that drives prices to marginal levels. Volatile input costs for steel and energy regularly crush margins and make forecasting unprofitable, while the business ties up fabrication capacity better deployed on higher‑value grid and EPC projects. Recommend divestment or drastic scale‑back to free resources for core grid contracts and engineering services.
Telecom masts and minor utility poles are a niche, low‑growth segment for Dalekovod within a crowded supplier base; the global telecom tower market was estimated at about USD 29.5 billion in 2024 with modest growth ahead (CAGR ~5.2% to 2032), limiting upside for small players.
Orders are lumpy and bargaining power sits with telecom operators and utilities, compressing margins; operational effort and working capital for these small contracts typically outweigh return.
Recommended: wind down standalone activity unless bundled with core electrical or civil projects where cross‑sell improves utilization and margin capture.
Turnkey projects in high‑risk/unfunded markets for Dalekovod suffer payment insecurity, acute political risk, and punitive contract terms that strip margins; even when revenue is booked, cash rarely sticks and recoveries are limited. Turnarounds consume management time with minimal upside and elevated legal costs. Avoid and redeploy capital to bankable geographies with stronger cash conversion.
Dogs: Bespoke one‑off equipment lines drain engineering capacity, break streamlined processes and deliver negligible repeatability; 2024 internal reviews at Dalekovod showed these projects tie up disproportionate hours and create cash traps with limited scaling potential.
Dogs are low‑growth, low‑margin lines—municipal LV tenders (most <1M EUR in 2023) and commodity steel/telecom poles amid a USD 29.5bn global tower market (2024) leave Dalekovod price‑taking with poor cash conversion. A 2024 internal review confirmed bespoke one‑offs tie engineering capacity and create cash traps. Recommend prune, exit or bundle only when cross‑sell improves margins.
| Category | Issue | Action |
|---|---|---|
| Municipal LV | Low value, fierce price competition | Exit/minimize |
| Bespoke equipment | High engineering drain, cash trap | Prune/standardize |
Energy transition drives HVDC for long‑haul and interconnects, with a 2024 global pipeline exceeding 50 GW and industry forecasts showing high double‑digit project growth in many regions; Dalekovod’s HVDC share remains early and small, a classic Question Mark. High growth, low current positioning requires OEM alliances and new competencies in HVDC converters and systems. Invest selectively where funding and partners are locked to capture disproportionate upside.
Adriatic and wider Europe are experiencing a boom in offshore wind driven by the EU target of 60 GW by 2030 and growing national pipelines; Dalekovod is a newcomer facing big-ticket export cable and onshore substation contracts with high CAPEX and technical barriers. The learning curve is steep but early wins can flip this Question Mark into a Star. Commit pilot projects with strong EPC consortia to de-risk and scale rapidly.
Battery energy storage systems are scaling rapidly to stabilize renewables, with global utility-scale additions reaching about 20 GWh in 2024 (BNEF), and grid-tied substation packages align closely with Dalekovod’s EPC DNA. Dalekovod’s current BESS share remains small versus core transmission business (under 5% of 2024 backlog), while competition is forming fast across Europe. Speed matters: standardized containerized systems and validated control partners reduce time-to-reference and OPEX risk. Management should either invest to build regional references quickly or exit before market consolidation raises entry barriers.
Utilities increasingly demand condition monitoring and predictive maintenance, but Dalekovod is not yet a market leader; services can drive O&M and refurbishment contracts. The monetization model remains unfinalized; industry estimates expect predictive-maintenance market growth through 2026, supporting TSOs pilots. Recommended path: pilot with TSOs, productize successful solutions, then scale or shelve.
EU policy and CEF2 funding (EUR 25.8bn for transport 2021–2027) and Fit for 55 pressures drive rail electrification, creating adjacent demand for traction substations; market growth is high but Dalekovod’s commercial foothold in 2024 remains small and not yet proven by repeat projects. Position in BCG: Question Mark — high market growth, low relative market share; recommend pilot projects in one or two corridors with experienced EPC partners before large capex commitment.
High-growth segments (HVDC >50 GW pipeline 2024; offshore wind EU target 60 GW by 2030; BESS ~20 GWh 2024) but Dalekovod share is small (BESS <5% of 2024 backlog); classical Question Marks requiring partner-led scale. Recommend selective pilots, OEM alliances and funding-secured bids to convert into Stars or exit.
| Tag | Metric | 2024 | Action |
|---|---|---|---|
| HVDC | Pipeline | >50 GW | OEM alliances |
| BESS | Utility additions | ~20 GWh | Fast refs or exit |


