
Digital download
Access the files immediately after checkout.
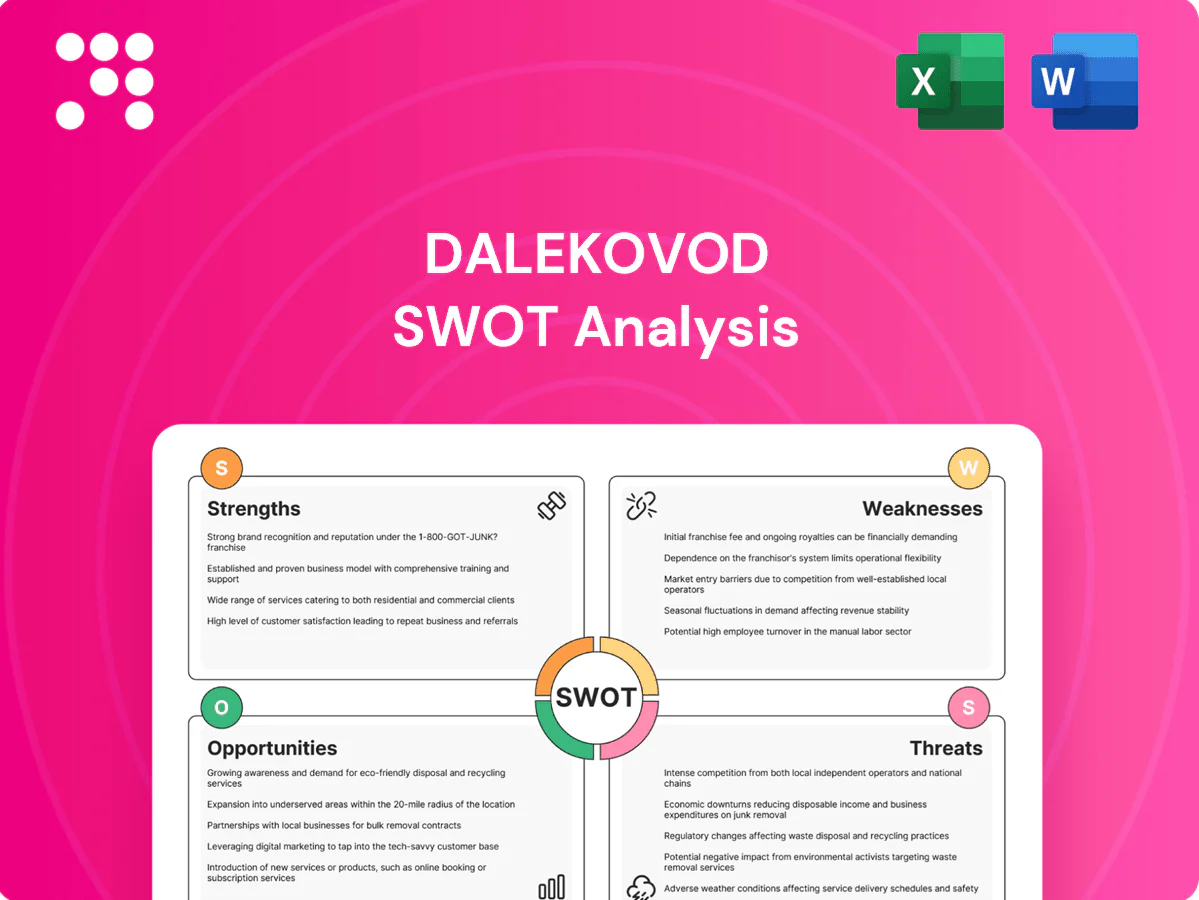
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
Dalekovod's strengths in engineering and regional presence contrast with project concentration and market cyclicality; our concise SWOT highlights these dynamics and strategic levers. Want the full story—purchase the complete SWOT to access a professionally written, editable report with financial context and actionable recommendations. Ideal for investors, advisors, and managers planning growth or risk mitigation.
Dalekovod delivers engineering, procurement and construction under a single contract, simplifying interfaces for utility clients and lowering administrative overhead. This integrated EPC model reduces schedule risk and cost overruns—industry studies indicate EPC approaches can cut delay-related losses by up to 30%—and enables tighter quality control from design through commissioning. The one-stop offering is increasingly attractive for grid expansion and refurbishment amid rising European network investments.
Dalekovod, founded in 1949 and with 75 years of experience by 2024, specializes in design and construction of high-voltage transmission lines and substations. This niche expertise improves execution efficiency and safety outcomes on projects across Croatia and regional cross-border corridors. Proven standardized designs and methods reduce clients' lifecycle costs and strengthen bid credibility in complex terrains.
Owning in-house steel structure manufacturing gives Dalekovod supply assurance and customization flexibility, allowing tailored towers and components to client specs. Vertical integration compresses lead times and protects margins by eliminating external supplier markups. The facility supports rapid response to change orders, accelerating project schedules. Full quality traceability from mill to site differentiates the offering for risk-sensitive clients.
Dalekovod leverages international project experience to expand its addressable market beyond Croatia, reducing reliance on domestic demand and allowing redeployment of proven teams and methods across regions; the company, founded in 1949 and listed on the Zagreb Stock Exchange, uses cross-border references to strengthen prequalification in tenders and its familiarity with differing grid codes and permitting regimes lowers project friction.
Decades in power transmission have built trust with utilities, EPC partners and financiers, driving repeat business and framework agreements that stabilize backlog. Brand recognition can lower bid bonds and streamline due diligence, and supports talent attraction in a tight engineering labour market.
Dalekovod offers integrated EPC delivery that can reduce delay-related losses by up to 30%, enabling tighter cost and schedule control. Founded in 1949 (75 years by 2024) and listed on the Zagreb Stock Exchange, the company leverages long-term utility relationships and repeat contracts to stabilise backlog. In-house steel manufacturing secures supply and margin protection while supporting rapid project response.
| Metric | Value |
|---|---|
| Founding year | 1949 |
| Years of operation (2024) | 75 |
| Estimated EPC delay reduction | up to 30% |
 Detailed Word Document
Delivers a strategic overview of Dalekovod’s internal and external business factors, outlining strengths, weaknesses, opportunities and threats to assess its competitive position, identify growth drivers and operational gaps, and highlight risks shaping the company’s future.

 Customizable Excel Spreadsheet
Provides a concise, visual SWOT matrix for Dalekovod to quickly identify strengths, weaknesses, opportunities and threats, streamlining strategic decisions and stakeholder alignment.
Dalekovod's large EPC contracts create lumpy revenue and cash flows; mobilization often requires 10–20% of contract value, straining working capital and milestone billing timing. Delays in permits or land acquisition can push revenue recognition by several months, increasing cash-flow volatility with quarterly swings commonly exceeding 25%. This volatility complicates capacity planning and timely debt service.
Dalekovod remains heavily concentrated in transmission and distribution, with a majority (>50%) of revenues tied to T&D projects, limiting business diversification. Downturns or regulatory pauses in grid capex can materially dent utilization and backlog, increasing short-term volatility. Adjacent segments such as rail electrification and telecom towers appear underdeveloped relative to T&D, so portfolio concentration elevates earnings risk.
Competitive public tenders, which represent about 14% of EU GDP, compress pricing and shift risk to contractors; Dalekovod faces margin erosion when fixed-price bids lock in costs while commodity and labor inflation rises. Slow approval of change orders delays recovery of extra costs, and high bid costs strain overhead when win rates decline, magnifying margin pressure.
Mid-sized Dalekovod faces difficulty competing with global EPCs on mega-projects, limiting access to the largest contracts and keeping average project size below top-tier peers. Establishing a local footprint in new markets raises setup and bonding costs, while stringent local content and compliance rules increase entry barriers and cap backlog depth.
Project execution ties up cash in inventory, advances and retention, pressuring liquidity; long receivable cycles with public clients push DSO higher, delaying cash conversion. Performance guarantees and warranty reserves lock capital and reduce available funds, while financing costs on working-capital facilities erode margins on low-price contracts.
Large EPC contracts require 10–20% mobilization and cause lumpy revenue with quarterly swings commonly >25%, straining working capital and debt service. Revenue concentration (>50% in T&D) and underdeveloped adjacent segments raise earnings risk. Competitive public tenders (market ~14% of EU GDP) compress margins and delay change-order recoveries.
| Metric | Value |
|---|---|
| Mobilization | 10–20% |
| Quarterly swings | >25% |
| T&D revenue share | >50% |
| Public tender market | ~14% EU GDP |
This is the actual Dalekovod SWOT analysis document you’ll receive upon purchase—no surprises, just professional quality. The preview below is taken directly from the full SWOT report you'll get, and the complete, editable version is unlocked after payment. Buy now to download the full, detailed file ready for use.
EU decarbonization and cross‑border plans (2030 electricity interconnection target 15%) are driving strong T&D demand, especially for renewables integration and new lines/substations. Upgrades and permitting acceleration via EU funding streams like Connecting Europe Facility (energy envelope €5.84bn for 2021‑2027) can speed project approvals. Dalekovod can pursue turnkey HV packages aligned with these funded priorities and its high‑voltage expertise.
Wind, solar and BESS projects require grid tie‑ins and substation upgrades, creating EPC scope for collector systems and grid‑code compliance; ENTSO‑E estimates ~€190–200bn grid investment to 2030, while Europe’s BESS pipeline exceeds 100 GW by 2030. Co‑locating manufacturing with delivery shortens timelines and boosts cross‑sell of steel structures and installation services, improving project margins and working‑capital turnover.
Climate-driven asset stress is boosting demand for reconductoring, tower replacements and undergrounding, supported by EU NextGenerationEU funds of €723 billion that prioritize energy resilience. Utilities across Europe and North America report rising resilience capex, and Dalekovod can win retrofit programmes and condition-based maintenance contracts. Offering framework contracts would convert project wins into predictable, recurring revenue. Such services align with increased fire-mitigation spending and grid-hardening mandates.
Emerging CEE and MENA markets require transmission buildouts to meet projected demand growth of roughly 3–5% annually through 2030, creating sizable contract pipelines; targeted local partnerships help satisfy content rules and cut entry risk. Pre-bid alliances with OEMs improve bankability, often enabling 70–80% project debt financing, while pursuing mid-size lots preserves Dalekovod’s balance sheet and cash ratios.
EU decarbonization funding and CEF (€5.84bn energy 2021‑27) plus NextGenerationEU (€723bn) boost T&D tenders, enabling Dalekovod to target turnkey HV packages. ENTSO‑E grid capex €190–200bn to 2030 and Europe BESS >100GW by 2030 create large EPC and O&M pipelines. Digital tools (predictive O&M, drones) cut costs and enable multiyear service revenues.
| Opportunity | Metric | 2024/25 |
|---|---|---|
| EU funding | CEF / NextGenEU | €5.84bn / €723bn |
| Grid investment | ENTSO‑E to 2030 | €190–200bn |
| BESS pipeline | Europe by 2030 | >100 GW |
| CEE/MENA demand | Annual growth | 3–5% pa |
Steel price swings and transport disruptions can squeeze fixed-price contracts for Dalekovod, with volatility pressuring margins; Croatia adopted the euro on 1 January 2023, reducing kuna risk but leaving exposure to USD/CNY for imported inputs.
Supply-chain shocks have lengthened lead times for conductors and critical equipment to several months in peak periods, inflating working capital needs, and hedging may not fully offset rapid market moves.
Transmission projects face complex environmental and community approvals that in Europe often extend 3–5 years, stalling construction and cashflows. Legal challenges can halt sites and escalate costs, with delays commonly shaving 200–400 basis points off project IRR. Post-election policy shifts can reprioritize budgets, delaying tenders. Prolonged permitting can force client scope reductions of up to ~20%, compressing margins.
Global EPCs and low-cost regional players are forcing down margins as the global EPC market is estimated at about USD 820 billion in 2024 with growth to ~USD 1.1 trillion by 2028, intensifying price pressure. OEM-led turnkey offerings from firms such as Siemens and GE bundle equipment plus construction, shortening bid cycles and squeezing specialist contractors. Ongoing consolidation among competitors increases bidding power and erodes Dalekovod's win rates and negotiation leverage.
Experienced linemen, welders and HV engineers remain scarce, increasing reliance on a limited skilled workforce and raising delivery risk through wage inflation and long training lead times. Safety incidents involving understaffed crews can halt projects and damage Dalekovod’s reputation. Persistent talent scarcity constrains capacity to accept new contracts and scale operations quickly.
Utilities and state entities delaying payments or cutting capex in downturns heighten Dalekovods counterparty risk; delayed receivables and higher DSO undermine liquidity and project financing. Rising interest rates (ECB policy around 4% in 2024) can postpone projects or force scope reductions, increasing bad-debt exposure and cash-flow unpredictability.
Steel-price and shipping volatility, plus 3–6 month lead times for critical kit, compress fixed-price margins and raise working-capital needs; USD/CNY exposure persists post-euro adoption. Intense global EPC competition (USD 820bn market in 2024; ~USD 1.1tn by 2028) and OEM turnkey bids erode win rates. Public capex delays, higher rates (~4% ECB 2024) and stretched DSO amplify liquidity and bad-debt risk.
| Threat | Key metric |
|---|---|
| Global EPC market | USD 820bn (2024) → ~USD 1.1tn (2028) |
| Lead times | 3–6 months peak |
| ECB rate | ~4% (2024) |
| DSO impact | Delayed payments ↑ liquidity strain |


