
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
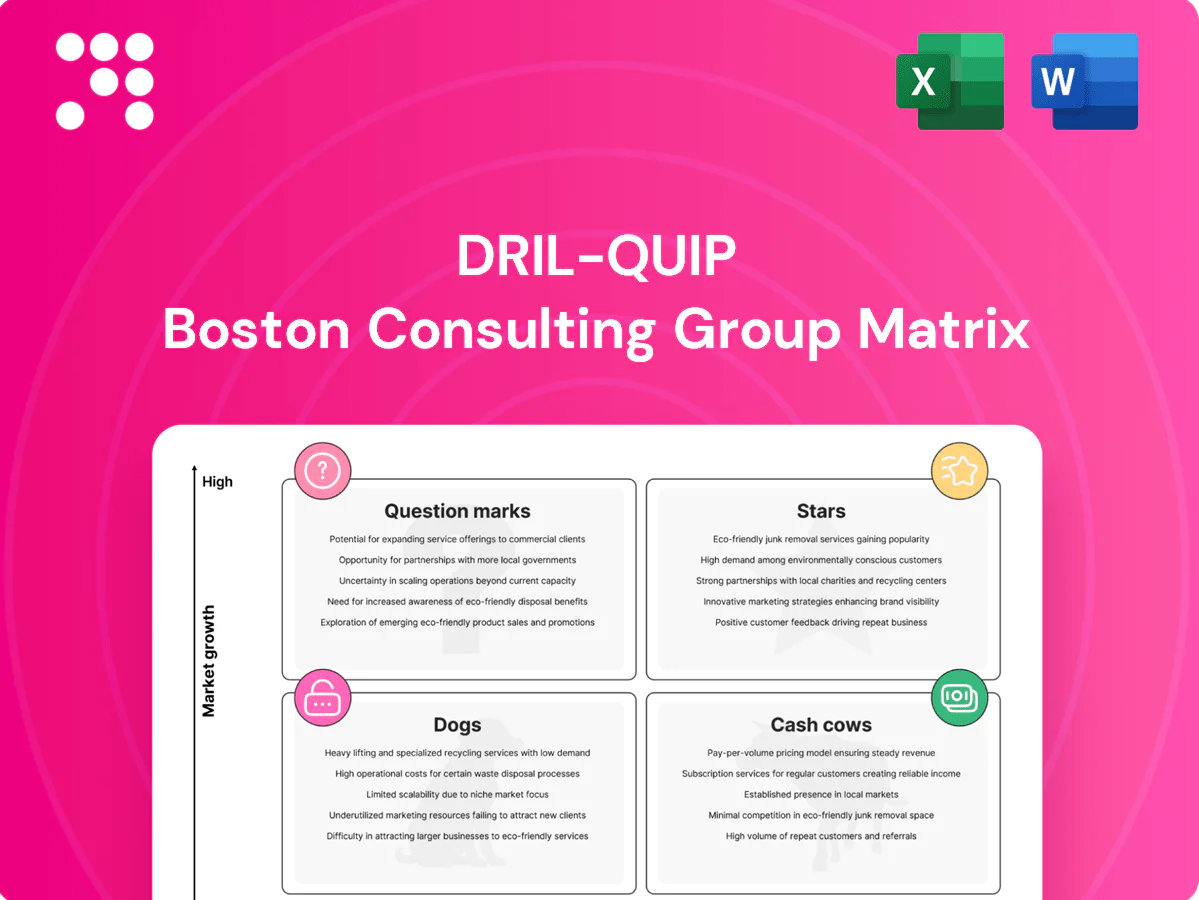
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Want to know which Dril‑Quip products are fueling growth and which are quietly bleeding cash? This preview hints at positions, but the full BCG Matrix shows exact quadrant placements, hard data, and clear strategic moves you can act on. Buy the complete report for a Word deep‑dive plus an Excel summary—ready to present and use in decision meetings. Skip the guesswork; get instant, practical clarity and a roadmap for smarter capital allocation.
High-growth deepwater basin activity keeps complex subsea wellheads in demand and Dril-Quip competes at the premium end, with strong share where specs are tight and failure is not an option; they absorb significant engineering and service cash but the project pipeline remains hot, so continue investing to maintain leadership while the market is still sprinting.
Deepwater (>1,000 ft) and HP/HT (commonly >15,000 psi and >150°C) require premium subsea trees, positioning Dril-Quip in the sweet spot for complex fields. Major deepwater projects often exceed $500m capex and favor proven suppliers with global service networks, supporting premium pricing. Margins on premium subsea trees are healthy but project delivery is capital intensive—protect wins, standardize interfaces, then convert scale-driven growth into predictable cash cows.
Ultra‑deepwater risers (>1,500 m) are mission‑critical, highly specified systems that favor incumbents with proven track records and specialist supply chains. Demand follows multi‑year field developments—typical sanction‑to‑first‑oil timelines are 3–7 years—so visibility into follow‑on volumes is decent. Cash burn is concentrated during build and install phases, requiring significant near‑term working capital; doubling down on delivery excellence secures follow‑on scopes.
Integrated design-to-service packages answer operators demanding fewer interfaces and clearer accountability; bundling Dril-Quip hardware with installation and lifecycle services increases win rate on complex projects, ties up upfront resources but protects margin and customer stickiness, and is most scalable where the installed base is dense.
Harsh-environment solutions are Stars for Dril-Quip: Arctic, HP/HT and cyclone-prone fields demand engineered toughness, driving higher engineering hours and premium pricing; 2024 offshore sanctioning rebound (Rystad Energy: +18% year-on-year) is expanding these niches and wins secure long-term margin uplift. Stay visible in concept select and co‑engineer with tier‑one operators to anchor contracts early.
High-growth deepwater and HP/HT demand keeps Dril‑Quip’s premium subsea trees and integrated services in Star position; wins are capital‑intensive but secure follow‑on scopes. 2024 offshore sanctioning rose +18% (Rystad), supporting multi‑year pipelines and >$500m capex projects with 3–7y sanction→FO timelines. Focus: early co‑engineering, delivery excellence, bundle services to convert growth to predictable cash.
| Metric | 2024 | Implication |
|---|---|---|
| Offshore sanctions | +18% (Rystad) | Expanding Star pipeline |
| Typical project capex | >$500m | Favors proven suppliers |
| Sanction→FO | 3–7 years | Multi‑year visibility |
 Detailed Word Document
Comprehensive BCG review of Dril-Quip products, pinpointing Stars, Cash Cows, Question Marks and Dogs with investment guidance.

 Customizable Excel Spreadsheet
One-page Dril-Quip BCG Matrix placing each business unit in a quadrant to simplify strategy and speed C-suite decisions.
Standardized specialty connectors move predictably across projects and regions, generating steady repeat orders and predictable cash flow. Mature specifications and efficient, high-throughput manufacturing keep margins robust while promotion spend remains minimal. Delivery reliability is the commercial edge, supporting long-term OEM and operator contracts. Capex should stay tight and cycle times compressed to maximize cash yield.
Once installed, Dril-Quip equipment requires routine inspections, recerts and call‑out support, driving predictable service demand; aftermarket often delivers high single‑to‑low double‑digit organic growth but low market expansion. Recurring revenue yields solid margins, typically in the 20–30% range, and funds capital deployment for R&D and M&A. Maintain minimal investment in tooling and technicians to keep uptime best‑in‑class while preserving cash flow for strategic bets.
Operators stock critical spare parts for subsea assets, producing predictable, sticky demand with attachment rates exceeding 80% to Dril-Quip’s installed base in 2024. Low sales effort and high reuse mean selling costs are minimal while aftermarket gross margins run roughly 30–50%, making this business highly margin‑accretive and operationally simple. Prioritize pricing optimization and guaranteed availability, while pruning SKUs to avoid over‑complexity and inventory drag.
Brownfield upgrades/retrofits sit squarely in Dril-Quip’s Cash Cows: mature fields prefer incremental upgrades over rip‑and‑replace, lowering execution risk and shortening sales cycles. Known interfaces mean faster approvals and predictable margins; 2024 Rystad Energy estimates global brownfield offshore spend around USD 40 billion, keeping steady cash flow. It’s not flashy growth, but retrofits deliver strong cash conversion; standardize kits and streamline approvals to keep throughput high.
Training and certification programs generate a quiet annuity for Dril-Quip by mandating proprietary-system training tied to service contracts, keeping recurring revenue and customer lock-in while requiring low incremental capex and repeat sessions.
They improve customer stickiness and operational safety, and digitizing modules scales delivery to widen margins without adding headcount.
Cash cows: standardized connectors, aftermarket spares, brownfield retrofits and training deliver steady, high‑margin cash (aftermarket gross 30–50%, service margins 20–30%), low capex and high attachment (>80% in 2024), funding R&D/M&A; focus on pricing, SKU pruning, inventory turns and compressed cycle times.
| Segment | 2024 metric | Typical margin | Capex |
|---|---|---|---|
| Connectors | Repeat orders, global | ~30–40% | Low |
| Aftermarket spares | Attachment >80% | 30–50% | Very low |
| Retrofits | Brownfield spend ~USD 40B | 20–30% | Moderate |
| Training | Recurring annuity | High (digital scale) | Minimal |
The file you're previewing is the exact Dril-Quip BCG Matrix you'll receive after purchase—no placeholders, no watermarks, just the finished report. Crafted for clarity and strategic use, it includes market-backed analysis and clean formatting. Buy once and download immediately; it's ready to edit, print, or present. No surprises—what you see is what you get.
Shallow‑water conventional gear sits in a low‑growth 2024 segment with heavy price pressure and abundant substitutes, driving gross margins often under 10% and compressing profitability.
Little room exists to differentiate versus low‑cost manufacturers, while cash is tied up in inventory (inventory days frequently >120) with thin returns.
Minimize exposure and exit SKUs that do not feed larger systems or integrated offerings to preserve cash and redeploy capital.
One‑off highly bespoke builds showcase cool engineering but deliver lousy economics: bespoke jobs at comparable oilfield OEMs typically reduce gross margins by 5–10% versus standard products. Unique parts drain engineering and procurement resources and rarely repeat, driving unit costs up. Schedule risk frequently erodes margin as overrun rates approach industry averages. Push customers toward modular, standardized options or walk away.
Legacy variants with outdated specs linger in catalogs yet show negligible demand, creating supply-chain and QA complexity without revenue growth or ROI. Continuing support ties up procurement, spare-parts inventory, and testing resources while offering no clear payback. Rationalize and sunset these SKUs promptly, with defined migration paths, cross-reference charts, and phased support windows to minimize field disruption.
Low-volume regional SKUs tailored to a single regulator or operator frequently stall sales cycles and create sporadic demand that inflates per-unit servicing costs; approvals granted by one authority rarely transfer to others, forcing duplicated certification work and parts obsolescence. Holding slow-moving inventory raises carrying costs and working capital strain, so consolidate into global SKUs where feasible to improve turnover and reduce certification redundancies.
Dogs:
Competing here distracts from engineered, high‑spec systems that delivered Dril‑Quip 2024 core margins above 18%; divest or outsource low‑value supply and redeploy capital to specialized offerings.
Commodity components yield 4–7% gross margins in 2024 versus Dril‑Quip core engineered margins >18%; they act as cash traps and depress overall ROI. Inventory days often exceed 120, tying working capital. Divest or outsource noncore SKUs, consolidate approvals, and redeploy capital to high‑spec systems.
| SKU | 2024 GM | Inv days | Action |
|---|---|---|---|
| Commodity parts | 4–7% | >120 | Divest/Outsource |
| Engineered systems | >18% | 60–90 | Invest |
Digital monitoring & condition-based maintenance sits in Question Marks: operator interest is high while share is still forming, with the predictive maintenance market at about $6.3B in 2023 and rapid growth expected. Implementation requires software, data integration, and proof of value; pilots typically show 10–30% uptime gains. It burns cash early but can unlock sticky service pull-through; pilot hard with anchor clients and measure uptime improvements.
Industry is testing all‑electric subsea architectures in 2024 to cut emissions and simplify topsides, with pilot programs by major operators such as Equinor and Shell. Market growth could accelerate if reliability proves out, driven by decarbonization targets and cost-of-ownership gains. Dril‑Quip has an entry point but current commercial share remains limited. Bet selectively on high-visibility reference projects to climb the adoption curve.
CCUS and geothermal are adjacent markets needing rugged well equipment with tweaks, not reinvention; as of 2024 there are 30+ large-scale CCUS facilities and roughly 16 GW global geothermal capacity, signaling hot growth but fluid standards. Early moves consume capital and engineering bandwidth without guaranteed volumes, so place options with partners and keep designs modular to protect capital and enable rapid adaptation.
Question Marks: Intervention & light‑well systems face rising interest as 2024 cost‑down cycles pushed operators toward lighter intervention packages; early demand rose ~10% year‑on‑year in targeted basins. Adoption varies by basin and operator comfort; could scale via strategic alliances or remain a niche. Pilot go‑to‑market in 3–5 basins and monitor win rates closely.
In 2024 emerging offshore provinces (Guyana, Brazil’s pre-salt satellites, West Africa, and Mexico) accelerated requests for integrated turnkey packages while incumbents such as Subsea 7 and TechnipFMC remain entrenched; winning one flagship project often produces follow‑on momentum, whereas a lost bid converts engineering and mobilization spend into sunk cost.
Digital monitoring: $6.3B predictive maintenance market (2023); pilots show 10–30% uptime gains. All‑electric subsea: 2024 operator pilots (Equinor, Shell)—commercial share small but strategic. CCUS/geothermal: 30+ large CCUS facilities, ~16 GW geothermal (2024) — modular designs reduce risk. Intervention growth ~10% in targeted basins (2024); target 3–5 basins for pilots.
| Opportunity | 2023/24 metric | Action |
|---|---|---|
| Digital monitoring | $6.3B (2023); 10–30% uptime lift | Pilot with anchor clients |
| All‑electric subsea | 2024 operator pilots (Equinor, Shell) | Selective flagship bets |
| CCUS/geothermal | 30+ CCUS facilities; ~16 GW geothermal (2024) | Modular designs, partner options |
| Intervention | ~+10% demand in 2024 basins | Pilot in 3–5 basins |
| Emerging provinces | Rising turnkey requests (2024) | Target flagship wins, limit capex |


