
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
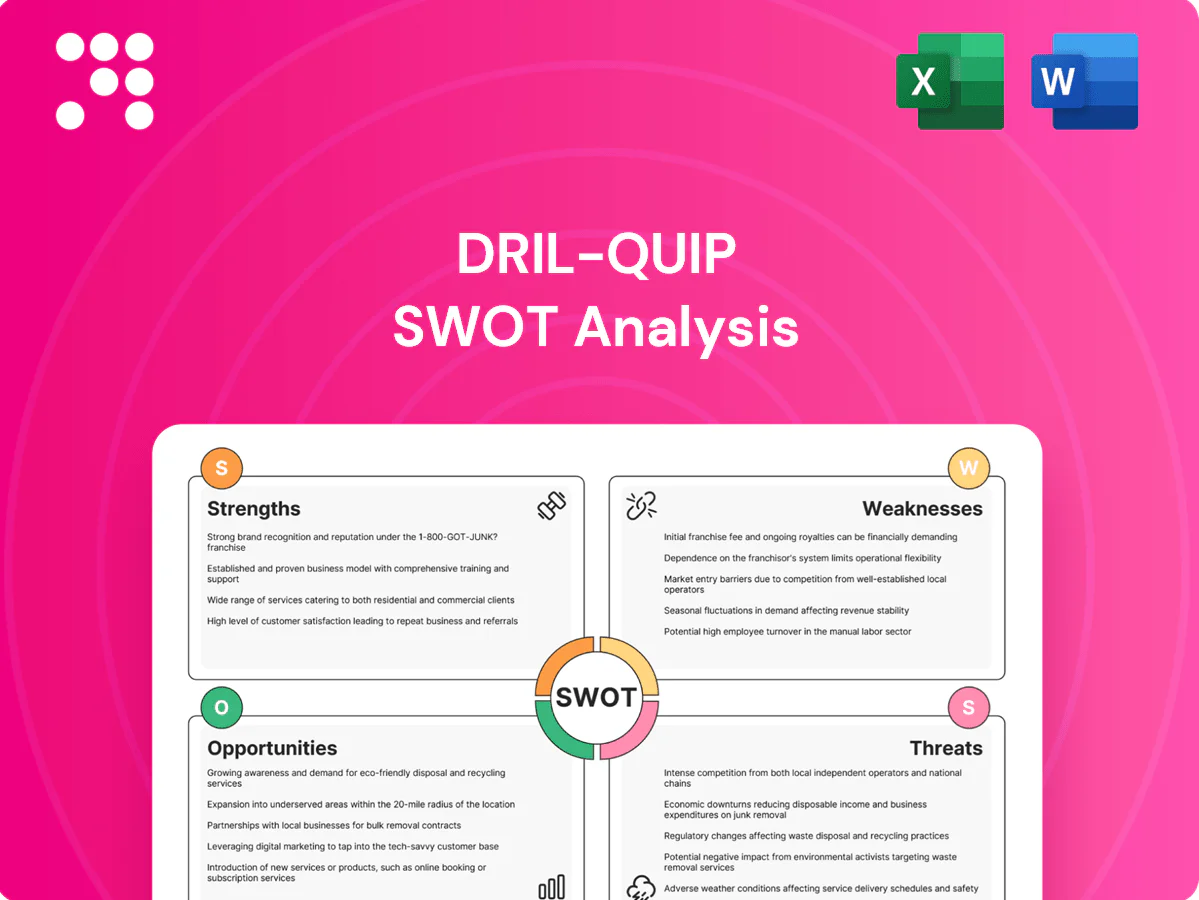
Our Dril-Quip SWOT snapshot highlights strong product innovation and aftermarket services, offset by oil-price sensitivity and competitive pressure; regulatory and supply-chain risks could constrain growth. Want the full strategic picture? Purchase the complete SWOT analysis for an editable, research-backed Word and Excel package to plan, pitch, or invest with confidence.
Deepwater engineering prowess: with over 44 years in high-spec designs for deepwater and harsh environments, Dril-Quip has built technical moats through precision and reliability. This engineering credibility shortens qualification cycles with major operators and supports warranty-sensitive contracts. The niche focus enables premium pricing on mission-critical equipment, bolstering resilience in tendering for deepwater projects.
Dril-Quip’s comprehensive subsea portfolio spans wellheads, trees, risers and specialty connectors, enabling bundled solutions that simplify supplier interfaces for operators. Founded in 1981 (44 years in 2025), the broad catalog facilitates cross-selling on complex projects, increasing share of wallet and commercial efficiency. Integrated offerings enhance customer stickiness across full field life cycles, reducing touchpoints and procurement complexity.
Serving integrated majors, independents and NOCs diversifies end-market exposure and reduces dependency on any single customer segment. Multi-region presence helps balance regional cycles and supports revenue resilience. Established relationships drive frame agreements, repeat awards and early visibility into tenders; NOV acquired Dril-Quip for $1.775 billion in 2021, underscoring that strategic value.
Aftermarket field services, installation support, and life-of-field maintenance generate steady recurring revenue and improve equipment uptime, boosting customer satisfaction and retention. Service teams supply real-time feedback that accelerates product improvements and reduces warranty costs. Higher-margin service contracts help stabilize cash flow between project awards and smooth earnings volatility.
Dril-Quip proprietary connectors and engineered systems deliver measurable performance differentiation for deepwater applications, where a single well can exceed $50 million in capital cost and downtime can surpass $1 million per day. Proven low-failure performance reduces operator risk in these high-cost environments. Lengthy qualification histories (commonly 12–24 months) create strong barriers to entry and encourage long-term standardization on operator specs.
Deepwater engineering since 1981 (44 years in 2025) delivers certified, low-failure systems that shorten operator qualification (12–24 months) and command premium pricing. A broad subsea portfolio and recurring aftermarket services create sticky, higher-margin revenue; NOV acquired Dril-Quip for $1.775B in 2021, reflecting strategic value. Performance reduces operator downtime risk (> $1M/day) on wells costing > $50M each.
| Metric | Value |
|---|---|
| Founded | 1981 |
| Acquisition | $1.775B (2021) |
| Qualification | 12–24 months |
| Downtime risk | > $1M/day |
 Detailed Word Document
Provides a concise SWOT analysis of Dril-Quip, outlining its core strengths and operational weaknesses while identifying market opportunities and external threats that influence its strategic position.

 Customizable Excel Spreadsheet
Provides a concise Dril-Quip SWOT matrix that highlights key strengths, weaknesses, opportunities, and threats to quickly relieve strategic pain points and guide priority actions.
Revenue remains closely tied to operators’ deepwater capex cycles, making Dril‑Quip vulnerable to project deferrals or cancellations that can rapidly erode backlog and order flow. Limited visibility persists despite long sales cycles, amplifying earnings volatility in downcycles. The business has faced this cyclicality since NOV acquired Dril‑Quip for about 1.1 billion USD in 2018, underscoring scale but not insulation from offshore swings.
Large engineered orders drive uneven quarterly results for Dril-Quip, with a few multi-million-dollar projects dominating revenue recognition. Long qualification and procurement cycles delay revenue and extend sales-to-cash timelines. Working capital often spikes during build phases, straining liquidity. This lumpiness complicates forecasting and capacity planning.
Specialized facilities and skilled labor keep Dril-Quip’s fixed-cost base high, making overheads less flexible. Underutilization in downturns compresses margins as capacity sits idle. Scaling down risks losing critical capabilities, and cost absorption pressure rises sharply when award flow slows.
Dril-Quip's heavy concentration in oil and gas limits exposure to faster-growing low-carbon segments; global clean-energy investment reached about $1.7 trillion in 2023 (IEA), drawing capital away from traditional subsea demand. Limited diversification heightens transition risk as customers reprioritize decarbonization and may shift spend from conventional subsea kit. Pivoting will likely require incremental R&D and capex to serve renewables and CCUS markets.
Meeting operator and regulatory standards is resource-intensive for Dril-Quip, driving higher compliance headcount and CAPEX and stretching engineering capacity; 2024 industry focus on safety and traceability further raised audit frequency. Country-specific local content rules increase procurement costs and complicate supply chains, while extensive documentation and testing routinely extend project timelines. Smaller regional competitors can outmaneuver Dril-Quip on localized requirements and speed to qualification.
Revenue tied to deepwater capex cycles; NOV bought Dril‑Quip for about 1.1 billion USD in 2018, showing scale but not insulation. Lumpiness from large engineered orders and long sales/qualification cycles increases earnings volatility. Heavy fixed costs and compliance/local-content burdens raise breakeven and slow responsiveness. Clean‑energy investment reached about 1.7 trillion USD in 2023 (IEA).
| Metric | Value |
|---|---|
| Acquisition | ~1.1 bn USD (2018) |
| Clean-energy invest | ~1.7 tn USD (2023) |
This is the actual Dril-Quip SWOT analysis document you’ll receive upon purchase—no surprises, just professional quality. The preview below is taken directly from the full report and reflects the same structured, editable file you'll download after checkout. Purchase unlocks the complete in-depth version.
Improved breakevens—often cited at roughly 40–50 USD/bbl in 2024—plus steadier operator cash flows are re‑activating deepwater FIDs in Brazil, Guyana and the US Gulf of Mexico. Multi‑year project pipelines lift Dril‑Quip’s addressable backlog and revenue visibility. Standardized subsea and topside designs shorten award cycles and provide operating leverage as facilities fill.
Integrity management, tie-backs and equipment upgrades extend field life and drive recurring work streams; aftermarket and replacement cycles can account for a meaningful share of service firm revenues and provide steady demand. Brownfield interventions often deliver faster paybacks—commonly 1–3 years—helping operators accelerate cash returns and smoothing supplier revenues between megaprojects.
Embedding sensing, monitoring, and analytics into Dril-Quip equipment can materially improve reliability and uptime, while standardized product families cut manufacturing costs and lead times. Digital twins and remote support boost service margins and scalability; the digital twin market is growing at roughly a 35% CAGR (2021–2026), highlighting strong demand. These capabilities reinforce competitive differentiation and recurring-revenue potential.
Alliances with EPCs and operators can secure preferred‑supplier status; 2024 upstream capex rose ~12% YoY (Rystad Energy), increasing demand for frame deals that give volume visibility and lower bid costs, while co‑engineering shortens qualification cycles and enables bundled subsea solutions.
Dril-Quip capabilities in high-spec connectors and pressure systems can translate into CCS, offshore gas and geothermal interfaces, aligning with IEA estimates that CCS must scale toward ~5.6 GtCO2/yr by 2050.
Specialty connectors fit adjacent use cases with modest diversification able to de-risk revenue streams and capture growing tender pools.
Targeted R&D (small pilot budgets) could open new contracts while preserving core margins.
Improved breakevens (40–50 USD/bbl in 2024) and +12% upstream capex (2024) revive deepwater FIDs, boosting backlog visibility. Aftermarket, tie‑backs and standardized designs shorten cycles and steady revenues; digital twins (≈35% CAGR 2021–26) raise service margins. CCS/geothermal adjacencies align with IEA 5.6 GtCO2/yr need, enabling modest diversification.
| Metric | Value |
|---|---|
| Breakeven oil (2024) | 40–50 USD/bbl |
| Upstream capex YoY (2024) | +12% |
| Digital twin CAGR | ≈35% (2021–26) |
| IEA CCS need | 5.6 GtCO2/yr by 2050 |
Commodity price volatility—Brent averaged about $86/bbl in 2024 with intra-year swings of 20–30%, driving operator capex shifts that can freeze deepwater FIDs; subsequent budget resets compressed tender activity and directly threaten Dril-Quip’s order intake and utilization rates.
Rival OEMs and integrated subsea players such as Schlumberger, Aker Solutions and OneSubsea compete aggressively on price and scope, pressuring Dril-Quip’s standalone margins; bundled EPC offerings have driven price concessions on large projects, with reported contract discounting up to double-digit percentages in 2024. Larger peers continue to out-invest in R&D and digital — industry R&D spends in 2024 exceeded $2bn for top-tier service firms — amplifying tech gaps. Price wars on trees and connectors can materially erode profitability on key products.
Material costs and long-lead components remain volatile, with S&P Global and IHS Markit reporting extended delivery times in 2024 that strain procurement for offshore OEMs. Delays can push projects into liquidated-damages exposure and disrupt customer delivery schedules. Persistent inflationary pressure in 2024-25 compresses margins if costs cannot be passed through, while supplier concentration raises the risk of single-point disruption.
Tighter environmental rules are lengthening permitting timelines and can delay offshore project starts by months to years, increasing capex carry for suppliers like Dril-Quip. Stakeholder pressure and capital flows toward low‑carbon strategies — Bloomberg Intelligence projects ESG assets could top 53 trillion dollars by 2025 — risk shrinking addressable demand for traditional well‑construction equipment. Rising compliance costs and the financial plus reputational penalties for non‑compliance heighten operational and legal exposure.
Operations across multiple jurisdictions expose Dril‑Quip to sanctions, trade barriers and currency volatility that can compress margins and delay projects. Local content mandates in oil and gas often force higher local sourcing and capex, reducing procurement flexibility. Political instability and weak contract enforcement can disrupt logistics, staffing and the timely realization of revenues.
Brent volatility (avg $86/bbl in 2024; 20–30% swings) and frozen deepwater FIDs cut tendering, threatening order intake and utilization. Aggressive pricing by Schlumberger/Aker/OneSubsea and reported double‑digit contract discounting in 2024 pressure margins while top peers spent >$2bn on R&D. Supply chain delays, inflation and longer permits (ESG assets ≈ $53T by 2025) raise costs, compliance and demand risks.
| Threat | Key metric | 2024/25 signal |
|---|---|---|
| Commodity volatility | Brent avg | $86/bbl (2024) |
| Competitive pricing | Contract discounts | Double‑digit (2024) |
| R&D gap | Top peer spend | >$2bn (2024) |
| ESG shift | Assets | $53T by 2025 |


