
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
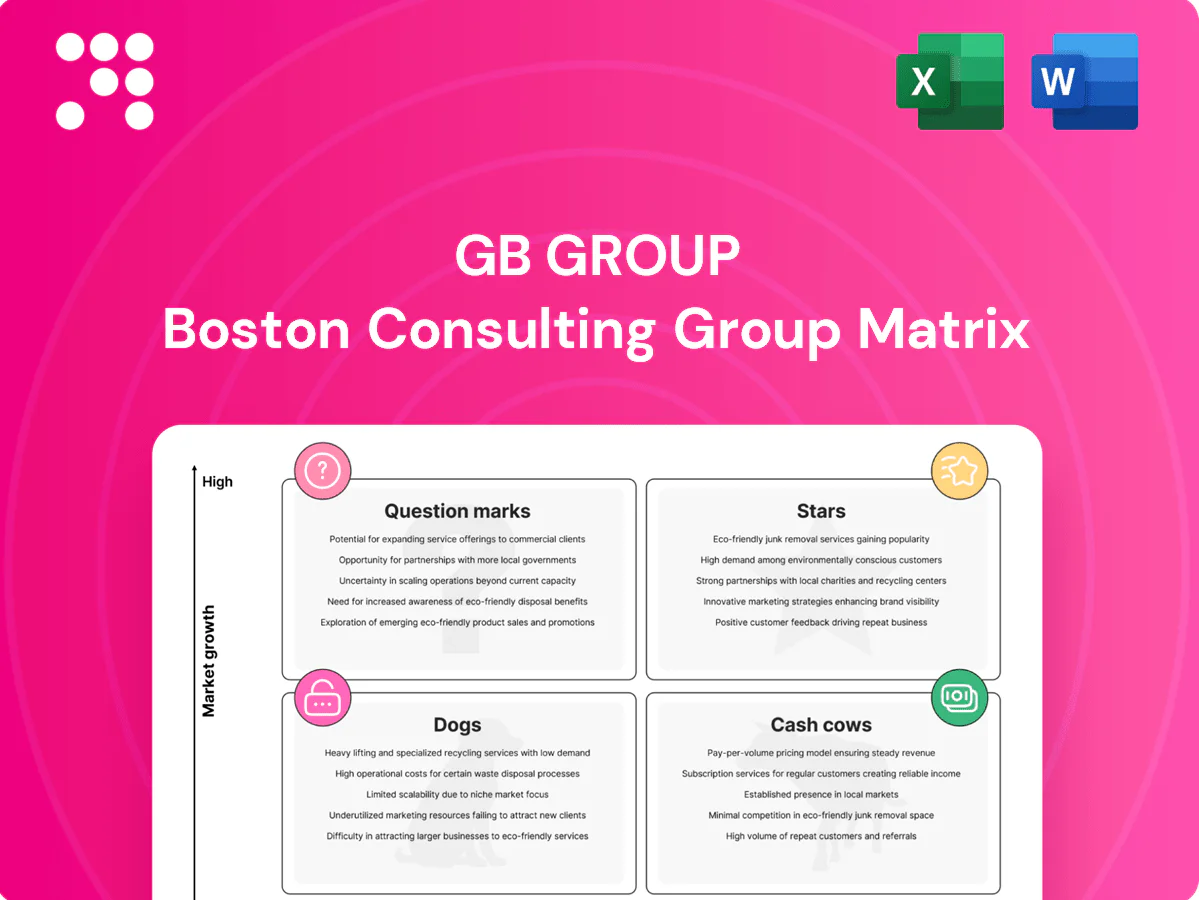
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
The GB Group BCG Matrix snapshots product positions—who’s a Star, who’s bleeding cash, and which offerings are Question Marks waiting to be validated. This short view hints at market share and growth patterns; the full report gives quadrant-by-quadrant data, strategic moves, and ready-to-use Word + Excel files. Buy the complete BCG Matrix for actionable recommendations and a clear investment roadmap you can present tomorrow.
Hardware‑bound legacy on‑prem ID verification is slow to update and costly to support; Flexera 2024 reports ~93% enterprise cloud usage and ~85% cloud‑first strategies, pushing demand to API‑native solutions. Turnarounds and refits often exceed $1M with 20–30% annual support overhead and limited ROI. Prioritize migration to cloud APIs or sunset these dogs.
Standalone postal address file licensing is a Dog: mail volumes have fallen roughly two-thirds in the UK since 2000, compressing demand; pure PAF resell is commoditized with low pricing power and minimal differentiation. It ties up support resources for little return; consider divestment or offering only bundled with higher‑value services.
Custom builds stretch teams and compress margins; bespoke government work often shows low single-digit project profits and high delivery overheads. Procurement cycles commonly run 6–12 months (2024), and scope creep frequently erodes margins and schedules. Cash impact is neutral to negative due to long payment terms; exit or tightly qualify only high-margin bids.
Legacy SMS OTP delivery is a Dogs segment for GB Group: carrier-driven per-message costs rose to roughly $0.01–$0.03 in 2024, squeezing margins into low single digits while enterprise clients shift to app-based and passkey authentication; volatile delivery quality and routing costs further erode profitability and increase fraud exposure given SIM-swap risks documented since NIST deprecation of SMS for MFA.
Regional point solutions with narrow data struggle to scale across countries or sectors, showing sales cycles 30–50% longer and upsell paths thin; support load often exceeds 60% of product revenue, making unit economics negative. For GB Group these Dogs should be consolidated or retired into broader identity platforms to reduce churn and cost-to-serve.
Hardware‑bound ID, standalone PAF, bespoke builds and SMS OTP are Dogs: PAF demand down ~66% since 2000, SMS costs $0.01–$0.03/message (2024), support often >60% of revenue and sales cycles 6–12 months; low pricing power and thin margins—sunset, consolidate or pivot to cloud/API MFA.
| Segment | 2024 metric | Action |
|---|---|---|
| PAF | −66% vol since 2000 | Divest/bundle |
| SMS OTP | $0.01–$0.03/msg | Wind down |
Reusable digital identity/identity wallets are a Question Mark for GB Group: ecosystem still forming with low share today but big upside if regulators and major platforms tip — EU digital identity wallet framework progressed through 2024, accelerating pilots and standards work.
Realization requires heavy investment in standards, privacy engineering, and partnerships across banks, telcos, and platforms to capture network effects and trust.
With successful adoption it could breakout into a Star; failure to scale or fragmenting standards could relegate it to a niche stall.
AI-driven fraud is exploding: FBI IC3 reported $10.3B in fraud losses in 2023 and deepfake-enabled scams surged, driving strong demand but a crowded vendor landscape. GBG’s proprietary trust signals and data assets position it well, yet the tech race (biometric liveness, deepfake detection) is intense and capital-hungry. Early traction metrics—hit rates, false-acceptance/false-reject parity, and seamless UX—must be proven quickly. Recommend either double down with accelerated R&D or acquire specialist IP to compress time-to-market.
Regulation is tightening—MiCA entered application in 2024 and US enforcement ramped up—yet cycles remain choppy; market volatility persists. Global crypto market cap exceeded 1 trillion USD in 2024, signaling high growth potential while GBG’s on‑chain KYC share remains limited. Integration with blockchain analytics (on‑chain data + sanctions screening) is critical. Recommend test‑and‑scale pilots, keeping optionality low‑cost.
Emerging markets identity graph sits as a Question Mark: >$30bn TAM in emerging markets (2024 est.), yet over 1 billion people lack formal ID (World Bank), making data quality the primary hurdle; success requires deep partnerships with telcos, bureaus and governments, is cash hungry pre-scale and demands selective pilots to prove unit economics rapidly.
Account opening fraud for BNPL and micro-lenders is an explosive, price-sensitive category with global BNPL users ~180 million in 2024; GBG's identity credibility helps but agile local players capture market share quickly. Tailored models and packaged workflows are required to reduce false declines and fraud losses. Invest if win-rate improves materially; otherwise bundle into core risk offerings.
Reusable identity, AI-fraud, on‑chain KYC, emerging‑market identity graph and BNPL onboarding are Question Marks for GBG: high upside but require heavy R&D, partnerships and capex. 2024 signals: EU wallet pilots, FBI IC3 $10.3B fraud (2023), crypto >$1T market cap, BNPL ~180M users, >1B without formal ID.
| Segment | 2024/2023 metric | Key need |
|---|---|---|
| Digital wallet | EU pilots 2024 | Standards & partners |
| AI fraud | $10.3B (IC3 2023) | Advanced detection |
| On‑chain KYC | Crypto >$1T (2024) | Analytics integration |
| EM ID graph | TAM>$30B; >1B unID | Telco/govt deals |
| BNPL onboarding | 180M users (2024) | Tailored models |


