
Digital download
Access the files immediately after checkout.
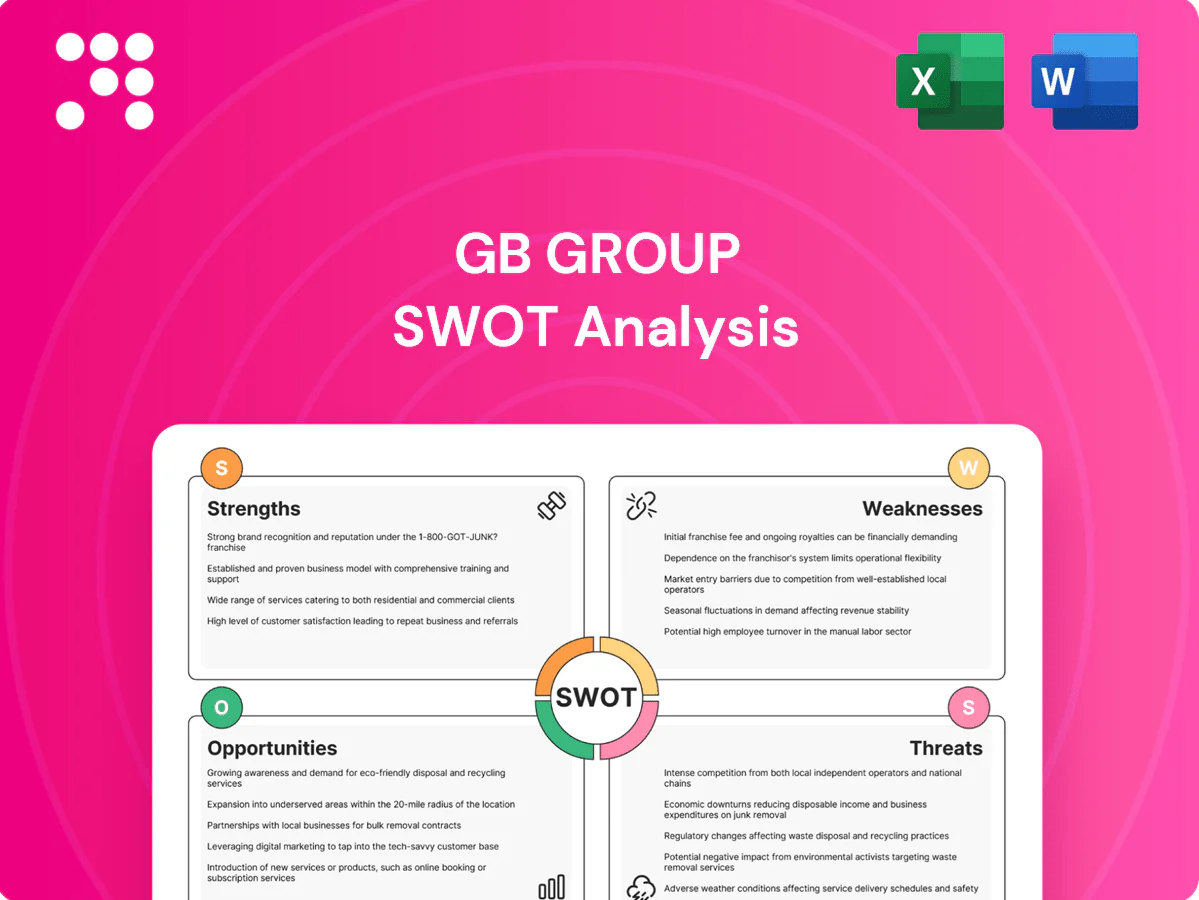
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
GB Group’s strengths lie in market-leading digital identity and fraud-prevention solutions, strong client relationships, and scalable data capabilities, while dependencies on UK/European markets and integration complexity pose weaknesses; growth opportunities include global digital ID adoption, with competition and regulatory change as key threats. Purchase the full SWOT analysis to get a research-backed, editable Word and Excel package for strategy, investment, or due diligence.
GB Group offers an integrated platform across identity verification, fraud prevention and location intelligence, cutting vendor sprawl for over 11,000 customers and processing >1bn transactions annually (2024). The breadth supports end-to-end onboarding, continuous monitoring and transaction decisioning. Unified workflows boost accuracy and speed, raising switching costs and driving higher wallet share.
GB Group's solutions cover KYC, AML, age verification and sanctions screening across 70+ countries, offering auditable workflows that help clients meet evolving regulatory obligations; the platform handles over 1 billion verification checks annually, supporting faster deployments and lower compliance risk. Domain expertise shortens time-to-live and deepens ties with banks, fintechs and regulated enterprises, boosting retention and cross-sell.
Serving five core verticals — financial services, e-commerce, gaming, telecoms and government — spreads revenue risk and reduces dependency on any single end-market. Global coverage supports multinational onboarding and cross-border payments, reinforcing resilience across jurisdictions. This footprint amplifies data network effects, boosting verification accuracy and scalability as transaction volumes grow.
GB Group's rich data access — integrating multiple global signals and serving over 17,000 customers — drives high match rates and strong fraud detection accuracy, while orchestration layers enable dynamic decisioning and step-up verification that reduce friction and maintain risk control, differentiating GBG from point solutions.
GBG is a recognized identity data intelligence provider with long-standing partnerships and LSE listing credibility; its integrations with major platforms and data vendors shorten deployment cycles and accelerate time to value. Brand trust is critical in identity and fraud markets, supporting premium pricing and repeat enterprise wins.
GB Group provides an integrated identity platform processing >1bn transactions annually (2024) for over 11,000 customers, enabling end-to-end onboarding, continuous monitoring and transaction decisioning. Breadth across 70+ countries and five verticals reduces revenue concentration and amplifies data network effects, improving match rates and retention. Listed on LSE with deep partner integrations supports premium positioning.
| Metric | Value (2024) |
|---|---|
| Transactions processed | >1 billion |
| Customers | >11,000 |
| Coverage | 70+ countries |
 Detailed Word Document
Delivers a strategic overview of GB Group’s internal and external business factors, outlining strengths, weaknesses, opportunities, and threats to assess its competitive position, growth drivers, operational gaps, and market risks shaping future performance.

 Customizable Excel Spreadsheet
Delivers a focused SWOT matrix highlighting GB Group's strengths, weaknesses, opportunities and threats to quickly identify and address strategic pain points; editable, visual format enables fast stakeholder alignment and rapid decision-making.
Rising fintech, e-commerce and instant payments—global e-commerce exceeded $6 trillion in 2024—boost identity and fraud prevention demand; more transactions require real-time verification and continuous monitoring. Embedded finance expands identity needs across retail, marketplaces and platforms, widening the addressable market. GBG can capture higher volumes and upsell advanced analytics, device and behavioural risk solutions to banks and merchants.
Applying machine learning to device, behavioral and network signals can materially lift detection rates, and demand for generative AI countermeasures against deepfakes and synthetic IDs is rising alongside broader AI adoption. McKinsey estimates AI could add up to 13 trillion USD to the global economy by 2030, boosting budgets for fraud prevention. Model orchestration and explainability are critical to win regulated clients, enabling premium pricing and client stickiness.
Rising digitization and tighter KYC in APAC, LatAm and Africa expand TAM amid 1.4 billion unbanked adults (World Bank Findex 2021) and a digital identity market ~25 billion USD in 2023 (MarketsandMarkets). Local data partnerships improve coverage and accuracy where bureau penetration is low. Tailored products for thin-file populations unlock revenue from underserved segments, while channel alliances speed market entry.
eIDAS 2.0 (adopted June 2023) and national ID wallets across the EU (447 million citizens) are scaling public-sector digital ID programs; by mid-2025 over 20 member states were piloting wallets, creating large integration demand. Vendors ensuring compliance and interoperability will capture substantial market share, and GBG can monetize via trust services and verification rails.
Location intelligence boosts address validation, geofencing and fraud scoring, improving match rates and detecting anomalous patterns when combined with device and IP signals. Bundling location with IDV raises hit rates and reduces customer friction, enabling smoother KYC and faster onboarding. It unlocks logistics, mobility and retail media use cases while increasing ARPU and retention for GBG.
Growing global e-commerce ($6T in 2024) and embedded finance expand IDV demand; GBG can upsell analytics, device and behavioral risk to banks and merchants. AI-driven detection and generative-AI countermeasures (McKinsey: up to $13T by 2030) raise budgets for fraud prevention and model explainability. Digital ID market (~$25B in 2023) and EU eIDAS rollouts (447M citizens; 20+ states piloting wallets by mid-2025) create integration opportunities.
| Metric | Value |
|---|---|
| Global e‑commerce 2024 | $6T |
| AI economic impact | $13T by 2030 |
| Digital ID market 2023 | $25B |
| EU population / wallets | 447M / 20+ states |
Evolving privacy and data regulations—notably GDPR with fines up to 4% of global turnover or €20m—plus UK data reform and expanding US state privacy regimes restrict GB Group’s data use. Rising compliance costs and reduced data availability can squeeze margins and product capabilities. Severe penalties for breaches heighten legal risk. Fragmented rules across jurisdictions complicate scaling and increase operational overhead.
Large incumbents such as Experian and Equifax and IDV specialists (Onfido, Veriff) compete fiercely on coverage, accuracy and price, while platform players like Stripe and AWS increasingly bundle identity into broader suites. In 2024 the identity-verification market continued double-digit growth, accelerating vendor entry and API-led customer switching. Frequent API swaps keep churn high and sustain margin-erosion risk for GB Group.
Handling sensitive identity data makes GBG a prime target for cyberattacks; the average global cost of a data breach was $4.45m in IBM's 2024 report. Any incident could trigger GDPR fines up to €20m or 4% of global turnover and prompt client losses. Reputation damage in identity services erodes trust rapidly. Increased cyber insurance and layered controls drive sustained operational costs.
Advancing fraud techniques—synthetic identities, deepfakes and bot farms—are evolving rapidly as adversaries leverage AI and inexpensive cloud compute to bypass controls; the FBI IC3 reported $10.3B in reported fraud losses in 2022, underscoring scale. Detection models require continuous retraining and monitoring; lagging updates risk higher false negatives or increased customer friction.
Macroeconomic slowdown and FX volatility can force budget cuts and lower transaction volumes, delaying projects and shrinking platform usage; IMF projected global growth at 3.0% in 2024 (WEO Apr 2024), underscoring weaker demand. Startups and cross-border merchants may consolidate spend, reducing new-client acquisition and transaction frequency. Currency swings materially impact reported results for global businesses, making planning and pricing more challenging.
Regulatory limits (GDPR fines up to 4% of turnover or €20m) and rising compliance costs constrain data use and margins. Fierce competition and API-led vendor switching pressure pricing and churn amid double-digit market growth. Escalating cyberattacks and AI-driven fraud (IBM 2024 breach cost $4.45m; FBI IC3 $10.3B in 2022) raise loss and remediation expenses.
| Metric | Value |
|---|---|
| GDPR max fine | 4% turnover / €20m |
| Avg breach cost (2024) | $4.45m |
| FBI IC3 fraud (2022) | $10.3B |
| IMF global growth (2024) | 3.0% |


