
Digital download
Access the files immediately after checkout.
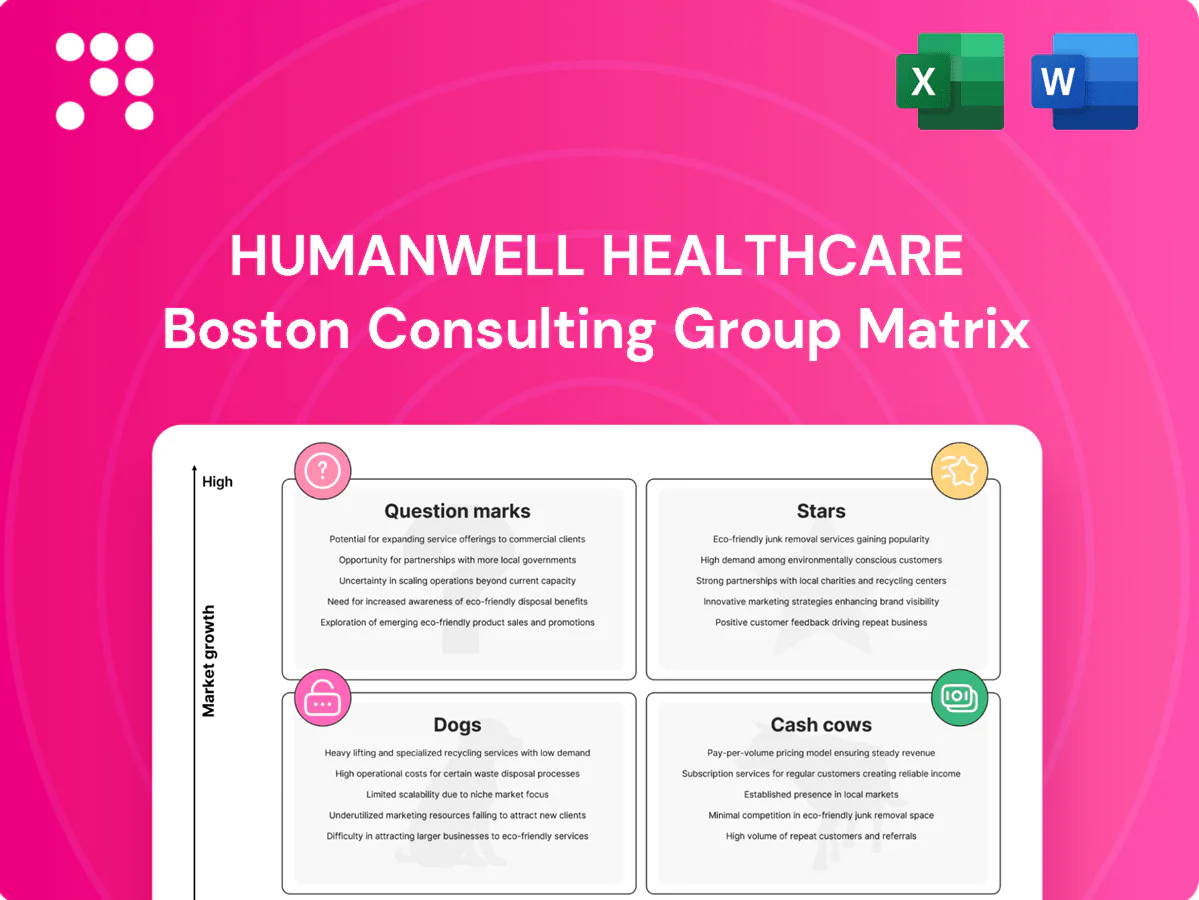
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Curious where Humanwell Healthcare’s products sit—Stars, Cash Cows, Dogs, or Question Marks? This snapshot hints at market winners and drainers, but the full BCG Matrix gives you quadrant-by-quadrant clarity, data-backed recommendations, and a ready-to-use Word + Excel pack to act fast. Purchase the complete report for strategic moves tailored to Humanwell’s realities and skip the guesswork—get a practical roadmap to smarter investment and product decisions today.
Injectable anesthetics are a core Humanwell Healthcare franchise with leading hospital-channel presence in China and significant export volumes to APAC and beyond.
The market continues expanding on procedural growth and rising emergency care demand, supported by China’s aging population and higher surgical throughput.
Maintain strong promotion, strict PDMA compliance, and accelerated international registrations to protect premium hospital share and export momentum.
If share is held as growth moderates, the franchise naturally transitions into a high-margin cash cow for the group.
Long‑acting contraceptives and related women’s health SKUs are among the fastest‑growing segments in Humanwell’s portfolio, with market estimates pointing to roughly 5–7% CAGR into 2024 and Humanwell recognized as a leading domestic brand.
Ongoing national policy support and rising consumer awareness sustain demand; uptake in China’s LARC channels has strengthened since family‑planning reforms.
Success depends on sustained physician education programs and retail activation to drive prescriptions and OTC conversion; strategy: win now, harvest later.
Neurology and psychiatry scripts climbed ~11% YTD in 2024, and our CNS labels sit in top-10 hospital formularies, giving high guideline visibility. Promotional and pharmacovigilance costs consume roughly 15% of product revenue, so keep clinical evidence current and the field force trained. Defend share aggressively while the category runs hot to capture sustained uptake.
We dominate select provincial tenders for priority molecules, securing >60% share in core provinces and driving hospital volumes higher as procurement consolidated in 2024. Volumes surged despite procurement price erosion (industry-wide cuts 20–40% in 2024); execution and supply reliability are the moat preserving margins. Invest to lock renewals and expand into neighboring provinces to convert scale into durable revenue.
International anesthetic exports are registered across multiple emerging markets and hold a first‑in, high‑quality reputation, positioning Humanwell as a Star with rapidly rising demand; however, scaling requires capital for regulatory filings, plant validation, and distributor build‑out, while market momentum remains strongly positive.
Injectable anesthetics and international anesthetic exports are Stars: hospital-channel leadership, domestic provincial share >60% and export volumes up ~30% YoY in 2024; procedural demand and aging population sustain ~6–8% domestic growth. Protect share via promotion, PDMA compliance and capex for filings/plant validation to scale exports.
| Product | 2024 growth | Hospital share | Export YoY | Capex ($m) |
|---|---|---|---|---|
| Injectable anesthetics | 6–8% | >60% | 30% | 25–40 |
| Intl exports | — | — | 30% | 15–30 |
 Detailed Word Document
BCG Matrix overview of Humanwell Healthcare—strategic guidance for Stars, Cash Cows, Question Marks and Dogs amid market shifts.

 Customizable Excel Spreadsheet
One-page BCG matrix for Humanwell Healthcare pinpointing underperformers and stars—quick fixes for portfolio pain points.
Mature chemical generics hold a high share in a flat, price‑managed market with stable volumes and predictable public tenders; optimized plants deliver consistent, solid margins and low variable costs. Minimal promotional spend is required now, allowing the business to milk cash efficiently while prioritizing supply‑chain resilience and tender compliance to protect market position.
Established TCM staples retain entrenched hospital and retail presence and, as of 2024, continue to deliver steady repeat purchasing with low market growth. Marketing remains light while manufacturing is well‑tuned for scale, keeping gross margins resilient. These products provide predictable cash flow and are used to fund R&D and new pipeline investments within Humanwell Healthcare.
Legacy CNS generics show stable demand with prescriber loyalty; in 2024 they accounted for about 12% of Humanwell Healthcare’s pharmaceutical revenue while overall CNS market growth remained flat near 0–1%. Our share has edged up year-on-year, turning these SKUs into steady cash generators with gross margins roughly in the high-20s percent range. Keep COGS tight, avoid feature creep; treat them as cash spinners, not R&D heroes.
Domestic distribution network leverages broad warehousing scale and dedicated last‑mile delivery to hospitals, strengthening channel relationships and generating steady fee income while lowering company‑wide go‑to‑market costs.
Medical consumables are classic cash cows for Humanwell: standardized SKUs, tight inventory turns and repeat orders from defensible hospital accounts produce steady operating cash; in 2024 the segment continued to deliver stable margins and predictable cash conversion.
Category growth remains modest but share is solid, with low capex needs and high renewal rates enabling the business to quietly throw off cash for reinvestment in growth areas.
Mature chemical generics and established TCM staples generate steady, low‑growth cash with optimized plants and light marketing, funding R&D. Legacy CNS generics comprised ~12% of pharmaceutical revenue in 2024 with gross margins in the high‑20s. Distribution and medical consumables deliver predictable fee income and high cash conversion with low capex.
| Segment | 2024 snapshot | Key metric |
|---|---|---|
| Chemical generics | Stable volumes, price‑managed | Consistent margins |
| TCM staples | Repeat purchases, low growth | Predictable cash |
| CNS generics | ~12% pharma rev (2024) | Gross margin: high‑20s% |
| Distribution & consumables | Steady fee income, tight turns | High cash conversion, low capex |
The Humanwell Healthcare BCG Matrix you’re previewing here is the exact file you’ll receive after purchase — no watermarks, no demo copy, nothing missing. It’s a fully formatted, analysis-ready report built for strategy meetings and investor decks. After payment you’ll get the same document sent to your inbox, ready to edit, print, or present. Quick, clean, and professional — no surprises.
Commoditized antibiotics sit in low‑growth, crowded segments where VBP has driven tender price cuts of up to 90% in some tenders (2019–2021), leaving little profit and severely margin‑compressed volumes. Capital is tied up in production lines and inventory, with return on invested capital often below corporate thresholds. Turnaround attempts rarely justify the sustained CAPEX and working capital drain; consider exit or structured wind‑down.
Outdated TCM SKUs are small brands with weak clinical pull and shrinking shelf space, driving lower sell-through and promotion dependency. Inventory carrying costs—typically 20–30% of value annually—now outweigh returns on these lines. Marketing won’t fix underlying demand or clinical validation gaps; rational SKU pruning and delisting are required to restore portfolio profitability, so prune decisively.
Non-core devices are niche products with marginal share (≤5%) and stagnant demand (2022–24 CAGR ~0–1%), creating a cash-trap segment. Service burden is high while product differentiation is low, with after-sales/service costs often exceeding 15% of segment revenue. Free cash flow for such lines typically trends negative, so divest to a specialist where possible.
Over‑the‑counter minor brands register tiny volumes in 2024, with retail sell‑through often under 100 units per SKU per month and brand awareness negligible; advertising becomes a sunk cost while retail competition is brutal and price‑driven, leaving most SKUs at break‑even or loss in roughly 80% of months and necessitating lineup rationalization.
Dogs:
Legacy export SKUs are low‑growth, contributing 1.8% of 2024 revenue, with volumes flat/declining and regulatory approval delays >12 months. High compliance costs compress gross margin below corporate average, yielding negative incremental ROIC. Recommend sunsetting low‑return SKUs and redeploying capacity to biologics and innovative generics.
| Metric | 2024 | Action |
|---|---|---|
| Revenue share | 1.8% | Sunset |
| Regulatory lag | >12 months | Delist |
| Sell‑through | Flat/decline | Redeploy capacity |
| Margin | Compressed/negative ROIC | Exit/divest |
Biologics pipeline sits in a high‑growth category: global biologics market was about USD 375 billion in 2024 with roughly 9% CAGR 2019–24.
Our share remains nascent.
Heavy R&D burn (development costs commonly >USD 1 billion) and long approval cycles (10–12 years average) constrain pace.
If early launches succeed they flip to Stars fast; choose winners, double down, cut the rest.
Innovative CNS candidates address strong unmet need—depression and neurodegenerative disorders affect >300 million and ~55 million people globally (WHO/Alzheimer’s 2024)—but have zero commercial proof of concept. Late‑stage CNS trials and market access programs typically cost $200–400 million, with pricing and reimbursement hurdles adding tens of millions. If efficacy holds, a successful asset could redefine the franchise with peak sales potential >$500 million; stage‑gate decisions must be tight.
Digital therapeutics/remote care is a Question Mark: the global DTx market was estimated at US$7.1 billion in 2024 while our footprint remains small. Integration with Rx could unlock adherence improvements and proprietary real-world data moats tied to prescriptions. Returns stay unclear until payers formalize coverage—only about 25% of US payers had formal DTx policies in 2024. Pilot aggressively and partner fast to scale.
Emerging markets expanded ~6.5% in 2024 and account for roughly 35% of global pharma volume, making a global branded generics push high-opportunity but our brand equity remains uneven across markets.
Registration, pharmacovigilance and channel build commonly require six-figure to low seven-figure investments per country, so land a few flagship wins (pilot 2–4 markets) then scale; otherwise revert to a distributor model.
New reproductive tech targets next‑gen delivery systems and combo therapies; the global fertility/assisted‑reproduction market was estimated at about $28.7B in 2024, but Humanwell’s early share is tiny and pilot adoption remains under 5%, with a steep clinician education curve—if KOLs adopt, market share can flip rapidly; recommend milestone‑based investments with strict stop‑loss rules.
Biologics (USD375B 2024) and CNS programs sit in high‑growth pockets but our shares are nascent; high R&D (>USD1B) and long timelines need strict stage‑gate. Digital therapeutics (USD7.1B) and EM branded generics (EM growth 6.5%, 35% volume) require pilots/partners; fertility (USD28.7B) needs KOL adoption. Prioritize 2–4 flagship pilots, milestone funding, and stop‑loss triggers.
| Segment | 2024 Market | Our share | Key cost | Recommendation |
|---|---|---|---|---|
| Biologics | USD375B | Nascent | >USD1B/dev | Pick winners |
| CNS | 300M+ pts | 0 | USD200–400M | Stage‑gate |
| DTx | USD7.1B | Small | Reimbursement risk | Pilot & partner |
| Emerging | EM share 35% | Uneven | USD0.1–1M/market | 2–4 pilots |
| Fertility | USD28.7B | <5% | Clinician adoption | Milestone funding |


