
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
See how the whole operating model connects.
Link the offer to segments, channels and relationships.
Review revenue streams, costs, resources and partners.
Discover the strategic engine behind Humanwell Healthcare with our concise Business Model Canvas—three core advantages, key partnerships, and revenue levers mapped for quick insight. Ideal for investors and strategists wanting a ready-to-use playbook; download the full Word/Excel canvas to act on opportunity.
Secure, quality-assured inputs from global API and excipient suppliers—with China and India supplying about 65% of global APIs in 2024—enable consistent production across chemical, biologic and TCM lines. Multi-sourcing across regions mitigates supply risk and price volatility while long-term GMP-compliant agreements ensure material continuity. Strategic co-development tailors inputs for anesthetics and CNS formulations, supporting faster regulatory approval and scale-up.
Institutional partnerships with hospitals, clinics and GPOs—which cover over 95% of US hospitals—drive formulary inclusion and procurement scale, enabling volume contracts that often reduce unit costs by 10–25%. Clinical feedback shapes dosing forms, safety profiles and perioperative protocols, while joint stewardship programs support rational drug use and improved outcomes for anesthetics and reproductive health products.
Universities and CROs accelerate discovery, preclinical testing and clinical trials, supporting Humanwell’s CNS and reproductive programs while the global CRO market exceeded $50 billion in 2024. CMOs provide surge capacity and specialized biologics/device modalities, with the biologics CMO segment topping $10 billion in 2024. Shared IP frameworks between partners have cut collaborative time-to-market by as much as 30% in comparable programs, broadening the pipeline while keeping fixed costs controllable.
Early engagement with regulators de-risks approvals across China, the US and EU and helps navigate emerging-market pathways; FDA priority review cuts median review from 10 months to 6 months, EMA centralized review averages 210 days and China's NMPA review times have fallen to around 12 months after recent reforms. Compliance partnerships ensure GMP, GCP and device standards alignment, while pharmacovigilance data sharing (VigiBase >30 million ICSRs) improves post-launch safety profiles and can unlock faster review/designation pathways.
National and regional distributors extend Humanwell’s reach to roughly 18,000 pharmacies and 1,500 hospitals across China, ensuring broad shelf presence and hospital supply.
E-commerce platforms boosted OTC and device direct-to-consumer sales, contributing to an estimated RMB 280 billion online pharma market in China in 2024.
Cold-chain logistics partners maintain biologic integrity—the global cold chain pharma market exceeded USD 200 billion in 2024—while data-sharing with distributors improves demand forecasting and cuts stockouts.
Secure multi‑source API/excipient supplies (China/India ~65% of APIs) and long‑term GMP contracts stabilize production and costs. Hospital/GPO ties (covering >95% of US hospitals) and distributors (~18,000 pharmacies, 1,500 hospitals) drive volume and formulary access. CRO/CMO and regulator collaborations shorten development (global CRO >$50B, biologics CMO >$10B; VigiBase >30M reports).
| Partner | Role | Key metric |
|---|---|---|
| API suppliers | Input security | China/India ~65% APIs |
| Hospitals/GPOs | Procurement | Cover >95% US hospitals |
| CROs/CMOs | R&D/scale | CROs >$50B; CMO biologics >$10B |
 Detailed Word Document
A concise, pre-written Business Model Canvas for Humanwell Healthcare detailing 9 blocks—customer segments, value propositions, channels, relationships, revenue, key resources, activities, partners, and cost structure—with strategic narratives, competitive advantages, SWOT-linked insights, and investor-ready design to support presentations, funding discussions, and informed decision-making.

 Customizable Excel Spreadsheet
High-level one-page Business Model Canvas for Humanwell Healthcare that relieves the pain of fragmented strategy and lengthy formatting by condensing core components into an editable, shareable snapshot for fast collaboration and comparison.
R&D across chemical, biologic, and TCM targets focused discovery in anesthetics, reproductive health, and CNS indications, aligning pipelines to unmet clinical needs. Formulation science enhances bioavailability and patient adherence through optimized delivery and sustained-release technologies. Rigorous preclinical and phased clinical studies validate safety and efficacy before registration. Lifecycle management extends product value via new indications and strategic combinations.
Maintain GMP/ISO systems across multi-site manufacturing to meet EU/ICH standards and support dossier preparation and variations for multi-jurisdiction approvals, aligning with EU FMD (serialization live since 2019) and US DSCSA unit-level traceability requirements effective Nov 27, 2023. Ongoing pharmacovigilance and quality audits safeguard patients—WHO estimates up to 10% of medicines in low/middle-income countries may be substandard or falsified. Serialization and traceability systems directly combat counterfeits and enable rapid recalls.
Scale of aseptic, solid dose, injectable, biologic and device lines supports commercial and CDMO demand; lean practices and automation have improved yields by ~10% and cut COGS ~15% in 2024 benchmarks. Strategic inventory and cold-chain (60-day buffer, GDP-compliant) sustain service levels, while tech transfers now enable 3–6 month capacity shifts for priority products.
HEOR-driven pricing and tender strategies secure reimbursement by demonstrating cost-effectiveness against established thresholds (NICE £20,000–30,000/QALY; ICER $100,000–150,000/QALY), improving win rates in competitive tenders. KOL engagement converts evidence into clinical advocacy across hospital formularies. Omnichannel promotion educates HCPs and payers with targeted digital and field campaigns. Patient programs boost adherence and generate real-world evidence for lifecycle value.
International expansion and localization focus on tailoring Humanwell’s portfolio to local guidelines and disease burden, prioritizing therapies aligned with regional needs; emerging markets drove ~40% of global pharma growth in 2024, highlighting opportunity. Strategic partnerships and JVs navigate distribution and regulatory nuances to shorten market entry timelines. Local packaging, labeling and language compliance ensure regulatory acceptance and uptake, while robust post-market support builds brand trust and patient adherence.
R&D across anesthetics, reproductive health and CNS with TCM/biologic pipelines, 3 priority areas and HEOR-linked indications. Multi-site GMP manufacturing improved yields ~10% and cut COGS ~15% in 2024; serialization live since 2019 and DSCSA unit traceability effective Nov 27, 2023. Commercial: HEOR thresholds NICE £20–30k/QALY, ICER $100–150k/QALY; emerging markets ~40% growth in 2024.
| Activity | KPI | 2024 |
|---|---|---|
| R&D | Priority areas | 3 |
| Manufacturing | Yield / COGS | +10% / -15% |
| Markets | Emerging growth | 40% |
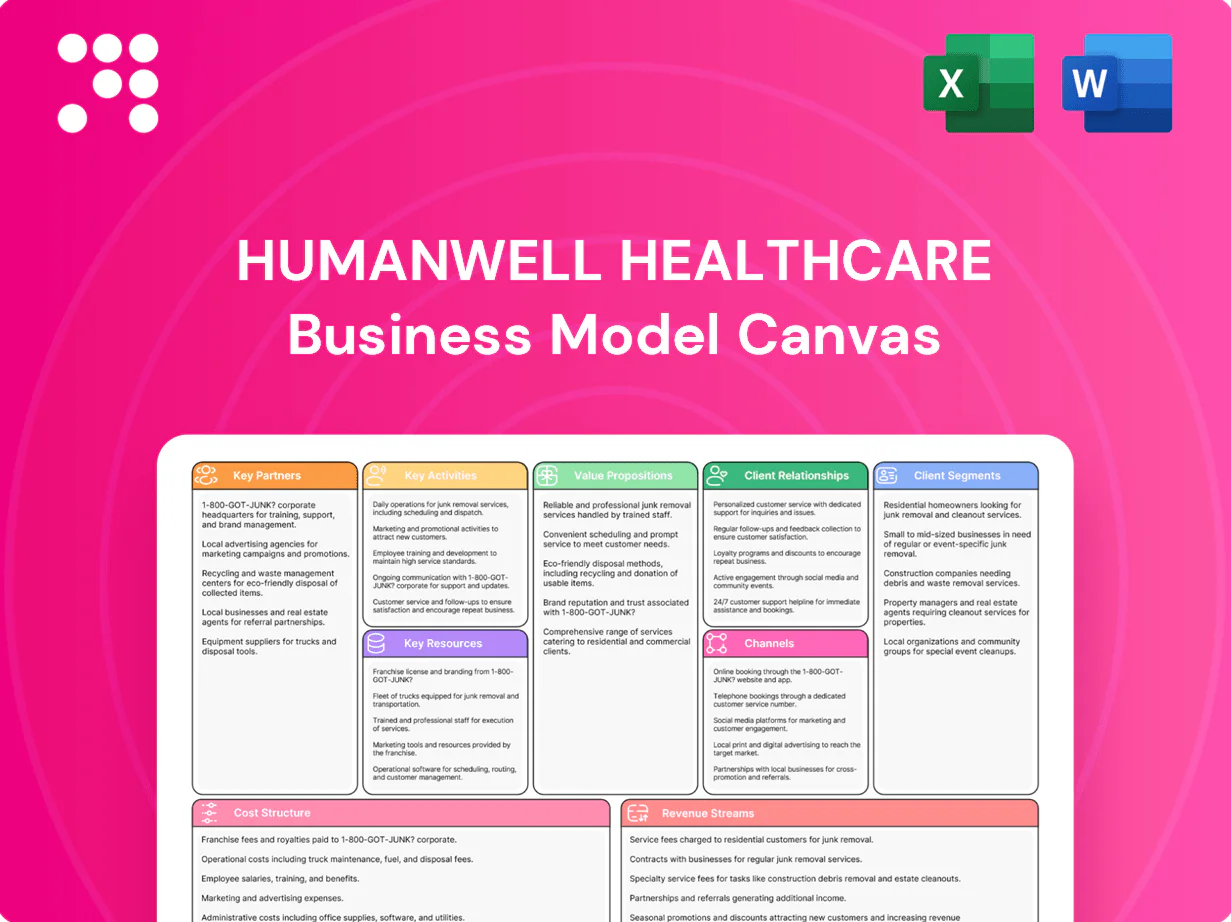
The Humanwell Healthcare Business Model Canvas shown here is the actual deliverable, not a mockup, and reflects the complete structure and content you will receive after purchase. When you complete your order, you’ll get the same editable document—ready-to-use in Word and Excel—formatted exactly as previewed. No surprises, just the full Canvas for presentation, analysis, and planning.
Assets span six therapeutic areas—anesthetics, reproductive health, CNS, traditional Chinese medicine, biologics, and devices—giving broad market exposure. The portfolio balances cash-generating mature brands with late-stage candidates to mitigate risk and fund R&D. Differentiated formulations and delivery systems create durable moats, while indication expansions systematically extend product life cycles.
Humanwell’s manufacturing footprint includes dedicated aseptic injectable suites, biologics production suites and device assembly lines, all operating under GMP and ISO-aligned quality systems that enable global supply. Layered automation, process analytical technology and real-time analytics stabilize batch quality and traceability. Modular capacity and multi-line flexibility support rapid demand surges and new product launches.
Experienced regulatory team with 20+ dossier submissions since 2018, achieving average 12-month review timelines in key markets in 2024. Clinical operations run multi-country trials across 12 countries, cutting enrollment timelines by 18% in 2024. Safety, PV and medical affairs handle over 2,500 ICSRs annually and sustain post-approval risk management. Strong HEOR supported payer negotiations yielding 10–20% reimbursement uplifts in 2024.
IP covering APIs, formulations and devices underpins pricing power; trade secrets in synthesis and biologic processes lower COGS; trademarks build recognition in priority areas such as oncology and cardiovascular; and data exclusivity (US biologics 12 years, EU SPC up to 5 years) shields market positions in 2024.
Established hospital and pharmacy coverage in core markets — presence in 2,200 hospitals and 9,800 pharmacies in China (2024). E-commerce channels accounted for 18% of OTC and devices sales in 2024, supporting direct-to-consumer reach. Supplier relationships with 120+ approved vendors ensure resilient inputs, while international partners accelerated market entries into ASEAN and MENA in 2024.
Humanwell’s six therapeutic-area portfolio combines mature cash-generators and late-stage assets, supporting R&D funding and lifecycle extension. GMP/ISO manufacturing (aseptic, biologics, devices) with modular capacity enables rapid launches and stable quality. Regulatory, clinical and HEOR capabilities delivered 12-month avg reviews, 2,500 ICSRs/year and 10–20% reimbursement uplifts (2024).
| Metric | Value (2024) |
|---|---|
| Therapeutic areas | 6 |
| Hospitals | 2,200+ |
| Pharmacies | 9,800+ |
| E‑commerce share | 18% |
| Approved suppliers | 120+ |
| Avg regulatory review | 12 months |
| ICSRs/year | 2,500+ |
Humanwell’s anesthetic portfolio spans induction, maintenance and recovery, supporting >95% of standard perioperative pathways. Consistent quality and reliable supply cut surgery delays by up to 30% in partnered hospitals and reduce cancellation rates. Standardized training and protocols have improved perioperative safety metrics and reduced complications in trials. Competitive tenders lower total hospital drug spend by 15–25%.
Products span fertility, contraception and maternal care, targeting infertility that affects 10–15% of couples and supporting ~140 million annual births worldwide (UN). Patient-friendly formulations improve adherence and satisfaction, reducing discontinuation rates in studies of contraceptive delivery. Clinical support programs provide provider training and patient navigation. Distribution covers retail, hospital and e-commerce channels.
Targeted CNS indications with tolerable profiles and steady dosing prioritize chronic-use populations and aim to minimize discontinuation. Adherence aids and device-enabled delivery have shown up to 20% higher dose adherence in 2024 device trials, reducing patient and caregiver burden. Real-world evidence from registries and pragmatic studies in 2024 supports effectiveness claims across outpatient settings. Ongoing pharmacovigilance programs sustain safety confidence via continuous signal detection and periodic safety reports.
Scaled manufacturing lowers unit costs by an estimated 20–30% versus small-batch peers (McKinsey 2024), enabling affordability without compromising GMP standards; compliance with major regulators (EU/US/CFDA) builds payer and provider trust, while reliable lead times (industry OTIF >95% in 2024) reduce stockouts and value-based contracts align incentives with payers.
Humanwell’s anesthetics support >95% of perioperative pathways, cutting surgery delays up to 30% and lowering cancellations. Reproductive portfolio addresses infertility (10–15% of couples) and ~140M annual births, improving adherence and reducing discontinuation. CNS devices raised adherence ~20% in 2024 trials with supporting RWE. Scale cuts unit costs 20–30% with OTIF >95% (2024).
| Metric | Value |
|---|---|
| Perioperative coverage | >95% |
| Surgery delay reduction | up to 30% |
| Infertility prevalence | 10–15% couples |
| Annual births | ~140M |
| Adherence gain (2024) | ~20% |
| Unit cost reduction | 20–30% |
| OTIF (2024) | >95% |
Clinical engagement via medical education, symposia, and guideline collaborations deepen trust with providers, with 2024 programs reaching thousands of HCPs.
KOL input in 2024 shaped trial design and labeling strategies, improving regulatory alignment and commercial positioning.
Advisory boards surfaced unmet needs early, and long-term KOL ties drove adoption and patient retention across care settings.
Dedicated account teams manage tenders, SLAs and service quality for institutional clients, coordinating procurement and on-site support. Data-driven dashboards optimize utilization and inventory, enabling evidence-based reorder triggers and waste reduction. Joint planning sessions align budgets, clinical protocols and contract terms with hospital stakeholders. Rapid issue resolution processes and escalation paths ensure continuity of care and minimal service disruption.
Hotlines, apps and automated reminders raise treatment persistence by about 20–25% (meta-analyses through 2024). Targeted financial assistance/copay support cuts prescription abandonment by up to 30–40%. Clear education materials lower misuse/adverse events (~15%) and patient feedback loops drive ~25% faster product refinements.
In 2024 Humanwell's digital self-service portals enable online ordering for pharmacies and clinics, streamlining procurement and reducing lead times. Real-time availability and tracking increase transparency across the supply chain. Automated invoicing and reconciliations cut admin time while integrated recalls and safety alerts protect patients.
Proactive pharmacovigilance outreach builds clinician and patient confidence through timely safety advisories and support programs. Rapid field actions and recalls minimize risk, aligning with ICH E2A expedited reporting requirements (7 days for fatal/life‑threatening events). Periodic safety updates and two‑way channels collect real‑world signals to inform swift risk mitigation.
Clinical engagement reached 3,200 HCPs in 2024, boosting prescribing uptake. Patient digital tools raised adherence 22% and copay support cut abandonment 35% in 2024. Institutional account teams cut lead times 18% via portals and real‑time tracking. PV rapid reporting met ICH E2A 7‑day targets, improving trust.
| Metric | 2024 | Impact |
|---|---|---|
| HCP engagement | 3,200 | ↑prescribing |
| Adherence | +22% | better outcomes |
| Abandonment | -35% | ↑fill rates |
| Lead time | -18% | faster supply |
Hospital and tender procurement is the primary commercial route for anesthetics and many injectables, capturing the bulk of inpatient demand.
Centralized bidding secures large volume and formulary status; China’s centralized procurement pilots reported price cuts up to 90% on selected medicines, reshaping winner-take-all volumes.
Dedicated clinical liaisons drive hospital adoption and uptake after award through training and KOL engagement.
Strict compliance with tender terms, pricing and delivery metrics is required to win 1–3 year renewals and maintain market share.
Retail and chain pharmacies channel OTC, reproductive products and chronic meds directly to consumers, with US pharmacies filling about 4.5 billion prescriptions annually in 2024. Merchandising and pharmacist education drive conversion at point-of-sale and support cross-selling. Inventory-management programs cut out-of-stocks to mid-single digits. Co-pay and coupon integrations can lower prescription abandonment by up to 30%.
In 2024 Humanwell leveraged wholesalers and distributors to extend national coverage across 31 provincial-level regions with about 320 regional partners, enabling efficient reach into hospitals and pharmacies. Value-added services from partners—financing and cold-chain logistics—support temperature-sensitive products and reduce stockouts. Data sharing with distributors improved demand planning, while consolidated shipments cut logistics costs by roughly 10%.
Online e-commerce and DTC channels extend reach for eligible products and devices as global e-commerce surpassed $5.7 trillion in 2023 and was projected beyond $6 trillion in 2024, while telehealth integration (≈15% of outpatient visits in 2024) ensures appropriate use and follow-up. Subscription models boost continuity, improving retention and predictable revenue, and digital analytics refine targeting and inventory to cut stockouts and CAC.
Local distributors navigate regulations and market norms, accelerating approvals and channel access; co-branding or private-label launches tailor products to local preferences. Tech transfers enable domestic manufacture where tariffs or supply chains constrain imports. Royalties (typical 5–10%) and milestone payments diversify revenue; 2024 licensing activity remained robust globally, supporting growth.
Hospital/tender procurement is the primary commercial channel, driven by centralized bidding (price cuts up to 90%) and clinical liaisons securing 1–3 year formulary access. Retail chains and 4.5B US prescriptions (2024) target OTC and chronic meds via pharmacist programs and co-pay integrations. Wholesale distribution (≈320 regional partners across 31 regions) plus e-commerce (> $6T global 2024) and telehealth (~15% outpatient 2024) extend reach.
| Channel | 2024 Metric |
|---|---|
| Hospital/Tender | Centralized cuts ≤90% |
| Retail Pharmacies | 4.5B US scripts |
| Distributors | ≈320 partners, 31 regions |
| E-commerce/Telehealth | >$6T; ~15% visits |
Hospitals and surgical centers are high-volume users of anesthetics and injectable drugs, supporting roughly 50 million US surgeries and over 300 million procedures globally per year (2024 estimates). Their primary value drivers are reliability, patient safety, and cost-effectiveness, with procurement largely via public tenders and GPOs (GPO penetration ~80% in US hospitals). They demand robust clinical training, 24/7 technical support, and validated supply-chain continuity.
Retail pharmacies and chains are key channels for OTC, reproductive and chronic therapies, with Chinese chain outlets exceeding 80,000 locations by 2024, capturing the bulk of front‑line consumer sales. They demand dependable supply, co‑marketing and category management support from suppliers. Margin structures, slotting fees and promotions materially influence product uptake and stocking decisions. Many chains now leverage digital ordering and analytics to optimize inventory and promotions in near real time.
Physicians and clinics—notably prescribers in anesthesia, OB/GYN, neurology, and primary care—require concise evidence, dosing guides, and patient materials to support office-based procedures. The US has about 1,062,000 active physicians (AMA 2023), many performing outpatient interventions that demand convenient formats. Rapid, responsive medical information and tailored materials increase clinician loyalty and prescription uptake.
Payers and health authorities determine access via reimbursement and formulary rules, requiring robust pharmacoeconomic evidence and budget-impact models; NICE commonly cites thresholds around £20,000–30,000 per QALY. Value-based contracts are increasingly used to align incentives for high-cost therapies, and decisions prioritize safety and real-world outcomes.
Consumers and patients are the primary end users for Humanwell’s OTC, reproductive-health products and selected devices, driving a global OTC market estimated near 150 billion USD in 2024. They prioritize simplicity, affordability and wide availability; digital support raises adherence—meta-analyses show improvements up to 30%. Transparent safety information measurably increases trust and repeat purchase intent.
Hospitals/surgical centers: ~50M US surgeries, ~300M global procedures (2024); prioritize reliability, safety, supply continuity. Retail pharmacies: >80,000 China outlets (2024); focus on supply, promotions, digital ordering. Physicians: ~1,062,000 US doctors (AMA 2023); need concise evidence and support materials. Consumers: OTC market ~150B USD (2024); value simplicity, price and digital adherence aids.
| Segment | Metric (2024) | Top Priority |
|---|---|---|
| Hospitals | 50M US surgeries; 300M global | Supply & safety |
| Pharmacies | >80,000 China outlets | Availability & promotions |
| Physicians | 1,062,000 US | Clinical evidence |
| Consumers | OTC ≈150B USD | Affordability & simplicity |
Discovery, preclinical and multi‑phase trials drive major outlays, with clinical stages consuming over 60% of R&D budgets and Phase III trials often costing $100–500M each. Specialty areas like CNS and biologics push costs higher due to longer timelines and manufacturing complexity. Regulatory studies and HEOR add protocol and market-access spend, often several million per indication. Pipeline risk necessitates active portfolio balancing to spread failure costs.
Facility operations, labor and utilities across chemical, biologics and device modalities drive core manufacturing spend; as of 2024 NMPA and WHO GMP requirements keep validation, documentation and routine audits ongoing. Continuous waste reduction and yield improvement programs materially protect margins, while cold-chain and aseptic processes add persistent capital and operating overhead.
Regulatory budgets include submission fees (FDA PMA ≈ $500k in 2024; 510(k) often $12k–$30k) and notified-body audits (€50k–€200k). Inspections, documentation and PMS/safety reporting typically consume 1–3% of revenue annually. Training, quality governance run $100k–$500k p.a., while legal and IP (patent filings $20k–$50k; enforcement/litigation often >$1M) round out compliance spend.
Sales, marketing, and market access costs include maintenance of field teams and KOL engagement, continuous medical education programs, tender participation with pricing support, and HEOR-led payer negotiations; digital marketing and e-commerce operations scale as China’s online pharma market surpassed RMB 400 billion in 2024.
Logistics and distribution drive major cost lines: warehousing, transportation and last-mile delivery raise supply-chain spend, with cold-chain handling for biologics increasing logistics costs roughly 20–30% in 2024; inventory holding and write-downs commonly represent 1–3% of revenues, while distributor margins range 8–20% and rebates typically 2–8%.
Clinical development consumes >60% of R&D with Phase III costs typically $100–500M and high-risk pipeline requiring portfolio diversification. Manufacturing and GMP compliance drive CAPEX/OPEX, cold-chain added cost +20–30% (2024). Sales, market access and logistics (distributor margins 8–20%; inventory write-downs 1–3%) and regulatory fees (FDA PMA ≈ $500k) are material ongoing spends.
| Item | 2024 Metric |
|---|---|
| Phase III cost | $100–500M |
| R&D share clinical | >60% |
| Cold-chain uplift | +20–30% |
| China online pharma | RMB 400B |
| Distributor margins | 8–20% |
Hospital and retail sales focus on anesthetics, CNS and specialty medicines, supplied through healthcare institutions and pharmacies. Pricing is set via government tenders, negotiated hospital lists and public reimbursement catalogs. Revenue is volume-driven with seasonal and procedural demand cycles and OR schedules. Active lifecycle management—new formulations, indications and patent strategies—sustains recurring revenue.
Retail and e-commerce channels drive direct consumer sales of OTC and reproductive health products, within a global OTC market estimated at about $160 billion in 2024 and China e-commerce accounting for roughly 30% of OTC volume. Strong brand equity and convenience allow premium pricing and higher gross margins. Bundles and subscription plans boost recurring revenue and predictability, while pharmacy cross-selling raises average basket value and customer lifetime value.
Biologics and specialty injectables command premium pricing for complex therapies and sterile formats, contributing to Humanwell’s higher-margin mix; the global biologics market reached about $420 billion in 2024, underpinning pricing power. Cold-chain logistics and bundled service packages (logistics, patient support) enhance value and reduce spoilage. Indication expansions steadily widen addressable markets while hospital tenders and contracts stabilize recurring demand.
Revenue stems from devices, kits and combo products that complement Humanwell’s core drug portfolio; global medical device market was estimated at about $566 billion in 2024, supporting cross-sell opportunities and margin diversification.
Recurring sales from disposables and accessories drive steady cash flow while service, installation and training deliver ancillary income and higher lifetime customer value.
Licensing generates upfronts typically from 5–200 million USD and milestone payments that can cumulatively reach hundreds of millions to >1 billion USD for late‑stage assets, with royalties commonly 3–12% on net sales (2024 industry norms).
Tech transfers and co‑development attract fees and equity swaps; outsourcing unused capacity to provide CMO/CRO services taps the ~60 billion USD global outsourced services market (2024 estimate).
Geographic distribution agreements deliver steady, contractually‑based royalty streams and market access fees that stabilize cash flow across regions.
Humanwell earns hospital and retail sales from anesthetics, CNS and specialty drugs via tenders and reimbursement; revenue is volume‑driven with lifecycle management sustaining repeat sales. OTC/e‑commerce (global ~160B USD in 2024; China ~30% share) and premium brands boost margins and subscriptions. Biologics (~420B USD 2024) and specialty injectables raise ASPs; devices (~566B USD 2024) and disposables add recurring cash flow. Licensing upfronts 5–200M USD, milestones up to >1B, royalties 3–12%; CMO/CRO market ~60B USD (2024).
| Stream | 2024 metric |
|---|---|
| OTC e‑commerce | 160B USD; China ~30% |
| Biologics | 420B USD |
| Devices | 566B USD |
| CMO/CRO | ~60B USD |


