
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
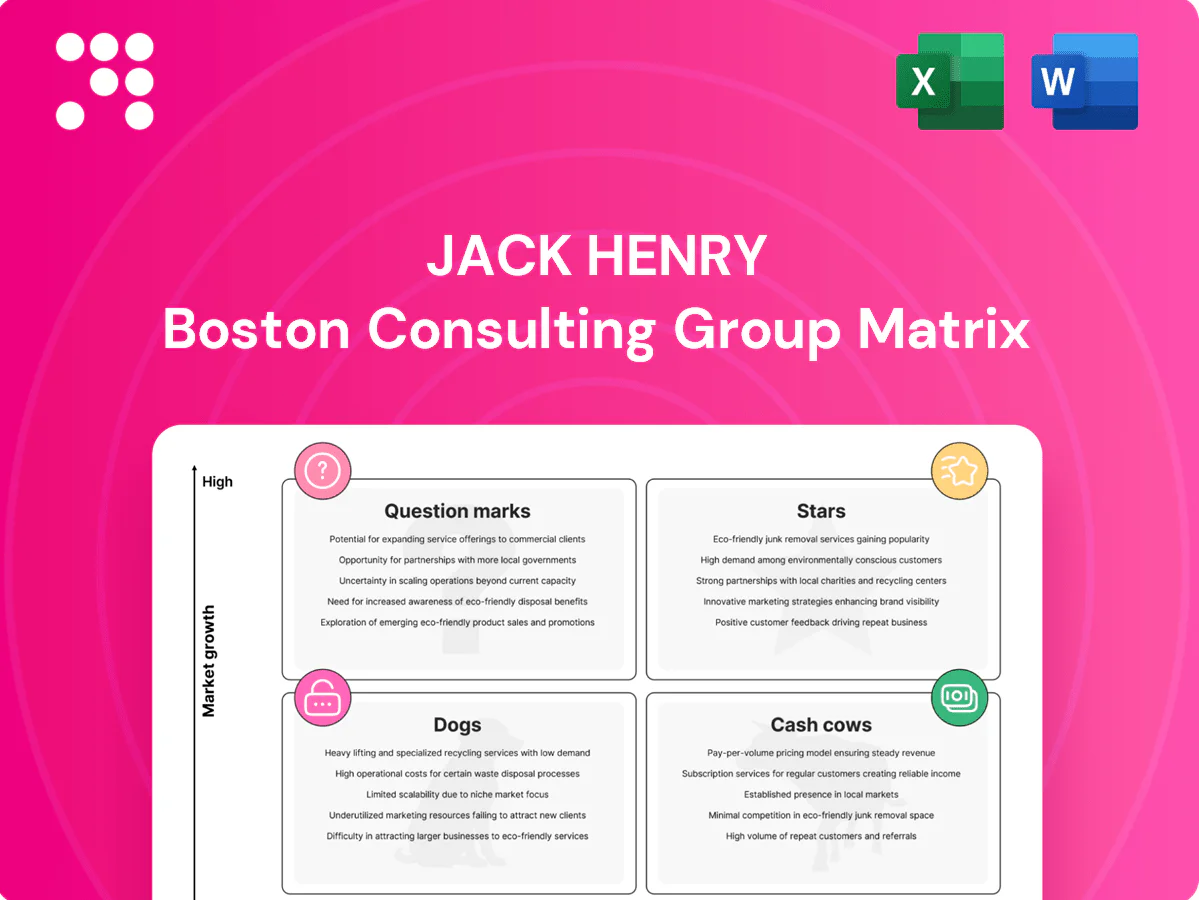
The Jack Henry BCG Matrix preview shows where key products land—stars, cash cows, dogs, or question marks—but it’s just the tip of the iceberg. Buy the full BCG Matrix to get quadrant-by-quadrant placement, data-backed recommendations, and a ready-to-use Word report plus an Excel summary you can present tomorrow. Skip the guesswork: get strategic clarity, prioritized actions, and the visuals you need to move capital and resources with confidence.
Digital banking is a Star: fast-growing channel where Jack Henry already penetrates roughly 9,000 financial institutions as of 2024. Mobile-first features, user-level personalization, and frequent releases drive stickiness and rising adoption. It soaks up investment but the runway to lead is clear. Hold share, keep shipping, and it can mature into a cash cow.
RTP (live since 2017) and FedNow (launched July 2023) drove a 2024 spike as institutions race to enable instant payments; Jack Henry’s deep connectivity and compliance capabilities position it to capture onboarding demand. Implementation is cash-hungry now—integrations, fraud/risk, operations—but solutions become defensible once embedded; scale quickly to lock network effects.
Attacks are up and losses hit hard: FBI IC3 reported $10.3 billion in reported cybercrime losses in 2023, driving boards in 2024 to prioritize fraud spend. Machine‑learning detection plus step‑up authentication keeps fraud visible and preserves budgets by cutting false positives and preventing escalations. It needs continuous model tuning and data investment but builds trust fast, creating durable platform pull‑through for Jack Henry.
Banks demand optionality, not lock-in, and APIs are the on‑ramp; Jack Henry’s open ecosystem reduces churn and attracted thousands of third‑party integrations by 2024, deepening platform stickiness.
Building and certifying integrations is costly, yet adoption accelerates: industry data shows API traffic and fintech transactions growing double‑digits annually through 2024.
Cloud‑delivered core extensions (origination, servicing, CRM) are Stars: adoption accelerated in 2024 as faster deployments and lower IT friction produced easy wins for clients. They require steady SRE and reliability spend but deliver strong attach and recurring revenue; Jack Henry reported FY2024 revenue of $1.78 billion, with technology services driving platform monetization. Keep bundling to cement platform share.
Digital banking, instant payments (RTP/FedNow) and cloud core extensions are Stars for Jack Henry: ~9,000 FI penetrated (2024), FY2024 revenue $1.78B, cloud add‑on attach >25% and industry cloud core SaaS ~20% YoY (2024). Cybercrime drove fraud spend after $10.3B losses (FBI IC3, 2023), increasing demand for ML detection and integrations. Invest to scale APIs, SRE, and integrations to convert growth into durable platform revenue.
| Metric | 2023/24 |
|---|---|
| FIs penetrated | ~9,000 (2024) |
| FY revenue | $1.78B (2024) |
| Cloud add‑on attach | >25% (2024) |
| Cloud SaaS growth | ~20% YoY (2024) |
| Reported cyber losses | $10.3B (2023) |
 Detailed Word Document
Concise BCG analysis of Jack Henry’s products with strategic guidance on Stars, Cash Cows, Question Marks, and Dogs.

 Customizable Excel Spreadsheet
One-page Jack Henry BCG Matrix that spots growth vs drain, simplifying portfolio decisions for faster, C-level clarity.
Core processing platforms: large installed base serving more than 9,000 financial institutions, anchored by multi‑year contracts and low churn. Mature market yields slower new wins but margins remain healthy, with steady recurring revenue. Incremental efficiency improvements and targeted upsell keep cash flowing. Maintain and modernize prudently; avoid over‑investing in net‑new core builds.
Debit/EFT and ACH processing deliver high-volume, predictable-fee revenue—Nacha reported ACH volumes exceeded 30 billion annually in 2023–2024—translating to stable demand and modest growth. Operating leverage is excellent: incremental transaction costs are low against fixed platforms, driving strong margin contribution. The play is reliability and compliance, not splashy features; milk the scale to fund growth bets elsewhere.
Managed hosting & support are cash cows with recurring contracts and sticky relationships; industry SLAs target 99.99% uptime, making reliability more valuable than novelty. Tooling and automation drive declining cost-to-serve, often cutting labor hours 20–30%. Pack SLA-backed upgrades and efficiency investments to sustain margins; downtime costs (industry estimate ~$5,600 per minute) justify premium pricing.
Back‑office workflow tools for deposits, lending, and reconciliation are entrenched in Jack Henry’s base, showing low market growth but high renewal economics; FY2024 revenue for the company was about $1.80 billion, with enterprise renewal and retention in core processing exceeding industry SaaS norms and reliably enabling seat/module upsells. Focus remains on stability, incremental UX improvements, and using these cash flows to underwrite newer, higher-growth bets.
Core processing, ACH/debit and managed hosting generate steady, high‑margin cash flow—FY2024 revenue ~$1.80B, renewal ~95%, ACH volumes >30B (2023–24); focus on reliability, compliance, and modest upsells to fund growth bets.
| Metric | Value |
|---|---|
| FY2024 Revenue | $1.80B |
| Renewal Rate | ~95% |
| ACH Volumes | >30B (2023–24) |
| Uptime SLA | 99.99% |
The Jack Henry BCG Matrix you're previewing is the exact file you'll receive after purchase. No watermarks, no demo notes—just a polished, ready-to-use strategic report. It’s crafted for clarity with market-backed insights and formatted for editing, printing, or presenting. Buy once, download instantly, and start using it with your team or stakeholders right away.
On‑prem only modules retain install‑base pockets—Jack Henry serves more than 9,000 financial institutions—but demand is fading as cloud adoption accelerates. Upgrade cycles are painful and costly, often requiring multi‑month projects and significant professional services spend. Turnarounds rarely pay back; sun‑set with care and redeploy talent to cloud migration and SaaS offerings.
Paper‑centric branch utilities face steep foot traffic declines, with branch visits down roughly 40% since 2019 and digital channels now handling the majority of interactions, making digital substitutes far cheaper. Revenue per branch is flat to declining while support costs and compliance burden rise, squeezing margins. Differentiation is minimal versus fintechs and digital offerings. Recommend bundling into end‑of‑life plans and exiting nonstrategic footprints.
Legacy report writers sit in the Dogs quadrant: old tooling eclipsed by modern BI and APIs, delivering no growth while clients tolerate them until migration windows. McKinsey 2024 found roughly 70% of IT spend goes to maintenance, mirroring how support costs erode product margins here. Recommend active migration paths and limit new feature development to minimize ongoing support burden.
Standalone bill-pay lags as fintechs set UX and real‑time expectations; Jack Henry reported approximately $1.86 billion revenue in FY2024, yet basic bill‑pay loses share to integrated fintechs. Pricing pressure squeezes margins, rebuilds require significant capex with limited upside, so folding into the core digital suite or retiring the product is pragmatic.
Featurelets serving edge cases don’t scale: small‑adoption modules create disproportionate sales and support overhead that can exceed their revenue contribution. Divest or deprecate these Dogs to refocus the roadmap on scalable products and free engineering capacity for growth areas with higher ROI. Prioritize sunsetting low-use features to reduce maintenance burden and accelerate core innovation.
On‑prem modules keep pockets across >9,000 FI clients but cloud demand erodes them; upgrades are costly and rarely pay back so sunsetting and talent redeploy is advised. Branch utilities face ~40% drop in visits since 2019, flat per‑branch revenue and rising costs—bundle or exit. Legacy report writers and bill‑pay lose share; Jack Henry FY2024 revenue ~$1.86B—deprecate/divest low‑ROI items.
| Product | Issue | 2024 metric | Action |
|---|---|---|---|
| On‑prem modules | Declining demand | >9,000 clients | Sunset/repurpose |
| Branch utilities | Footfall drop | -40% visits vs 2019 | Bundle/exit |
| Legacy tools | High maintenance | 70% IT spend maint. | Migrate/limit dev |
| Bill‑pay | UX loss | FY2024 rev $1.86B | Fold/retire |
By 2024 roughly 60% of banks report GenAI pilots for frontline support and advisory, signaling high interest but no clear winner yet.
If models remain safe and accurate, estimates show up to 30% servicing-cost reduction and pilot NPS uplifts of about 5–10 points.
Successful scale needs strict data governance, full auditability, and tight core-system hooks.
Action: double down on use cases with measurable lift or cut within 6–12 months.
Embedded banking/BaaS is an exploding category, with McKinsey and others projecting the embedded-finance revenue pool at over $200 billion by 2025, but it operates in regulatory fog across banking, consumer protection, and third-party oversight. Packaged with robust risk controls and real-time monitoring, community banks can safely play offense and win share. Land a few flagship programs to prove unit economics before scaling. If contribution margins compress materially, exit early to avoid capital drag.
Banks seek deeper relationships with ~33.2 million US small businesses (SBA 2023), making cross-sell of SMB merchant add‑ons tempting, but the market is crowded with players like Stripe, PayPal, Square and incumbents. Take rates run roughly 1–3% for card processing, thin without scale, so test integrated payouts, invoicing and lending loops. Invest where attach to the core is strongest and repeatable.
Question Marks: Data monetization & insights—Jack Henry has a compelling story delivering actionable insights across deposits and lending to its more than 9,000 client institutions, but buyer enthusiasm for dashboards outpaces consistent ROI proof. With the right connectors and packaged integrations, upsell potential could accelerate materially; McKinsey 2024 finds top data-driven banks can boost revenue by up to 20% from personalization and analytics.
Open banking/consent management sits as a Question Mark for Jack Henry: regulatory moves accelerated in 2024 (CFPB consumer access proposals; PSD2 enforcement continues), so banks must deliver clean consent flows and hardened APIs quickly to capture nascent demand. Interest is forming but not fully budgeted; build compliance‑led bundles to convert trials into paid deals.
Question Marks: GenAI, data monetization and open banking show strong interest but uneven ROI—60% of banks ran GenAI pilots in 2024 and Jack Henry’s 9,000+ clients give scale optionality, yet buyer budgets lag.
Action: focus on deposits/lending connectors, compliance‑led API bundles and 6–12 month proofs of unit economics.
| Segment | 2024 signal | Upside |
|---|---|---|
| GenAI | 60% pilots | 30% servicing cost cut |
| Data | 9,000+ clients | ↑20% rev (McKinsey 2024) |
| Open banking | Regulator push 2024 | Emerging monetization |


