
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
See how the whole operating model connects.
Link the offer to segments, channels and relationships.
Review revenue streams, costs, resources and partners.
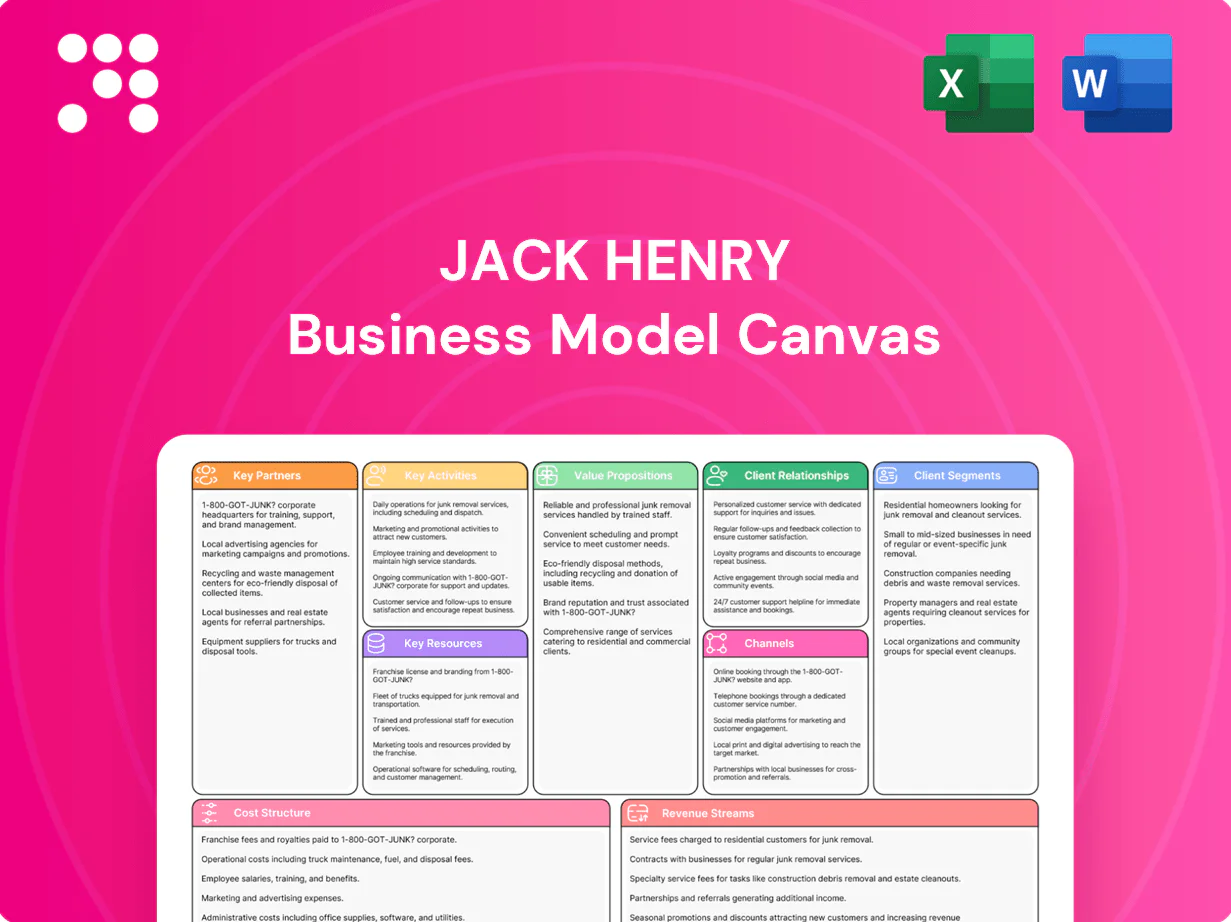
Unlock Jack Henry’s strategic playbook with a concise Business Model Canvas that maps its value propositions, key partners, and revenue mechanics in plain terms. This 3–5 sentence snapshot highlights why the company scales and where opportunities lie. Purchase the full, editable Canvas for a section-by-section toolkit ideal for investors, strategists, and founders.
Partnerships with ACH, RTP (live since 2017), FedNow (launched July 2023), wire networks and card schemes enable Jack Henry to offer end-to-end payment processing, broad acceptance and settlement reliability; ACH moves tens of billions of payments annually, supporting favorable economics, instant-pay features, fraud controls and faster certification and compliance updates.
Alliances with hyperscalers (AWS ~32%, Microsoft Azure ~23%, Google Cloud ~11% in 2024) and hosting partners provide secure, scalable delivery that supports targeted 99.99% uptime and robust disaster recovery. They underpin elastic performance for peak loads and enable joint architectures that accelerate modernization of core systems and digital channels. Co-selling with these partners broadens reach and credibility across Jack Henry’s ~9,000 client institutions.
Third-party fintechs extend Jack Henry platforms via APIs and prebuilt integrations, enabling banks to adopt niche solutions with minimal lift; in 2024 banks reported roughly 50% faster deployments using such integrations. Curated marketplaces reduce vendor risk and lower integration cost, with pilots showing vendor selection time cut by about 30% in 2024. Ongoing co-innovation keeps offerings aligned with market demand and regulatory shifts.
Specialist cybersecurity and fraud vendors supply threat intelligence, authentication and continuous monitoring that harden Jack Henry platforms against evolving attacks; 2024 industry pilots report integrated controls can reduce fraud losses and false positives by about 20–25%. Shared product roadmaps and SLAs enable coordinated, rapid responses to new vectors, lowering incident dwell time and operational losses.
Engagement with regulators, standards groups and bank associations guides Jack Henrys compliance posture and product roadmaps; Jack Henry serves more than 9,000 financial institutions (2024), so early visibility into rule changes reduces change-management cost and downtime, supports audits, reporting and exam readiness, and lets participation shape practicable standards for clients.
Partnerships with ACH, RTP (live 2017), FedNow (launched Jul 2023), wires and card schemes enable end-to-end payments for ~9,000 clients. Hyperscalers (AWS ~32%, Azure ~23%, Google ~11% in 2024) and fintech/API partners accelerate modernization and cut deployment time ~50%. Cybersecurity and regulator alliances reduce fraud/false positives ~20–25% and lower compliance costs.
| Metric | 2024 / note |
|---|---|
| Clients | ~9,000 |
| Cloud share | AWS 32% / Azure 23% / GCP 11% |
| Deployment speed | ~50% faster |
| Fraud reduction | 20–25% (pilots) |
 Detailed Word Document
A concise, pre-built Business Model Canvas for Jack Henry that maps customer segments, channels, value propositions, and revenue streams aligned with the company’s fintech strategy. Organized into nine BMC blocks with competitive analysis, SWOT linkage, and polished narrative for presentations, investor discussions, and operational decision-making.

 Customizable Excel Spreadsheet
High-level, editable one-page snapshot of Jack Henry’s business model that saves hours of structuring and makes boardroom-ready comparisons and team collaboration effortless.
Continuous enhancement of Jack Henry core systems and online/mobile banking is central, supporting over 9,000 financial institutions (2024). Development prioritizes performance, new features and usability, delivered via modular releases to reduce client disruption. Product backlogs are triaged against regulatory deadlines and market demand.
Running high-volume, low-lency payment rails is mission-critical for Jack Henry, which serves over 9,000 financial institutions and processes millions of payments daily. Activities include settlement, reconciliation, and exception management supported by automated workflows. Controls and redundancy frameworks enforce risk limits and target high uptime. Rich data feeds power reporting, fraud analytics, and regulatory filings.
Implementations move institutions from legacy stacks to modern platforms. Methodologies reduce conversion risk and downtime through staged cutovers and parallel testing. Data mapping and testing are rigorous and training accelerates adoption post go-live; as of 2024 Jack Henry serves more than 9,000 financial institutions.
Security engineering and governance protect sensitive financial data through layered controls and certified frameworks; Jack Henry maintains SOC 1 and SOC 2 attestation alongside PCI DSS and ISO 27001 alignment. Regular external audits and certifications sustain trust and client exam-readiness, while compliance updates map to evolving bank regulations. Incident response tabletop and live exercises strengthen operational resilience and recovery capabilities.
Open APIs link Jack Henry platforms to third-party solutions and bespoke workflows, supporting more than 9,000 financial institutions as of 2024. SDKs and sandboxes accelerate developer time-to-market and reduce testing cycles. Certification enforces performance and security standards for partners. Comprehensive documentation and dedicated support minimize integration friction and operational risk.
Continuous enhancement of core systems and digital channels supports more than 9,000 financial institutions (2024), prioritizing modular releases, performance and regulatory backlogs. High-volume, low-latency payments and settlement run with automated reconciliation and redundancy targeting 99.99% uptime. Security governance holds SOC 1/2, PCI DSS and ISO 27001 attestations.
| Metric | Value |
|---|---|
| Financial institutions (2024) | >9,000 |
| Payments processed | millions/day |
| Uptime target | 99.99% |
| Certifications | SOC 1/2, PCI DSS, ISO 27001 |
The Jack Henry Business Model Canvas you see here is the actual deliverable, not a mockup or sample. When you purchase, you’ll receive this same document in full—formatted and ready to edit. The file includes all sections visible in the preview and is provided in editable Word and Excel formats. No surprises—what you preview is what you’ll download.
Owned core processing and digital banking software are foundational assets for Jack Henry, which serves more than 9,000 financial institutions. These platforms embody decades of domain logic and compliance built into proven workflows. Modular IP enables cross-sell into adjacent areas such as payments and lending. Patents and licensing protections underpin product differentiation.
Direct connections to ACH, card networks, wires and RTP are critical: ACH handled about 30 billion U.S. transactions in 2023 while RTP volumes grew roughly 40% in 2024, enabling faster settlement. These links enable reliable, fast, compliant fund movement and established network certifications shorten time-to-market. Multi-network redundancy preserves continuity, reducing outage risk and supporting SLAs for thousands of financial institutions.
Secure hosting, enterprise databases and data lakes underpin Jack Henry’s operations and analytics, supporting the company’s more than 9,000 financial-institution clients. Observability stacks deliver near 99.99% performance visibility and SLA tracking. Multi-region DR sites and automated backup routines preserve availability, while integrated tooling enforces model risk management for analytics and compliance.
Engineers, bankers, compliance experts and support staff at Jack Henry convert complex regulation into scalable product features; their cross-functional expertise supports a client base of 9,000+ financial institutions (2024). 24/7 operations uphold strict SLAs (platform uptime and incident response) while customer success teams drive retention and revenue expansion.
Jack Henry’s longstanding trust with more than 9,000 community banks and credit unions (2024) is a strategic asset that shortens sales cycles via client references; active user groups and hundreds of advisory councils feed direct product input, while a decades-long reputation materially lowers perceived switching risk for prospects.
Owned core processing and digital platforms serve 9,000+ FI clients (2024), with patents and modular IP enabling cross-sell into payments and lending. Direct ACH/card/RTP links (ACH ~30B txns 2023; RTP +40% 2024) ensure fast, compliant settlement and redundancy for SLAs. Cloud, DR and observability (~99.99% visibility) support analytics and uptime; 24/7 ops and advisory councils drive retention.
| Metric | Value |
|---|---|
| Clients | 9,000+ |
| Founded | 1976 |
| ACH | ~30B (2023) |
| RTP growth | ~40% (2024) |
Integrated core, digital, payments, and risk tools reduce vendor sprawl, lowering total integration costs and accelerating deployment; Jack Henry reported FY2024 revenue of about $2.0 billion, reflecting scale that supports platform consolidation. Institutions gain unified data and a consistent UX across channels, improving operational efficiency and analytics. Lower integration burden speeds projects, and one throat to choke simplifies accountability for enterprise clients.
Reliability and compliance by design delivers industry-standard four nines (99.99%) availability with audit-ready controls that meet regulator and board expectations. Built-in compliance features reduce exam surprises while standardized, scheduled updates lower change risk. Prepackaged evidence packs streamline audits and accelerate evidence collection.
Open, modular architecture uses APIs and microservices to enable choice and extensibility, letting clients add or swap modules without costly replatforming. A broad partner ecosystem widens solution options and accelerates integrations. Serving over 9,000 financial institutions as of 2024, Jack Henry leverages faster innovation cycles to help clients protect competitiveness.
Cost-efficient modernization through SaaS delivery and shared services lowers total cost of ownership by consolidating infrastructure and support, while automation cuts manual back-office workload and error rates, freeing staff for higher-value tasks. Elastic capacity aligns cost with demand to avoid overprovisioning, and predictable pricing simplifies budgeting and cash-flow planning.
Modern digital channels in Jack Henry accelerate speed and usability, with 80% digital banking adoption in 2024 and real-time rails moving payments from days to seconds. Instant payments and granular card controls boost engagement and retention, while consistent web and mobile interfaces ensure seamless journeys across touchpoints. Analytics-driven personalization can lift engagement and revenue by up to 15%.
Integrated core, digital, payments, and risk tools reduce vendor sprawl and lower integration costs; FY2024 revenue ~2.0B supports platform consolidation. Built for 99.99% availability and audit-ready controls to ease compliance. Open API architecture and 9,000+ FI footprint enable extensibility and faster integrations, with 80% digital adoption and up to 15% personalization uplift.
| Metric | 2024 |
|---|---|
| Revenue | $2.0B |
| Clients | 9,000+ |
| Uptime | 99.99% |
| Digital adoption | 80% |
| Personalization uplift | up to 15% |
Named account teams coordinate roadmaps, issues and expansions for Jack Henry, which serves over 9,000 financial institutions (2024), translating business goals into deliverable plans aligned to client priorities. Regular monthly and quarterly reviews track KPIs and realized value to clients. Clear escalation paths ensure responsiveness and faster resolution for critical issues.
Multi-year agreements with Jack Henry align incentives for stability and platform evolution, leveraging service-level agreements that stipulate typical uptime targets of 99.9% and defined response times. Renewal cycles (commonly 3–5 years) enable roadmap refreshes tied to customer needs; volume tiers reward growth with escalating discounts (up to ~20% at higher bands) across the >9,000 FI customer base (2024).
Always-on helpdesks handle critical banking operations for Jack Henry, supported by roughly 6,000 employees in 2024 to ensure continuous incident management. Clear severity levels (S1–S4) guide escalation and SLA-driven action. Postmortems from major incidents feed root-cause fixes and resilience investments. Self-service portals and knowledge bases reduce ticket volume and speed resolution.
Workshops, certifications and e-learning accelerate adoption for Jack Henry customers, with the company supporting over 9,100 financial institutions as of 2024 and industry studies showing training can reduce onboarding time by up to 40%. Role-based curricula target admins and operators to shorten time-to-competency, updated content tracks product releases and regulatory changes, and sandboxes provide safe, production-like practice environments.
Advisory councils and forums channel structured feedback from Jack Henrys client base of more than 9,000 banks and credit unions, shaping product priorities. Co-design pilots with select users de-risk launches by validating features in live environments before wide release. Peer sharing through user groups accelerates adoption of best practices, while transparent roadmaps increase client trust and reduce churn.
Named account teams support 9,100+ financial institutions (2024) with monthly/quarterly KPI reviews and SLA-backed escalations (99.9% uptime target). Multi-year (3–5 yr) contracts and volume tiers (up to ~20% discount) drive renewals. 24/7 helpdesk, ~6,000 employees (2024), self-service and role-based training cut onboarding ~40%.
| Metric | Value (2024) |
|---|---|
| Customers | 9,100+ |
| Employees | ~6,000 |
| Uptime SLA | 99.9% |
| Renewal cycle | 3–5 yrs |
| Max discount | ~20% |
| Onboarding reduction | ~40% |
Field sales and solution consultants target banks and credit unions, leveraging Jack Henry’s reach to more than 9,000 financial institutions. Discovery aligns products to institutional workflows; demos and pilots prove ROI in live environments. Executive alignment with C-suite sponsors accelerates procurement and implementation timelines.
Post-sale customer success teams at Jack Henry surface expansion opportunities across its customer base, which serves more than 9,000 financial institutions. Regular health checks identify product and process gaps that prioritize interventions. Adoption metrics and usage dashboards drive next-best-offer recommendations and timing. Customer case studies deliver quantifiable ROI stories that accelerate internal buy-in for upsell initiatives.
Content, webinars (44% average webinar attendance in 2024), and interactive calculators educate prospects and qualify deals early, shortening sales cycles by up to 30% through self-serve materials. SEO and targeted digital campaigns drive inbound demand, accounting for a majority of organic leads. Client portals deliver digital servicing and cross-sell opportunities for existing Jack Henry customers.
Conferences, regional forums, and association partnerships amplify Jack Henry’s presence and access to over 9,000 financial institutions (2024). Securing speaking slots establishes thought leadership while live demos of core banking and payments systems build credibility and trust. Focused networking at events converts relationships into sales pipelines and partner integrations.
In 2024 Jack Henry’s developer portal and marketplaces leverage APIs, developer docs, and sandboxes to attract partners and clients’ IT teams, shortening integration cycles and increasing certified integrations visibility. Marketplace listings showcase certified integrations and reference architectures, while support channels and playbooks speed builds. Built-in analytics track ecosystem usage and partner performance to prioritize investments.
Field sales and solution consultants reach more than 9,000 financial institutions (2024) with demos/pilots proving ROI; customer success uses health checks and dashboards to drive expansion. Content and webinars (44% avg attendance in 2024) plus self-serve tools shorten sales cycles by up to 30%. Developer portal, APIs and marketplace accelerate integrations and partner visibility.
| Metric | 2024 Value |
|---|---|
| Financial institutions reached | >9,000 |
| Average webinar attendance | 44% |
| Sales cycle reduction (self-serve) | Up to 30% |
Community banks require efficient, compliant core systems and modern digital channels to serve local markets while meeting regulatory demands; they collectively hold about 20% of U.S. domestic deposits (FDIC, 2024). They prioritize reliability and high-touch service, prefer modular solutions that fit constrained budgets, and make purchasing decisions heavily influenced by peer relationships and vendor references.
Member-centric credit unions demand tailored digital experiences to improve member service and reduce fees; US credit unions hold over $2 trillion in combined assets and serve more than 100 million members (2024). Deep integrations with core systems and member services drive efficiency and cross-sell. Built-in compliance support lowers regulatory burden and operational cost, enhancing service delivery.
Regional banks and thrifts, typically defined as institutions with $10B–$250B in assets, require scale and enterprise-grade payments.
They demand measurable performance, resilience, and advanced analytics for risk management and fee optimization.
Multi-entity legal, accounting and ledger support is essential for holding-company structures.
Product roadmaps must match the rapid pace of fintech competition and regulatory change.
Embedded finance players demand APIs and rapid onboarding to deploy products; in 2024 fast RESTful APIs, sandbox environments and compliance scaffolding (SOC 2 Type II, PCI DSS, ISO 27001) are table stakes. Volume pricing and low-latency integrations drive partner economics, while certifications and sandbox-driven testing accelerate go-to-market.
Lenders, mortgage servicers, and specialty finance firms need robust back-office platforms for loan servicing, payments, risk and compliance; Jack Henry, serving over 9,000 financial institutions, positions payment and risk modules alongside centralized reporting and integrations to handle multi-trillion mortgage portfolios; predictable SaaS pricing preserves lender margins.
Community banks (≈20% of US deposits, FDIC 2024) need reliable, modular cores and high-touch service; credit unions (>$2T assets, 100M members, 2024) demand member-centric digital integrations; regional banks ($10B–$250B) require enterprise-grade scale, analytics and multi-entity ledgers; embedded finance and lenders prioritize APIs, compliance scaffolding and predictable SaaS economics; Jack Henry serves >9,000 FIs (2024).
| Segment | Key need | 2024 metric |
|---|---|---|
| Community banks | Modular core, reliability | 20% US deposits |
| Credit unions | Member digital CX | $2T assets;100M members |
| Regional banks | Scale, analytics | $10B–$250B |
| Embedded/lenders | APIs, compliance | Jack Henry: >9,000 FIs |
Jack Henry drives significant spend on software development and QA that shapes its product roadmap; in FY2024 the firm reported roughly $1.9B revenue with R&D-level investment representing a material portion of operating spend. Security and compliance add measurable overhead through audits, certifications and third-party controls. Tooling and testing environments are ongoing costs for staging, synthetic data and performance labs. Continuous delivery pipelines require steady investment in CI/CD, automation and observability.
Cloud and hosting opex for Jack Henry is dominated by compute, storage, networking and observability — DR, backups and multi-region redundancy add significant incremental costs. Platform and database licenses (third-party and commercial open-source subscriptions) materially raise recurring spend. Ongoing performance tuning and SRE efforts consume engineering hours and cloud credits; industry public cloud spend reached roughly $600 billion in 2024, highlighting sector cost pressure.
Salaries, benefits and training are a material line item for Jack Henry, which employed roughly 6,000 staff in 2024, driving multi-hundred-million-dollar annual personnel costs. 24/7 support staffing adds significant wage premiums and overtime, creating a multi-million-dollar run rate. Professional services scale with implementations, and ongoing recruiting and retention programs sustain elevated hiring and training spend.
Compliance, certifications and third-party audits drive recurring spend for Jack Henry, which since 1976 serves over 9,000 financial institutions; legal and risk management are continuous line items, and cyber insurance premiums scale with exposure and breach risk, while dedicated vendor management oversight is required to control third-party risk.
Sales, marketing, and partnerships drive significant recurring spend for Jack Henry; go-to-market teams and campaigns, plus event sponsorships and travel, are material line items. Partner enablement and revenue-share agreements compress margins, while solution consulting and pre-sales support raise fixed costs. Jack Henry reported FY2024 revenue of 2.16 billion, framing the scale of GTM investment.
Jack Henry's cost base centers on heavy R&D and QA spend tied to a multi-product roadmap, material cloud/hosting opex and third-party platform licenses, plus continuous CI/CD and SRE investments. Personnel (≈6,000 employees in 2024) and 24/7 support create large recurring wage costs. Compliance, audits, vendor risk and GTM (FY2024 revenue $2.16B) further compress margins.
| Metric | 2024 |
|---|---|
| Revenue | $2.16B |
| Employees | ~6,000 |
| Public cloud spend (sector) | $600B |
Recurring SaaS fees for core processing, digital channels, and risk modules form Jack Henry’s revenue base, with tiers that scale by seats, accounts, or feature sets. Multi-year contracts (common in enterprise banking) stabilize cash flows and support predictable ARR, while add-ons and professional services lift ARPU. In 2024 Jack Henry served roughly 9,000 financial institutions, expanding recurring revenue mix.
Per-transaction and volume-based fees monetize payments with typical per-item fees ranging $0.05–$0.30 and card interchange averaging about 1.5–2.0% for credit and 0.2–0.5% for debit in 2024. Interchange sharing and network pass-throughs apply, reducing net yield but preserving volume economics. Premium rails such as RTP command 20–50% higher rates, while exception handling (returns, disputes) can be separately billable, commonly $25–35 per item.
Annual maintenance and support contracts cover software updates, security patches and 24/7 assistance; premium SLA tiers command higher fees tied to response times and dedicated support. Uptime commitments of 99.9%+ justify premium pricing by reducing outage risk and cost to clients. Contracts often include indexation clauses tied to US CPI (3.4% in 2024) to preserve long‑term economics.
Implementation, data conversion and customization drive Jack Henry professional services revenue, supporting product sales and contributing to scale—Jack Henry reported approximately 2.06 billion in FY2024 revenue, with services enhancing deal value. Fixed-plus-variable pricing controls scope and boosts margin; training and change management are sold as add-ons; advisory services increase client stickiness and recurring spend.
Jack Henry sells reporting, fraud, and decisioning tools as add-on modules, packaging analytics and risk insights that save client implementation and operational time. The platform serves more than 9,000 financial institutions (2024), enabling usage-based pricing that aligns fees with delivered value. API access and metered premium endpoints create clear monetization paths and boost incremental revenue per client.
Recurring SaaS, multi-year contracts and professional services formed Jack Henry’s revenue base; FY2024 revenue was 2.06B and the platform served ~9,000 financial institutions. Payments: per-item fees $0.05–0.30; interchange ~1.5–2.0% (credit), 0.2–0.5% (debit). Support SLAs 99.9%+ and CPI indexation (US CPI 3.4% in 2024) protect margins.
| Metric | 2024 |
|---|---|
| Revenue | 2.06B |
| Clients | ~9,000 |
| Per-item fee | $0.05–0.30 |
| Interchange (credit) | 1.5–2.0% |
| Interchange (debit) | 0.2–0.5% |
| CPI indexation | 3.4% |


