
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
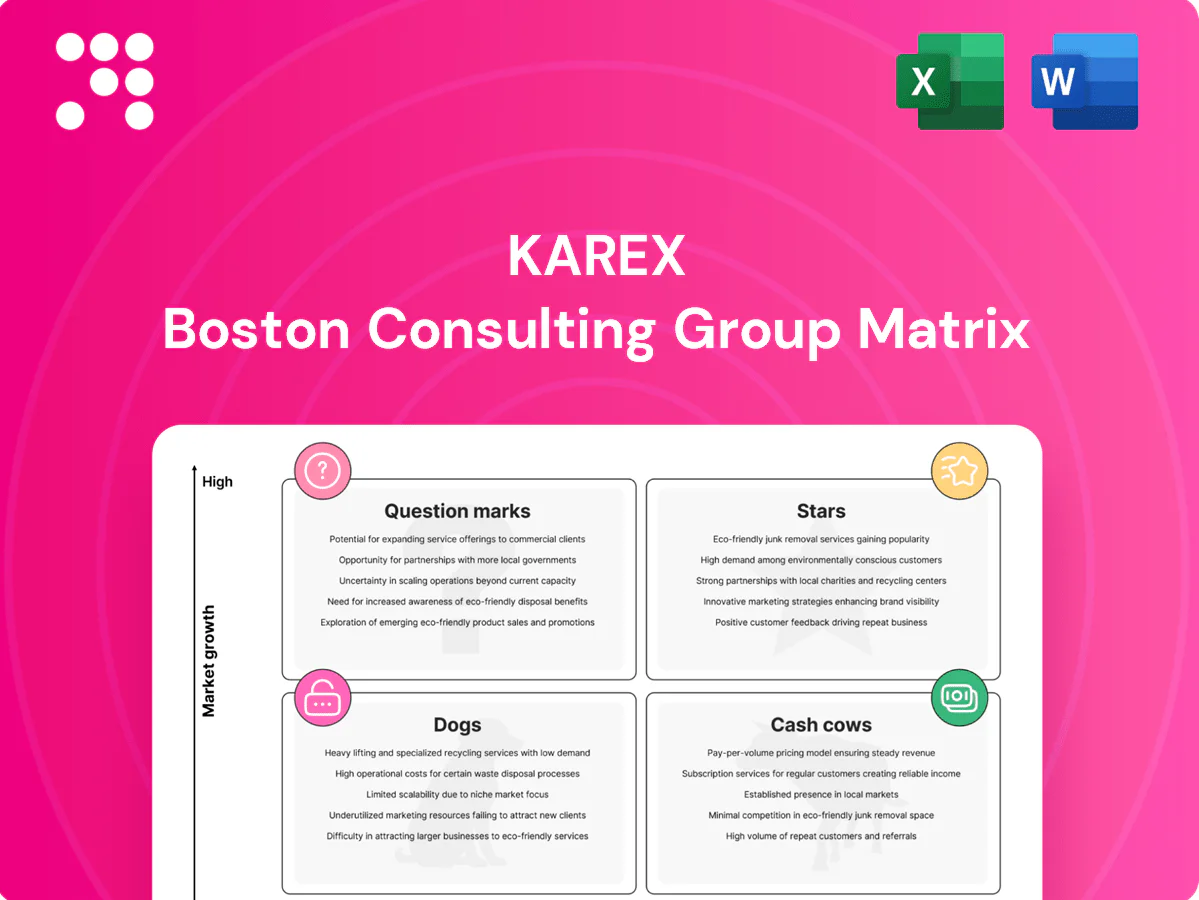
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Want a clear snapshot of Karex’s product landscape—what’s a Star, what’s bleeding cash, and where the next big wins could be? This preview teases the picture; buy the full Karex BCG Matrix for quadrant-by-quadrant placement, data-backed recommendations, and a ready-to-use Word and Excel pack. Skip the guesswork and get strategic clarity fast—purchase now and start reallocating capital with confidence.
Karex, the world’s largest condom manufacturer at about 5 billion units annually, sits in the Stars quadrant as the sexual wellness market grows ~6% CAGR (2024 est.). Private-label and major-retailer pipelines keep volumes rising, but capacity, QA and co-innovation demand heavy capex; tooling, automation and compliance often make cash in equal cash out. Hold the lead and these lines can mature into materially higher-margin cash cows.
Premium, design-forward ONE condoms and lubes are outpacing legacy SKUs in fast-growing online channels as global e-commerce reached a 21.8% share of retail sales in 2023. Share is climbing but aggressive promo, sampling and creator partnerships are cash-consuming. Continue funding awareness and retail placement while the category expands. If current momentum holds, ONE can become a dependable profit engine.
Personal lubricants ride the wellness wave and cross-sell with condoms; the global lube market topped an estimated 3 billion USD in 2024 and is growing mid-single digits annually, while Karex already supplies about 20% of world condoms and operates in 140+ countries, enabling rapid scale via OEM plus own brands; marketing and regulatory approval spend runs into millions per major market today, and securing repeat purchase turns a growth-hungry SKU into a cash-rich staple.
Consumers trade up for feel and function and the ultra-thin/textured/specialty subsegment is outpacing the base; premium formats are driving higher ASPs. Karex’s R&D and co-development with brand partners, backed by a manufacturing capacity >5 billion condoms/year (2024), place it in the front pack. Tooling and validation inflate working capital temporarily; sustaining quality at scale converts this star into a cash cow.
Global health initiatives scaled institutional distribution in 2024, increasing demand for certified suppliers; Karex, the world’s largest condom manufacturer by volume, is positioned as a preferred supplier with global certifications and presence in 100+ markets.
Karex sits in Stars: >5 billion condoms/year capacity (2024), benefiting from a ~6% sexual-wellness CAGR (2024 est.) and premium SKUs driving higher ASPs; ONE and lubes outpace legacy SKUs but require heavy capex, tooling and marketing. Convertable to cash cow if quality and scale sustain while promo spend normalizes.
| Metric | 2024 |
|---|---|
| Capacity | >5bn units |
| Market CAGR | ~6% |
| Lube market | $3bn |
 Detailed Word Document
Concise BCG analysis of Karex products—Stars, Cash Cows, Question Marks, Dogs—with clear invest, hold, divest guidance.

 Customizable Excel Spreadsheet
One-page Karex BCG Matrix that maps units into quadrants, cutting analysis time and clarifying portfolio decisions.
Standard latex condom SKUs are Karex cash cows: as the world's largest condom manufacturer with installed capacity around 5 billion condoms per year (2024), mature demand and dominant share deliver steady margins and dialed-in yields. Low incremental marketing and high line efficiency keep incremental costs minimal; cash out is mainly maintenance capex. These profits bankroll R&D and new-market expansion initiatives.
Private label for established retailers delivers predictable, high-volume sales in mature markets, providing Karex with steady utilization of manufacturing capacity. Long contracts and retailer switching costs preserve margins and reduce volatility. Minimal promotional spend shifts focus to service levels and OTIF performance to avoid stockouts. These contracts produce reliable cash flows that stabilize the P&L.
Pharmacy channel multipacks (core ranges) drive high repeat purchases with an estimated repeat rate around 70% and deliver stable basket behavior, accounting for the majority of routine SKU turns in 2024. Strong on-shelf presence and known trade terms keep out-of-stock low and sell-through high. Promotions are templated and efficient, driving predictable uplifts, while manufacturing is optimized for these pack sizes—classic milk-the-line economics.
Regional legacy brands Carex and Trustex sit in mature, low-growth markets yet remain entrenched and profitable where they operate, delivering steady margins rather than hypergrowth; global condom market size was estimated at about US$9.4bn in 2024, supporting durable demand.
Modest marketing spend preserves brand awareness while a tuned supply chain and SKU familiarity keep production costs low, enabling reliable free cash flow and margin stability for Karex.
OEM repeat runs with long-standing clients deliver recurring specs, low revalidation needs and highly predictable forecasts, keeping production schedules stable and inventory turns efficient.
Minimal engineering changeovers reduce unit costs and scrap, while limited need for heavy promotion preserves margin; these steady contracts quietly fund Karexs strategic R&D and capacity expansions.
Cash cows: standard latex SKUs, private-label and pharmacy multipacks deliver steady margins and predictable cash flow—installed capacity ~5 billion condoms/year (2024), global market ≈US$9.4bn (2024), pharmacy repeat rate ~70%, profits fund R&D and capacity expansions.
| Metric | Value (2024) |
|---|---|
| Installed capacity | ~5 billion condoms/year |
| Global condom market | ≈US$9.4bn |
| Pharmacy repeat rate | ~70% |
| Role | Predictable cash generation for R&D/capex |
The file you’re previewing here is the exact BCG Matrix document you’ll receive after purchase. No watermarks, no demo text—just the fully formatted, ready-to-use report built for strategic clarity. It’s crafted by analysts and formatted for immediate editing, printing, or presenting. Buy once, download instantly, and drop it straight into your planning or client decks—no surprises, no revisions needed.
Low-demand novelty SKUs (gag/odd flavors) serve niche interest with sporadic orders, often representing under 3% of unit demand in the condom category in 2024. They create awkward inventory, tie up line time and complicate planning, while turnaround spends rarely move the needle. Pruning these SKUs frees capacity and reduces scheduling complexity.
Fragmented micro-brands in saturated niches show limited differentiation and pull, leaving marketing spend ineffective without scale and often cannibalizing channel economics. Margin compression from promotions and complex distribution erodes profitability, especially for suppliers like Karex that supply to more than 140 countries. Consider consolidation to gain scale or strategic exit for non-core SKUs to restore margin and free capital.
Short runs drive 8–12% packaging waste and frequent changeovers that add roughly 20% to unit costs, squeezing margins at Karex as demand is flat-to-declining (≈2% YoY softening in mature markets in 2024). Revamps typically show payback periods beyond five years for low-volume formats, making capital retooling uneconomic. Sunset obsolete SKUs, standardize formats and redeploy capacity to core, higher-volume lines.
Non-core healthcare disposables for Karex show low market share and face a commodity-pricing trap that ties up cash; sector-wide volume growth was modest in 2024 (≈5% year-on-year), leaving margins under pressure and returns below core product thresholds. Competes with large device players on cost alone, making sales effort exceed financial returns; divestment or OEM partnerships are recommended over in-house scale-up.
Dogs: low‑demand SKUs (<3% unit share), low margins, high ops drag (8–12% packaging waste; ~20% higher freight; >90d cash cycle) with flat/‑2% YoY demand in mature markets (2024). Recommend prune/divest, standardize formats, redeploy capacity to core SKUs.
| Metric | Value (2024) |
|---|---|
| Unit share | <3% |
| Packaging waste | 8–12% |
| Freight | +~20% |
| Cash cycle | >90 days |
DTC subscriptions for condoms+lube offer sticky recurring revenue into a market estimated at about USD 8.5bn in 2024 and growing at roughly an 8% CAGR, making scale economically attractive. Karex’s low manufacturing cost base supports margin leverage, but limited brand equity and elevated CAC suppress current share. The business needs decisive investment in product differentiation, UX, and community to lower churn and CAC. Scale fast to capture unit economics or cut losses.
Consumer interest in non-latex/alternative-material lines is rising, but Karex’s market share is still forming despite being the world’s largest condom manufacturer with capacity near 5 billion condoms per year. Material sourcing, new tooling and international certifications drive early cash burn, often requiring multi-million USD capex and testing spend. If performance wins trials and gains procurement contracts, this segment can flip to a star; if not, it risks drifting toward dog status.
Modern trade expansion in emerging urban centers meets contested, costly shelf space; global urban population reached about 4.4 billion in 2024, concentrating premium demand and raising entry activation spend (often double-digit percent of early revenues). Early share is thin for Karex, so test-and-learn assortments and localized promotions can unlock growth. Double down where velocities prove out and ROI exceeds acquisition and shelving costs.
Category growth is strong but Karex’s presence in adjacent sexual wellness accessories is nascent; Karex produces ~5 billion condoms annually (2024), indicating manufacturing scale but limited accessory footprint. Brand trust may transfer, yet product-market fit isn’t proven; curated OEMs/partnerships can speed entry while capping upfront investment. Invest with tight, measurable milestones and go/no-go checkpoints.
Advanced urology/catheter niches show durable healthcare demand, but Karex holds minimal share outside SE Asia; global indwelling and external catheter markets were valued around 3–4 billion USD in 2024 with mid-single-digit CAGR. Regulatory and clinical onboarding typically takes 18–36 months, burning upfront cash and delaying revenue. Winning key hospital systems drives volume scalability; failing that, pivot to OEM supply-only preserves margins and lowers go-to-market spend.
Question Marks: DTC condoms+lube address an ~8.5bn USD market (2024) at ~8% CAGR; Karex (capacity ~5B units/yr, 2024) needs heavy spend to cut CAC/churn and prove PMF. Non-latex lines and urology niches (~3–4bn USD, 2024) demand capex and 18–36m regulatory ramp; pursue partnerships, tight milestones, or limit to OEM supply.
| Segment | 2024 Size | Key metric |
|---|---|---|
| DTC condoms+lube | 8.5bn USD | 8% CAGR |
| Urology/catheters | 3–4bn USD | Reg ramp 18–36m |


