
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
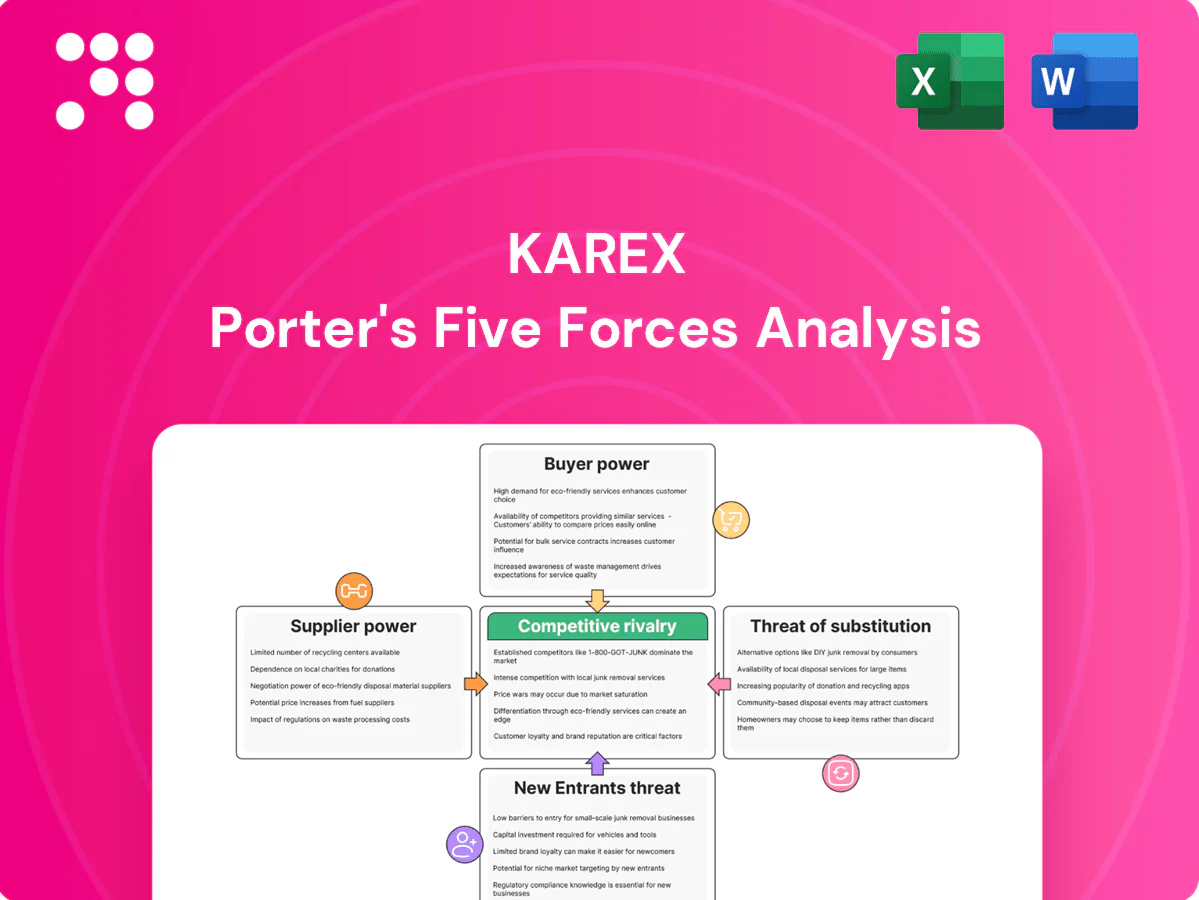
Karex’s Porter's Five Forces snapshot highlights competitive rivalry, buyer and supplier leverage, substitute threats, and entry barriers to frame strategic risk and opportunity. The full report breaks down each force with ratings, visuals and business implications. Unlock the complete analysis to inform smarter investment and strategy decisions.
Natural rubber latex production is heavily concentrated in Southeast Asia—Thailand, Indonesia and Vietnam accounted for roughly 70% of global output in 2023–24—exposing Karex to weather, disease and commodity swings. High-purity polyisoprene and polyurethane supply is limited to a handful of global specialty producers, constraining substitutes. This concentration grants upstream suppliers leverage in tight cycles. Long-term contracts and multi-country sourcing reduce but do not eliminate price spikes.
Specialty additives, silicone lubricants, foils and medical-grade packaging are sourced from qualified vendors to meet regulatory specifications, so approved-vendor lists narrow substitution options and modestly increase supplier bargaining power. Multiple global converters and certified suppliers, however, enable dual-sourcing and competitive bids, limiting long-term supplier dominance. Karex’s scale supports negotiating better pricing and priority allocations with key vendors.
Medical device compliance (ISO 4074, ISO 13485, FDA/CE) mandates validated inputs and processes, making certified raw materials and components highly stickier. Requalifying new suppliers commonly takes 6–12 months and industry surveys cite typical qualification costs around USD 250k–500k, elevating supplier bargaining power for certified inputs. Karex’s mature QA systems and robust vendor auditing partially mitigate this by shortening audit cycles and reducing defect risk. Higher regulatory scrutiny in 2024 further hardened switching costs.
Inputs priced in USD and shipping costs swing margin pressure downstream; container spot rates collapsed from 2021 peaks to roughly USD 1,500 average in 2024, but can move ±30–40% on short notice, and suppliers often pass costs through rapidly in tight logistics markets, shifting bargaining power away from buyers despite Karex’s global footprint offering routing and hedging flexibility.
Karex’s large volumes and multi-year contracts give it clear negotiating leverage and supply assurance, while co-development of thin-film and specialty lubricants creates mutual dependency that reduces suppliers’ ability to impose unilateral price hikes and secures quality continuity.
High concentration of natural rubber (≈70% SE Asia in 2023–24) and limited specialty-polymer suppliers give upstream leverage; certified inputs raise switching costs (qualification USD 250k–500k, 6–12 months). 2024 container avg ≈ USD 1,500 (vol ±30–40%) pressures margins. Karex’s multi-year contracts, scale and co-development moderate supplier power.
| Supplier factor | 2024 metric | Impact |
|---|---|---|
| Raw rubber concentration | ≈70% SE Asia | High |
| Qualification cost/time | USD 250k–500k / 6–12m | Raises switching cost |
| Logistics | Container ≈ USD 1,500 (±30–40%) | Margin volatility |
| Buyer leverage | Multi-year contracts, large volumes | Reduces supplier power |
 Detailed Word Document
Tailored Porter’s Five Forces analysis for Karex that uncovers key drivers of competition, buyer and supplier power, entry barriers, substitutes, and emerging disruptive threats to inform pricing, profitability, and strategic defenses.

 Customizable Excel Spreadsheet
Karex's Porter's Five Forces one-sheet clarifies competitive pressures with an editable radar chart, clean layout and copy-ready slides—ideal for rapid decisions and dashboards.
Large OEMs, global brands, NGOs and government tenders buy at scale with strict specs; Karex discloses production of about 5 billion condoms annually, which places it as a major supplier and targets large-volume contracts.
Their aggregated purchasing and competitive bidding give buyers strong price leverage, while switching costs remain moderate because qualified alternatives exist.
Karex must therefore compete on cost, consistent quality and delivery reliability to retain institutional share.
Private-label retailers push for low unit costs and promotional funding and leverage shelf space and placement for negotiating clout; consistent fill rates and quality lower churn risk. Karex, supplying over 4 billion condoms annually and roughly 20% of global capacity, can use its breadth across condoms, lubes and catheters to offer bundled deals that blunt buyer power.
ONE, Carex, and Trustex create pull-through demand and diversify Karex revenue away from OEM, with Karex supplying roughly 30% of global condom volumes, which strengthens brand-led pricing power. Brand equity and product differentiation on these lines reduce buyer bargaining by making switches costlier. Expanded direct-to-consumer channels cut intermediary leverage and capture higher margins. This portfolio mix helps stabilize pricing across cycles.
Medical-grade performance, on-time delivery and full documentation are non-negotiable for buyers; failures can trigger penalties or delisting, amplifying buyer power. Karex produces about 5 billion condoms annually (~20% global volume in 2024), which mitigates supply risk but raises service expectations. Premium reliability allows modest price premiums of c.3–5% without major churn.
Public tenders are highly price-competitive and transparent, with public procurement representing about 12% of GDP according to the OECD (latest data). Small price deltas, often under 5%, can swing awards and compress margins for suppliers like Karex, while multi-year framework agreements secure volume but cap upside. Operational efficiency and 200–500 basis points margin defense are critical to protect profitability.
Large institutional buyers and tenders exert strong price leverage; Karex produces ~5bn condoms (2024), ~20% global capacity. Public procurement (OECD ~12% of GDP) and tender deltas often <5% compress margins. Karex offsets through cost, reliability, bundled SKUs and brand allowing ~3–5% price premium but faces 200–500bps margin pressure.
| Metric | Value |
|---|---|
| Production (2024) | 5bn units |
| Global share | ~20% |
| Public procurement | ~12% of GDP (OECD) |
| Tender price delta | <5% |
| Price premium | 3–5% |
| Margin pressure | 200–500 bps |
This preview shows the exact Karex Porter's Five Forces analysis you'll receive immediately after purchase—no placeholders or mockups. It is the full, professionally formatted document covering supplier power, buyer power, rivalry, substitutes, and entry barriers. Once bought, you’ll get instant access to this identical file, ready for download and use.
Global branded leaders Reckitt (Durex), Church & Dwight (Trojan), Okamoto and LifeStyles drive heavy R&D and marketing intensity, competing on feel, thinness, textures and brand image. Karex supplies roughly 20% of global condoms and competes indirectly as an OEM on cost-quality and directly through its own brands. Strong brand differentiation in premium segments blunts pure price wars, keeping competition focused on product features and marketing.
Manufacturers in Malaysia, Thailand, China and India fiercely compete on cost for private-label contracts and tenders, with periodic overcapacity driving aggressive discounting. Karex’s position as the world’s largest condom manufacturer and its process know-how sustain lower unit costs versus smaller rivals. Continuous automation, yield improvements and scale economies are central to defending share and margin in this price-sensitive segment.
Product innovation cadence—driven by material science (polyisoprene, PU), ultra-thin films and ergonomic redesigns—has shortened to rapid refresh cycles, raising R&D intensity as global condom market ~USD 7.5bn in 2024. Faster cycles elevate table stakes and capex for testing and scale, while Karex’s multi-material manufacturing enables quicker iteration across SKUs. IP portfolios and regulatory clearances (CE/FDA pathways) create temporary moats that protect launches and pricing power.
Batch failures, recalls, or lapses can instantly shift institutional contracts; Karex, the world’s largest condom manufacturer producing billions of units annually, leverages superior QA and validation to retain buyers. Broad certifications such as ISO 13485 and CE expand addressable markets, while deep compliance remains a competitive asset that materially raises operating costs.
Marketing, e-commerce, and pharmacy relationships drive visibility and margins for Karex; e-commerce accounted for about 24% of global retail sales in 2024, increasing channel importance. Rivals are heavily investing in digital and influencer channels, forcing Karex’s brands to spend to sustain awareness against incumbents. OEM stability subsidizes brand building but creates channel conflicts that require active management.
Global branded leaders drive R&D/marketing while Karex supplies ~20% of global condoms and competes as OEM and brand owner; premium differentiation limits pure price wars. Market size ~USD 7.5bn (2024) with e-commerce ~24% of retail (2024); scale, QA (ISO 13485, CE) and multi-material capability are core defenses.
| Metric | Value |
|---|---|
| Karex share | ~20% |
| Global market | USD 7.5bn (2024) |
| E-commerce | 24% retail (2024) |
| Certifications | ISO 13485, CE |
Pills, IUDs, implants and injections increasingly substitute for pregnancy prevention, with long-acting methods representing roughly 30–40% of modern contraceptive use in high‑income markets (2024); however they do not protect against STIs, limiting full substitutability versus condoms. Uptake is strongly driven by education and healthcare access, and in developed markets LARC adoption has displaced condom usage among a growing share of couples.
Oral and injectable PrEP cut HIV risk by over 99% when taken as prescribed, which in some cohorts has reduced condom use and created partial demand erosion for condoms; however PrEP does not protect against other STIs, and STI rates have risen among high‑PrEP populations, keeping substitution incomplete. Public health campaigns and guidelines continue to promote condoms and regular STI screening, producing a moderate substitution threat concentrated in specific high‑risk cohorts.
Behavioral/natural substitutes—withdrawal, fertility tracking, abstinence—are attractive at zero direct cost; withdrawal has a typical-use failure around 22% (CDC) and fertility-awareness methods show typical-use failure roughly 13–24% in studies. Despite higher failure rates, a measurable minority still switches, and economic downturns amplify price-sensitive moves toward these no-cost options. This creates persistent low-grade substitution pressure on Karex’s paid products.
Female condoms and dental dams offer credible alternative barrier protection but represent under 1% of the global condom market in 2024, with availability and user familiarity remaining low; donor and institutional programs drive most volumes, limiting commercial scale.
Household oils and generic gels offer low-cost, convenient substitutes for branded lubricants, while the global personal lubricants market exceeded USD 2 billion in 2024, heightening price sensitivity; catheter demand shifts when clinicians and payers favor external versus intermittent products, and medical guidance plus reimbursement frameworks (eg hospital formularies, Medicare) strongly shape substitution risk, which varies by subcategory and geography.
LARC adoption (30–40% modern contraceptive use in high‑income markets, 2024) and PrEP (>99% HIV risk reduction when adherent) create partial substitution for condoms but STI protection gap keeps condoms relevant. Behavioral methods (withdrawal ~22% failure; fertility awareness 13–24%) and low‑cost lubricants (personal lubricants >USD 2bn, 2024) exert price‑sensitive pressure; female condoms remain <1% market share (2024).
| Substitute | Key stat (2024) |
|---|---|
| LARC | 30–40% HIC use |
| PrEP | >99% HIV reduction if adherent |
| Withdrawal | ~22% typical failure |
| Female condoms | <1% market |
| Lubricants | >USD 2bn market |
FDA 510(k) clearance, CE marking, ISO 13485 and ISO 4074 demand multi‑year validation, clinical data and multi‑million‑dollar investments; process validation and clinical studies materially raise entry costs. Ongoing regulatory audits and mandated batch testing add recurring compliance spend and operational complexity, creating substantial compliance moats that deter inexperienced entrants.
High-speed dipping lines, cleanrooms and ISO testing labs require significant capex, creating a high capital-intensity barrier to entry. Karex, the world’s largest condom manufacturer, produces over 5 billion units annually, so unit costs favor high utilization and large volumes. New entrants face a long ramp to competitive COGS, while scale players like Karex benefit from procurement discounts and superior yield performance.
Winning shelf space and consumer trust requires sustained marketing spend and national campaigns, not one-off discounts. E-commerce lowers distribution barriers but does not substitute brand credibility built through advertising and endorsements. Institutional tenders demand documented track records and client references. OEM entry is easier than building a brand, yet remains relationship-driven; Karex manufactures about 5 billion condoms annually.
Consistent medical-grade latex and specialty polymers require tightly vetted suppliers; industry supplier qualification commonly takes 6–12 months, slowing switches for newcomers. Qualification cycles and batch-level testing create high entry friction, and any QA slip can trigger product rejections or recalls costing >$1M per event. Established vendor networks and long-term contracts favor incumbents like Karex.
Incumbents can neutralize entrants via aggressive price matching, faster product innovation and exclusive supply or retail contracts; Karex, producing about 5 billion condoms/year and claiming roughly 20% market share, can flex capacity to defend tenders. Strong customer switching inertia and channel relationships further raise barriers, making entry threat moderate-to-low for manufacturing but higher for digital-first brands.
Regulatory and quality barriers (FDA/CE/ISO) plus multi‑million validation costs and recurring audits create high entry costs. Capital intensity—cleanrooms and dipping lines—gives scale incumbents cost advantage. Brand, distribution and supplier qualification (6–12 months) raise switching costs; 2024: Karex ~5bn units/yr (~20% market share), keeping threat moderate‑to‑low.
| Barrier | Metric |
|---|---|
| Regulatory | Multi‑million validation, audits |
| Capex/Scale | Karex 5bn units/yr (2024) |
| Supplier qual. | 6–12 months |


