
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
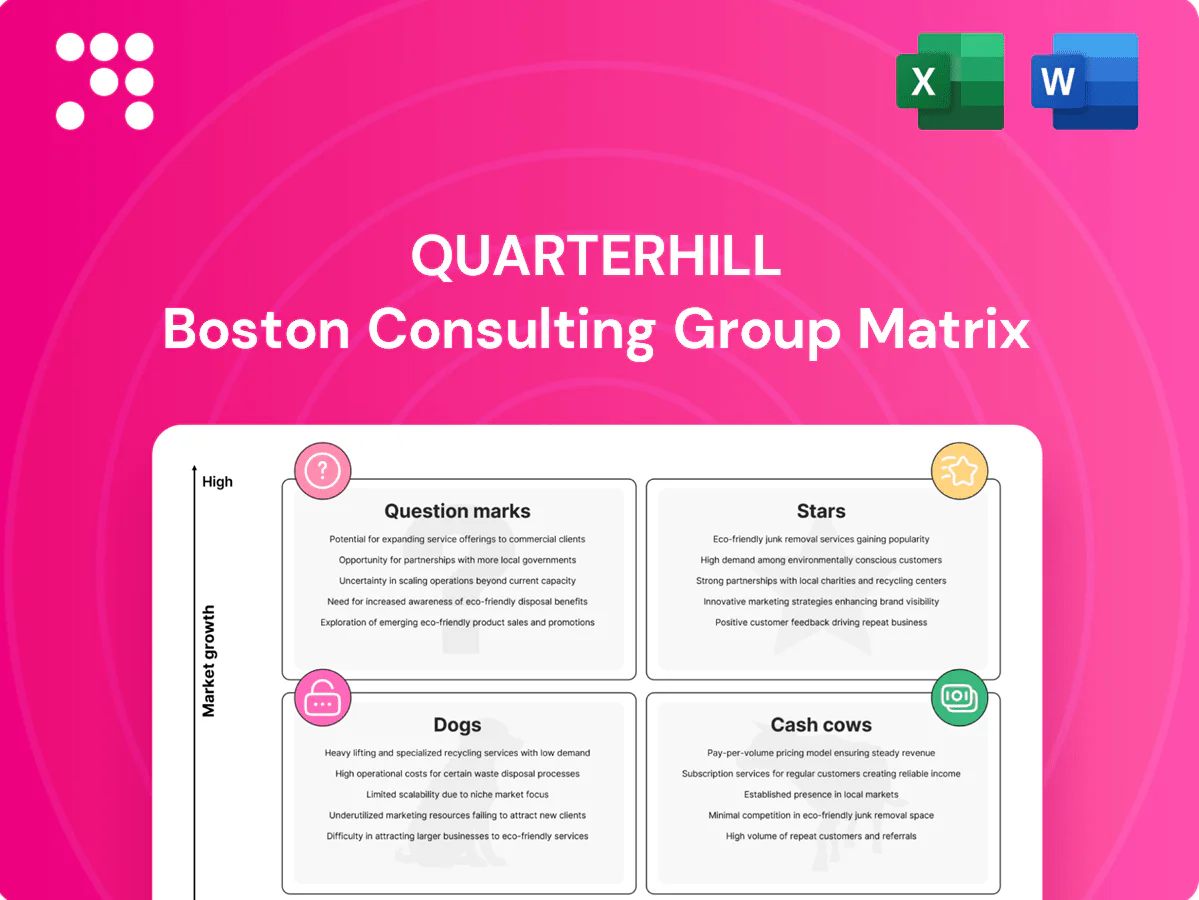
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Curious where Quarterhill’s products land—Stars, Cash Cows, Dogs, or Question Marks? This quick snapshot hints at positioning, but the full BCG Matrix gives you quadrant-by-quadrant clarity, data-backed recommendations, and a ready-to-use Word report plus an Excel summary to present and act on immediately. Buy the full version to skip the guesswork and get strategic, practical steps for where to invest, divest, or double down.
Quarterhill’s core tolling and roadside enforcement stack sits in a fast-growing ITS market estimated at about USD 45B in 2024 with ~9% CAGR, and it holds strong share on key North American corridors. The platform wins multi-year, multi-state contracts and shows high retention once embedded, driving predictable recurring revenue. Continued investment in sales and delivery capacity keeps the flywheel spinning; hold share now and it matures into a high-margin cash engine.
Managed services and O&M contracts represent a high-growth migration from project-based work to outcomes-focused models, operating, maintaining, and optimizing lanes and back offices. These contracts scale with traffic and program scope and lock in predictable renewal cycles, requiring upfront working capital to stand up but delivering durable, recurring cash flows. Continued investment is necessary to cement leadership and expand share in outcome-driven operations.
Interstate toll interoperability and clearing is a hot lane with few credible platforms; the US Interstate System spans about 48,000 miles, concentrating large transaction volumes. Quarterhill’s existing footprint gives leverage on data, rules, and integrations, enabling network effects and higher switching costs. This is leadership territory but requires continuous product and compliance spend to defend share, which compounds value over time.
Agencies demand real-time performance, auditability and revenue assurance; layered analytics that sit on existing stacks enable fast deployment and cross-sell. The marketing analytics market was ~USD 5.2B in 2024 with ~12% CAGR, supporting brisk growth; unit economics improve with scale but product requires continuous upgrades—prioritize roadmap and deploy standard modules now.
Quarterhill’s ITS tolling and enforcement stack sits in a USD 45B ITS market (2024) at ~9% CAGR with strong North American share and multi-year contracts. Managed O&M and interstate clearing scale recurring revenue across the 48,000-mile US Interstate network. Marketing analytics cross-sell targets a ~USD 5.2B market (2024, ~12% CAGR) and margins expand with scale.
| Metric | 2024 | CAGR | Note |
|---|---|---|---|
| ITS market | USD 45B | ~9% | Tolling/enforcement |
| US Interstate | 48,000 miles | - | High volume |
| Marketing analytics | USD 5.2B | ~12% | Cross-sell |
 Detailed Word Document
Comprehensive BCG Matrix review of Quarterhill's units with strategic moves for Stars, Cash Cows, Question Marks, and Dogs.

 Customizable Excel Spreadsheet
One-page BCG Matrix pinpointing portfolio pain points and prioritizing resource allocation for clearer strategic decisions
Installed bases renew quietly and predictably, driving steady cash from legacy toll system maintenance with low incremental selling effort and consistent margins.
Optimize parts inventories, SLAs, and staffing to milk that steady cash flow while keeping service levels high.
Don’t overengineer upgrades; focus on uptime and tight cost control to preserve margin and predictability.
Once throughput stabilizes, unit economics shine: industry benchmarks in 2024 show processors converting over 60% of incremental fees into operating profit, with single-digit capex intensity. Volume-based fees flow to the bottom line as fixed costs dilute. Automating reconciliation and customer care can widen margins by 200–400 basis points. Protect revenue with tight SLAs and renewal timing to lock retention and pricing.
Professional services add-ons—routine integrations, reporting packs, and minor customizations—are repeatable, priced for margin and supported by delivery playbooks that keep costs predictable for Quarterhill in 2024.
Bundle these offerings with renewals to lock scope and revenue; prioritize harvesting cash flow rather than stretching into bespoke engagements.
Replacement sensors, controllers, and lane gear sell into Quarterhill captive bases with highly forecastable demand and limited competition once components are specified, enabling steady margin recovery without large R&D spend.
Tighten inventory turns and standardize SKUs to reduce carrying costs and accelerate cash conversion while milking recurring service revenues from field upgrades.
Installed-base maintenance and aftermarket parts deliver steady cash with low incremental sell; 2024 data: royalties CAD 6.1M and processing fees converting >60% to operating profit. Automating reconciliation/customer care can add 200–400 bps to margins; prioritize SLAs, inventory turns, SKU rationalization and harvesting cash for growth or buybacks.
| Metric | 2024 |
|---|---|
| Royalties | CAD 6.1M |
| Fee profit conversion | >60% |
| Margin lift (automation) | 200–400 bps |
The file you're previewing is the exact BCG Matrix report you'll receive after purchase. No watermarks, no demo notes—just a fully formatted, analysis-ready document designed for strategic clarity. After buying, the full file is instantly downloadable and editable for presentations or planning. What you see is what you get—no surprises, just ready-to-use insight.
One-off bespoke deployments drain margin and management focus because they are low-share, low-growth, high-distraction initiatives that rarely scale into programs; McKinsey 2024 estimates about 70% of digital transformations fail to scale, underscoring the risk. Time-box, sunset, or exit these engagements to protect core margins and redeploy capital into scalable products and licensing.
Commodity roadside hardware in Quarterhill faces race-to-the-bottom pricing with undifferentiated parts, where industry gross margins are typically under 20% and vendors are easily swapped, driving high churn. Capital tends to be trapped in inventory and fixed assets yielding ROIC often below 8%, producing thin returns. Recommend de-emphasize these assets and pursue partnership or outsourcing strategies instead.
Dogs: Small geographies with stagnant spend — by 2024 many jurisdictions capped tech budgets and postponed upgrades, so incremental revenue stays negligible; low share rarely rises without outsized investment, and turnaround plans are typically costly and slow, eroding ROI.
Legacy on-prem back offices are heavy to maintain and increasingly hard to sell anew; with 94% of enterprises using cloud per Flexera 2024, demand skews away from on-prem. Little cross-sell potential remains, so continue fulfilling existing contracts but stop pursuing net-new sales; prioritize migration paths or formal sunset plans.
Dogs are low-share, low-growth assets draining margin and focus: bespoke projects with ~70% fail-to-scale rate (McKinsey 2024), commodity hardware with gross margins <20% and ROIC <8%, expiring IP and small geographies with negligible growth. Recommend sunset, divest, or outsource and redeploy to scalable products and licensing.
| Item | Metric | 2024 Value | Action |
|---|---|---|---|
| Bespoke deployments | Fail-to-scale | 70% (McKinsey) | Time-box/exit |
| Commodity hardware | Gross margin / ROIC | <20% / <8% | De-emphasize |
| Legacy on-prem | Cloud adoption | 94% (Flexera) | Migrate/sunset |
Policy momentum is building: by 2024 four major cities (London, Stockholm, Singapore, Milan) run congestion pricing and 30+ cities had pilots or plans, but market share among platforms remains unsettled. Early pilots show promising traffic and revenue uplifts city-by-city, creating lighthouse-deal opportunities for Quarterhill. Invest aggressively to win marquee contracts fast; if adoption stalls, pivot R&D and sales resources to adjacent mobility services.
V2X and connected vehicle services sit in a high-growth narrative—global V2X market around USD 6.8B in 2024 with ~18% CAGR forecast to 2030—yet standards remain fragmented and few scaled winners have emerged. Quarterhill can leverage its roadside footprint but must form OEM, telco, and agency partnerships to compete. Bet selectively where agencies commit procurement funding at scale and kill fast if RFPs or deployment timelines stall.
AI-driven violation detection shows 2024 pilots delivering 20–40% accuracy gains and 30–50% labor savings, yet buyer adoption remains in testing with 15–20% pilot-to-production conversion; if models push false-positive rates below ~5%, market share can jump fast. Fund targeted proofs with explicit ROI dashboards (cost per true positive, reviewer hours saved); if key metrics miss, stop further investment.
International ITS expansion is a Question Mark for Quarterhill: global ITS TAM ~30 billion USD in 2024 with ~8–9% CAGR to 2030, but different regulations and entrenched incumbents raise entry costs; land-and-expand via joint ventures can unlock municipal and tolling contracts; commit only where bid pipelines are validated and target margins exceed corporate thresholds, otherwise wait-and-watch.
New thematic IP acquisitions in 5G, edge, or automotive electronics can scale rapidly or become cash sinks; 5G subscriptions surpassed 1.5 billion in 2024 and the automotive semiconductor market was about $68B in 2024, so upside exists but licensing pathways and diligence complexity are high. Proceed only with identified anchor licensees and clear royalty models; walk away if adoption signals or technical/legal clearance are weak.
Question Marks: high-growth but uncertain bets—congestion pricing (4 cities by 2024), V2X (~USD 6.8B in 2024, ~18% CAGR), ITS TAM ~USD 30B (2024) and 5G/auto semiconductors (1.5B 5G subs; auto chips ~USD 68B in 2024) offer upside; require anchor deals, JV land-and-expand, stop if pipelines or metrics fail.
| Segment | 2024 | Key Metric |
|---|---|---|
| Congestion | 4 cities | Pilot→deal speed |
| V2X | USD 6.8B | 18% CAGR |
| ITS | USD 30B | 8–9% CAGR |
| 5G/Auto IP | 1.5B subs / USD 68B | Anchor licensees |


