
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
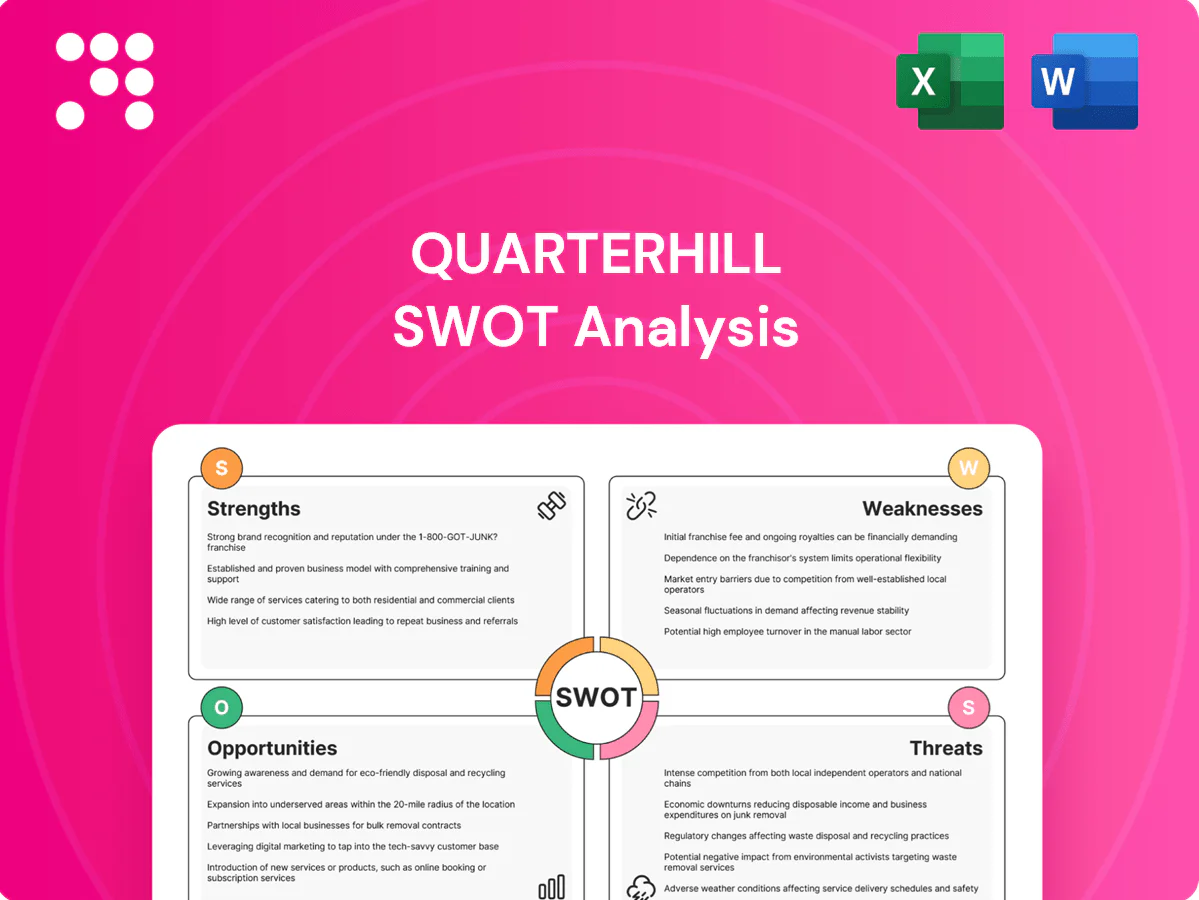
Quarterhill's SWOT distills the firm's tech licensing strengths, market risks, and growth levers into a clear, actionable view for investors and strategists. Purchase the full SWOT to access a research-backed, editable Word report plus Excel matrix. Use it to validate assumptions, build strategy, and present with confidence.
Operating in ITS and IP licensing spreads revenue sources and reduces single-market dependency; Quarterhill’s heritage includes an IP portfolio of roughly 2,000 patents, providing recurring licensing opportunities. The dual model helps balance cyclical swings between project-based ITS work and episodic IP monetizations. Cross-sector insights allow capital allocation to higher risk-adjusted returns, supporting resilience across economic cycles.
Quarterhill, traded on the TSX as QTRH, employs a holding-company model that acquires, optimizes and scales niche leaders, using capital, governance and operational discipline to unlock synergies and margin lift. Repeatable M&A processes generate a steady pipeline of targets and predictable value-creation events. Deep integration expertise shortens payback and compounds returns across successive acquisitions.
Quarterhill's installed ITS base and multi-year contracts (commonly 3–7 years) drive recurring maintenance, managed services and upgrade cycles, giving predictable revenue visibility. Long-term deployments create switching costs and customer stickiness, raising lifetime value. The installed base also serves as a platform for cross-selling analytics and new modules, enabling incremental ARPU expansion.
ITS solutions generate high-value traffic, safety and payments data that produce millions of probe points per city daily, and converting these streams into analytics and decision support measurably enhances agency/operator ROI by optimizing routing, safety interventions and fare capture. Data moats created from proprietary datasets strengthen differentiation and pricing power, and enable performance-based contracting tied to measurable KPIs.
Experienced IP monetization capabilities allow Quarterhill to unlock hidden value from its patent portfolio through licensing and settlements, converting dormant assets into recurring, high-margin cash flows; expertise in valuation, enforcement and negotiation supports these outcomes and helps diversify revenue beyond pure ITS project delivery.
Quarterhill combines ITS recurring contracts (commonly 3–7 years) with an IP portfolio of roughly 2,000 patents, creating diversified, high-margin revenue streams. ITS installed base and millions of probe points/day produce proprietary data moats for analytics cross-sell and KPI-linked contracts. Repeatable holding-company M&A and IP monetization deliver predictable value creation and cash for growth.
| Metric | Value |
|---|---|
| Patent portfolio | ~2,000 |
| Contract length | 3–7 years |
| Data scale | millions probe points/day |
 Detailed Word Document
Provides a concise SWOT analysis of Quarterhill, outlining internal strengths and weaknesses alongside external opportunities and threats to assess its competitive position and growth prospects.

 Customizable Excel Spreadsheet
Delivers a concise, visual SWOT matrix tailored to Quarterhill for rapid strategic alignment and stakeholder briefings; editable format enables quick updates as priorities shift, streamlining decision-making and cross‑team communication.
IP licensing revenue is episodic and lumpy, with Quarterhill reporting CAD 14.3 million in FY2024 and quarterly IP receipts swinging by more than 40% year-over-year, creating forecasting challenges.
Court timelines, counterparties, and case outcomes — often spanning 18–30 months to resolution — drive variability and complicate capital planning.
This volatility can pressure quarterly results and has contributed to depressed valuation multiples relative to peers.
Quarterhill's acquisitive growth model requires harmonizing systems, cultures and go-to-market approaches; Harvard Business Review notes roughly 70% of M&A fail to deliver expected synergies, so missteps can erode value and distract management. Earn-outs and deferred considerations add contractual complexity, while near-term integration costs can compress margins and cash flow for several quarters.
ITS deployments require significant hardware, deployment and service capex and working capital—installations often incur upfront equipment and labor spending of tens to hundreds of thousands per site. Cash conversion on large public-sector contracts commonly stretches 120–180 days, while bid bonds and performance guarantees typically lock up 5–10% of contract value, straining the balance sheet and limiting Quarterhill's flexibility during downturns.
Many ITS buyers are government entities with procurement cycles often spanning 6–24 months, creating timing risk for Quarterhill. Budget delays and policy shifts can stall awards and extend project start dates. Competitive tenders compress pricing, while collections and change orders can elongate cash conversion by several months.
Quarterhill's licensing-focused strategy makes it vulnerable to litigation and adverse publicity; unfavorable rulings or fee awards can materially reduce licensing income and margins, while legal fees are highly variable and can escalate quickly, and reputational harm from aggressive enforcement can damage relationships and spill into other business lines.
Quarterhill's IP licensing is episodic (CAD 14.3M FY2024) and litigation timelines of 18–30 months create forecasting volatility. ITS deployments and public-sector procurement (6–24 months) strain cash conversion (120–180 days) and compress margins. Acquisitive growth faces integration risk (HBR: ~70% M&A fail), raising near-term costs and valuation pressure.
| Metric | Value | Impact |
|---|---|---|
| IP revenue FY2024 | CAD 14.3M | Revenue lumpy |
| Litigation timeline | 18–30 months | Forecast risk |
| Cash conversion | 120–180 days | Working capital strain |
This is a real excerpt from the complete Quarterhill SWOT analysis you'll receive upon purchase—no surprises, just professional quality. The preview below is taken directly from the full report and is fully editable. Buy now to unlock the entire, detailed document immediately after checkout.
Global investment in tolling, road-user charging and safety systems is rising as governments fund digital infrastructure—US IIJA includes roughly $110 billion for roads and bridges and the EU’s NextGenerationEU earmarks about €800 billion for recovery and green transition, favoring smart mobility. Quarterhill can capture both upgrades and greenfield deployments while multi-year programs expand backlog and revenue visibility.
Transforming roadway data into predictive analytics can cut operating costs and improve uptime; the global smart transportation market is projected to top $200B by 2027, underscoring demand. AI optimization of congestion pricing, asset maintenance and enforcement can raise utilization and reduce downtime. Higher-margin software and services can boost ARR mix while data partnerships unlock new recurring revenue streams.
Fragmented regional ITS players create a fertile M&A landscape as the global ITS market reached roughly USD 40 billion in 2024 with ~8–9% CAGR, enabling Quarterhill to pursue roll-ups for scale economies and pooled R&D spend. Consolidation supports cross-selling across an expanded customer base, accelerating revenue growth, while disciplined valuations and integration can compound returns for shareholders.
Emerging markets are accelerating electronic tolling and ITS adoption, with the global electronic toll collection market estimated at about US$5.8B in 2023 and CAGR near 8% to 2030; local partnerships and regulatory compliance can unlock public tenders and concessions. Replicating Quarterhill's proven solutions cuts execution risk abroad while geographic diversification reduces exposure to single-market shocks.
Adjacencies in back-office tolling, account management and secure payments are natural extensions that can lift Quarterhill’s wallet share and defensibility; bundled offerings deepen customer relationships and drive recurring revenue. Enhancing cybersecurity around critical infrastructure addresses rising risk—IBM reported average breach cost at USD 4.45M (2023)—adding measurable value.
Rising public investment (US IIJA ~$110B roads/bridges; EU NextGenerationEU ~€800B) and a projected smart-transport market >$200B by 2027 support Quarterhill’s growth in tolling and ITS. ITS market ~$40B (2024, 8–9% CAGR) and ETC ~$5.8B (2023, ~8% CAGR) enable M&A, geographic expansion and software-led recurring revenue. Cybersecurity demand (avg breach cost $4.45M, 2023) and back-office adjacencies increase wallet share and defensibility.
| Metric | Value |
|---|---|
| IIJA (roads) | $110B |
| NextGenerationEU | €800B |
| Smart transport | >$200B (2027) |
| ITS market | $40B (2024) |
| ETC market | $5.8B (2023) |
Regulatory and policy shifts pose material threats to Quarterhill (TSX: QTRH): changes in tolling policies, privacy rules, or procurement standards can erode project economics and have halted an estimated 20–30% of smart‑transport projects in some jurisdictions. Tightening data governance limits analytics use and GDPR/CPRA‑style compliance can raise operating costs by double‑digit percentages. Policy reversals have delayed or canceled multimillion‑dollar contracts.
Court losses, claim invalidations or adverse precedents can materially erode Quarterhill’s patent portfolio value; patent litigation legal fees often exceed $2M per case, compressing already thin margins. Extended disputes tie up capital and management attention for years, while counterclaims can add multimillion‑dollar exposure and settlement risk, amplifying downside to revenue and valuation.
Global engineering and tech giants (Siemens revenue ~€72B in FY2023, Cisco ~$59B in FY2024) compete aggressively in ITS, using scale to underbid or bundle end‑to‑end solutions. Deep customer integrations and proprietary stacks create strong vendor lock‑ins that are hard to displace. Persistent pricing pressure from scale players can materially erode margins and profitability for smaller ITS specialists.
Rapid advances in sensors, V2X (3GPP Release 16/17), and edge computing mean existing Quarterhill solutions can be outpaced; IDC and industry forecasts flagged multi‑billion dollar edge investment waves in 2024–25 that favor newer architectures. Missing standards updates risks losing tenders as procurement increasingly mandates 5G‑V2X and IEEE interoperability; higher integration complexity raises implementation costs. Underinvesting in R&D relative to market pace could widen the competitive gap.
Recessions and fiscal tightening curb public infrastructure spending—IMF WEO April 2025 pegs global growth near 3.0% for 2025, implying softer capex for Quarterhill’s clients; currency swings of 5–10% materially alter cross‑border project costs; supply‑chain volatility (longer lead times, spiking component bids) delays deployments; higher interest rates (US fed funds ~5.25–5.50% mid‑2025) increase financing costs for customers and Quarterhill.
Regulatory shifts (GDPR/CPRA) and policy reversals have halted 20–30% of smart‑transport projects and can raise operating costs double‑digits. Patent litigation (legal fees >$2M/case) and adverse rulings threaten portfolio value. Competition from giants (Siemens €72B FY2023, Cisco $59B FY2024) and rapid tech shifts (3GPP R16/R17; 5G‑V2X) pressure margins. Macro: IMF growth ~3.0% (2025); fed funds 5.25–5.50%.
| Threat | Key data |
|---|---|
| Regulation | 20–30% projects halted; GDPR/CPRA |
| Litigation | Legal fees >$2M/case |
| Competition & tech | Siemens €72B; Cisco $59B; 3GPP R16/R17 |
| Macro | IMF growth ~3.0% (2025); fed 5.25–5.50% |


