
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
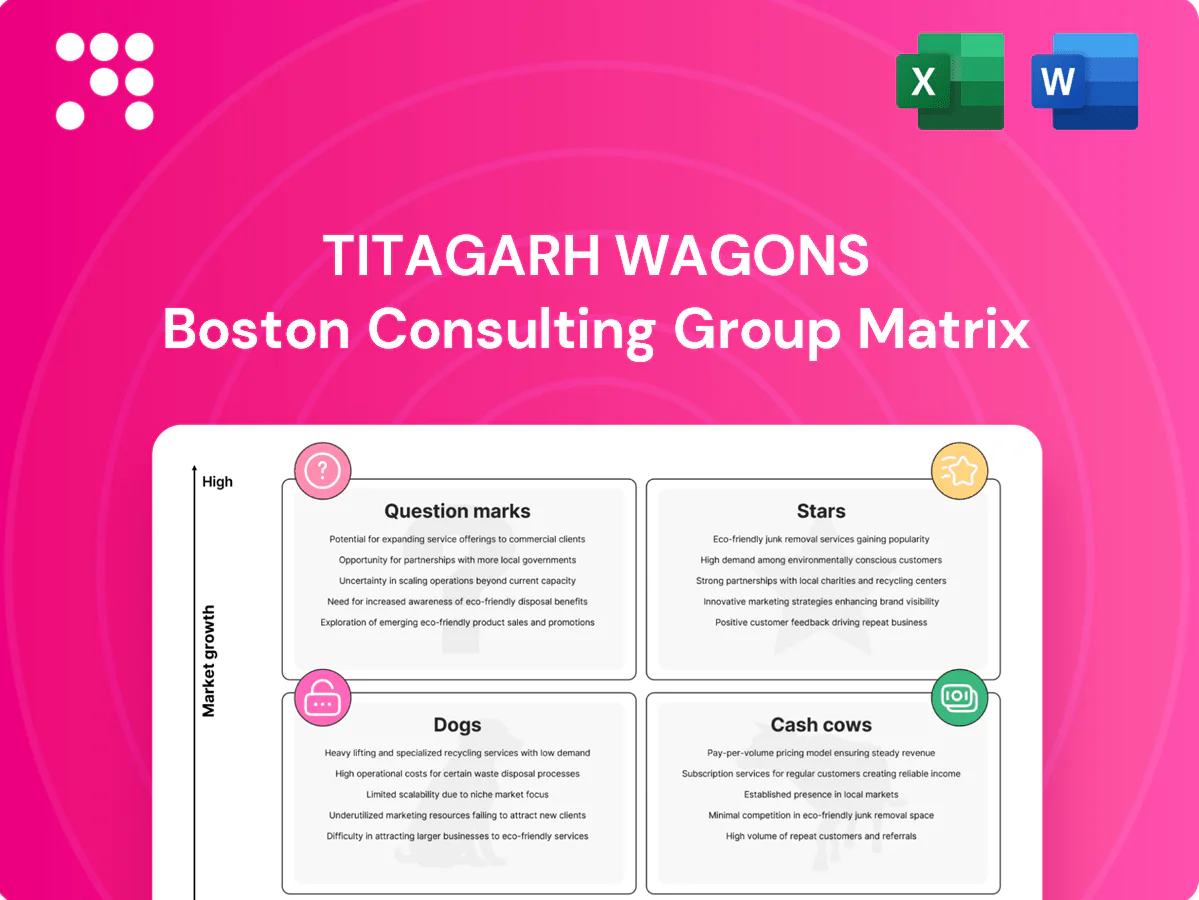
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Titagarh Wagons’ preview hints at which product lines are pulling weight and which need a rethink — but it’s just the tip of the iceberg. Buy the full BCG Matrix to get quadrant-by-quadrant placement, actionable recommendations, and ready-to-use Word and Excel files that save you hours of analysis. Get clarity fast and plan your capital moves with confidence.
Indian cities are scaling metro lines rapidly — over 35 cities and about 750 km of operational metro corridors as of 2024 — and Titagarh Wagons has won credible coach orders, securing visible market share on the ground. High market growth plus demonstrated execution translates to Stars status, but the business requires heavy capex, vendor development and testing, driving significant cash outflows. Maintain funding through the build phase; as network roll-out steadies and utilisation rises, the segment can mature into a cash cow.
Logistics is shifting to lighter, higher-payload wagons and Titagarh moved early with aluminum builds in 2024, gaining fast-growing niche share. That first-mover edge is expanding market share as orders for aluminum wagons rise. Engineering and tooling costs are chunky, so the segment consumes capital. The investment is worth it — manufacturing leadership now sets up long-term annuities.
Suburban rail upgrades and large EMU/MEMU renewals are back in focus after Indian Railways achieved 100% broad‑gauge electrification in 2023, driving a steep demand curve for new coaches. Titagarh Wagons’ modular EMU/commuter coach platforms position it as a go‑to supplier able to bid quickly into multiple tenders. High qualification, testing and ramp requirements keep working‑capital needs elevated, so preserving share via delivery excellence is essential to convert current orders into a durable franchise.
European EMUs via subsidiary sit in Stars: urban and regional fleet renewals in Europe remain steady‑to‑strong in 2024 and Titagarh has live references, lifting market share as its recovering order book wins projects.
Localization, certification, and supply‑chain resilience continue to consume capital; continued investment is warranted to secure margins and delivery timelines.
High‑performance bogies for metro/EMU become the differentiator as line speeds near 100 km/h and axle loads rise toward 14–18 tonnes, and Titagarh’s designs are shipping on marquee projects, nudging it into leadership; the tech stack and specialized testing rigs imply high capex and tight working capital. Nail sub-0.1% failure rates and reliability compounds into platform lock-in and recurring revenue.
Indian metros: >35 cities, ~750 km operational (2024); Titagarh has secured marquee coach and aluminium‑wagon orders, achieving Stars status as market growth and share accelerate. Heavy capex, certification and WC pressure persist; preserve funding to convert orders into cash cows as utilisation rises. European EMU wins raise export credibility.
| Metric | 2024 |
|---|---|
| Operational metro | >35 cities, ~750 km |
| Electrification | 100% BG (2023) |
| Axle loads / speed | 14–18 t / ~100 km/h |
| Failure target | <0.1% |
 Detailed Word Document
In-depth BCG analysis of Titagarh Wagons' units with strategic moves for Stars, Cash Cows, Question Marks and Dogs.

 Customizable Excel Spreadsheet
One-page BCG matrix for Titagarh Wagons, removing portfolio confusion and speeding strategic choices.
Core Indian Railways and private orders kept Titagarh Wagons' BOXN/BCNHL lines humming in 2024 with a multi-year orderbook and sustained monthly dispatches. Market growth is moderate, yet Titagarh’s entrenched capacity and share deliver proven unit economics, low rework rates and high plant utilization (~90% in 2024). Focus: milk volumes, tighten cycle times and protect margins.
Steel castings for bogies/couplers are a cash cow: mature demand from railways and metros with repeat customers and technical approvals yields steady volumes; component EBITDA typically sits around 10–15% in 2024. Vertical integration trims input costs roughly 5–7% and improves control. Growth is low but margins hold if yields/scrap stay tight; incremental automation (1–3% yield gain) can add 100–300 bps of margin.
Installed base repeatedly orders brake gear, doors, interiors and wear parts, creating a predictable, low‑growth, high‑margin stream; industry spare margins in 2024 ran about 20–35%. Working capital is light versus OE (typical spare WC 30–60 days vs OE 90–120). Keeping fill‑rates >95% and expanding SKU coverage 10–20% can gently lift cash flow and cash conversion.
Coach and wagon refurbishments at Titagarh Wagons are disciplined mid‑life upgrade programs run to annual budgets focused on process control and sub‑contractor turnaround rather than headline capacity growth. Cash conversion remains high when scopes are tightly defined and penalties/incentives align, minimizing disputes and working capital drag. Standardized kits and fixed pricing keep throughput predictable and margins stable.
Fabrication & heavy engineering shop floors, jigs and fixtures are fully sweated by steady orders (order book ~INR 7,000 crore in FY2024), driving high utilization and reliable cash generation; margins benefit from learning-curve gains and scale, and continuous lean improvements compound profitability even though the segment won’t outgrow the market.
Titagarh’s cash cows (BOXN/BCNHL, castings, spares, refurb) delivered high utilization (~90% in 2024), orderbook ~INR 7,000 crore (FY2024) and steady cash margins: castings EBITDA 10–15% (2024), spares 20–35%. Low-growth, high-cash with light WC; targeted automation and SKU expansion can add 100–300 bps.
| Segment | Key 2024 metric |
|---|---|
| Order book | INR 7,000 cr |
| Utilization | ~90% |
| Castings EBITDA | 10–15% |
| Spares margin | 20–35% |
The file you're previewing is the final Titagarh Wagons BCG Matrix you'll receive after purchase — no watermarks, no placeholders, just the finished, ready-to-use report. This preview matches the downloadable document exactly, crafted for strategic clarity with market-backed positioning of stars, cash cows, question marks and dogs. After purchase you'll get the same editable, print-ready file via download or email, ready for presentations or internal planning. Buy once, use immediately — no surprises.
Legacy low‑spec export wagon models suffer thin pipelines and sporadic tenders, with price‑only competition eroding margins and dragging returns in 2024. Market growth is tepid and brand leverage is limited, so cash often gets parked in bids and custom tweaks with little payback. Best to prune these SKUs and redeploy capacity to higher‑margin, growth‑oriented segments.
One-off bespoke defense prototypes show interesting engineering but economics stall: approval cycles commonly run 24–60 months and production runs are typically single-digit units, killing scale. Market is narrow and Titagarh Wagons’ share in defense remains negligible versus rolling stock, with orders often below 10 units. Cash ties up in engineering hours and trials, raising working capital intensity. Recommend sunsetting or bundling into scalable defense SKUs only.
Small non‑core foundry jobs are low‑ticket, high‑variety orders that force frequent changeovers, crushing throughput and operational efficiency; industry case studies show changeover downtime can cut foundry output by 10–25%. Growth is flat and these jobs dilute margins — practical contribution to Titagarh Wagons’ top line is negligible while eating skilled capacity. The true loss is opportunity cost on capacity that could serve higher‑margin rolling stock projects; exit or strong price escalation is hard to justify given customer retention risks.
Older passenger-coach designs are being phased to safer, lighter platforms; orders now trickle rather than flow, spares are limited and tooling upkeep costs outweigh returns, so wind-down and redeploy teams to current platforms; no verified public 2024 data for obsolescent-coach order volumes.
Ad‑hoc turnkey packages outside core scope combine civil, E&M and systems work in occasional low‑scale bids; they show poor win rates and thin margins, and market growth alone won’t help if execution costs exceed returns. Coordination and interface management consume remaining margin and increase working capital; pursue only when it directly enables core rolling‑stock volume.
Legacy low‑spec export wagons face sporadic tenders and price competition, eroding margins in 2024.
Defense prototypes have 24–60 month approval cycles and typically <10 unit runs, preventing scale.
Foundry changeovers cut output 10–25%, making small jobs non‑viable versus rolling‑stock work.
Recommend pruning SKUs and redeploying capacity to higher‑margin rolling stock.
| Metric | Value |
|---|---|
| Defense approval cycle | 24–60 months |
| Typical defense order | <10 units |
| Foundry changeover impact | 10–25% output loss |
Procurement cycles for defense mobility and rail‑adjacent kit are heating up, but visibility remains patchy despite Indian Railways capex of Rs 2.4 lakh crore for 2024–25; Titagarh has proven manufacturing capability but does not yet command a dominant share. Trials and qualifications absorb significant cash and working capital. Management should double down where product specs and procurement timelines align, or exit quickly if order pipelines fail to firm up.
Question Marks — Africa/SEA freight wagon exports: these regions are investing in rail but tender cadence remains uneven, creating stop-start demand. Titagarh’s brand is credible locally but not dominant, so early-stage bids and customization absorb engineering and capex. bid costs reduce ROI unless partnered; pursue selective investments with strong local partners to tilt win rates, otherwise pass.
Metro O&M and long‑term services are question marks: winning gives sticky, annuity revenue—India’s metro network crossed ~900 km by 2024 and O&M contracts typically run 10–20 years—yet entry barriers and competition are real. Current share is low though an installed base provides a foot in the door. Expect upfront cash burn for tooling, teams and SLAs (often tens of crores). Pilot small, prove KPIs, then scale or shelve.
Tech curve for battery/hydrogen hybrids is rising while standards and commercial demand remain nascent; Alstom's Coradia iLint entered passenger service in 2018 as an early proof point.
Titagarh’s rolling‑stock DNA gives technical credibility but no meaningful market share in hybrids yet; R&D and prototype programs will consume cash with limited near‑term payback.
Place small options, pursue grant funding and strategic pilots, and monitor for a breakout tender to scale.
Aluminum carbody shells for metro/EMU show clear performance upside—up to 30% lighter than steel, improving energy consumption and lifecycle costs—yet industrialization at Titagarh is mid-journey with weld quality and throughput as gating factors; market share can swing rapidly once targets are met. Heavy upfront capex and training are required, but successful early projects could convert this into a star within 1–2 contract cycles (12–24 months).
Question Marks: selective pilots, small R&D, partner-led export bids; tight cash burn vs upside if tenders materialize (IR capex Rs 2.4 lakh crore 2024–25; India metro ~900 km 2024).
| Item | Metric |
|---|---|
| Aluminum gain | ~30% lighter |
| O&M term | 10–20 yrs |
| Time to star | 12–24 months |


