
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Organize strengths, weaknesses, opportunities and threats.
Connect capabilities with market conditions.
Move from observations to focused strategic action.
Titagarh Wagons shows strong manufacturing scale and diversified rail-rolling portfolio but faces cyclical demand and commodity-price risks; expansion into exports and rail electrification presents clear upside. Want the full, investor-ready SWOT with actionable insights and editable Word+Excel deliverables? Purchase the complete analysis to plan, pitch, or invest with confidence.
Titagarh Wagons produces wagons, coaches and metro trains, spreading revenue across freight, passenger and urban-rail segments and supporting an order book above ₹10,000 crore as of 2024. This breadth enables cross-utilization of engineering, procurement and manufacturing platforms, lowering per-unit costs and shortening lead times. It also improves eligibility for varied tenders, reducing dependence on any single demand cycle.
In-house steel castings supply critical components, reducing dependence on vendors and shortening lead times, which supports tighter project schedules. Vertical integration improves quality control and protects margins by internalizing value-added steps. Fewer external bottlenecks enhance delivery reliability and strengthen negotiating leverage with suppliers and major rail and metro clients.
Titagarh Wagons' domestic leadership—built since its 1997 founding—delivers scale and positions it to benefit from India’s rail investment push. Its export footprint diversifies currency and demand exposure, while international references strengthen credibility in competitive bids. A wider geographic presence reduces country-specific risk and supports steadier order inflows.
Defense-grade engineering at Titagarh Wagons raises quality, reliability and regulatory compliance, enabling spillover into rail safety-critical products and signaling systems and supporting higher-margin, long-cycle defence and rolling-stock contracts that many competitors cannot match.
Titagarh Wagons leverages extensive experience in large public tenders and multi-year projects, improving tender win rates and long-term revenue visibility. Established qualification and certification processes ensure consistent compliance across contracts, while a strong execution track record drives repeat orders from rail and metro clients. Scalable production and project-management systems enable rapid response to order surges without compromising delivery timelines.
Titagarh Wagons (founded 1997) combines diversified revenue across freight, passenger and metro with an order book above ₹10,000 crore (2024), in-house steel castings that shorten lead times and defence-grade engineering that supports higher-margin, safety-critical contracts and export credibility.
| Metric | Value |
|---|---|
| Order book (2024) | Above ₹10,000 crore |
| Founded | 1997 |
| In-house castings | Yes |
 Detailed Word Document
Analyzes Titagarh Wagons’s competitive position by highlighting internal strengths and weaknesses and external opportunities and threats shaping its growth across rail and industrial manufacturing sectors.

 Customizable Excel Spreadsheet
Provides a concise, visual SWOT matrix to quickly align strategy for Titagarh Wagons, highlighting core strengths, operational risks, and growth opportunities for fast stakeholder decision-making.
Revenue is closely tied to government budgets and tender timing; Union Budget 2024 allocated roughly ₹2.6 lakh crore for Railways capex, making public spend a key demand driver. Any budget delays or cuts can disrupt order inflows and cash conversion, pricing is squeezed by competitive bidding, and revenue predictability is weaker than pure private-market peers.
Long production cycles and milestone-based billing stretch receivables for Titagarh Wagons, with an order book of about INR 11,500 crore as of March 2024 increasing cash conversion pressure. Inventory build-up and advance procurement tie up significant cash, heightening reliance on short-term financing. This working-capital intensity can compress returns during rapid scale-up phases.
Steel and energy cost swings materially compress Titagarh Wagons margins, since steel and power are large components of unit costs. Pass-through clauses in contracts are often partial or lagged, leaving the firm to absorb short-term spikes. Hedging is imperfect for long-dated railcar and project contracts, so margin visibility across the multi-year backlog can be uneven.
Advanced coach and metro projects often require external technology tie-ups, and with over 40 metro projects under development in India (2024), reliance on partners can limit IP ownership and pricing power for Titagarh Wagons. Integration risks raise program complexity and have historically contributed to schedule slippage and cost escalation in similar projects. Dependence on partners may slow localization of new platforms and affect margin capture.
Aftermarket services, spares, and refurbishment—typically higher-margin lines—remain under-penetrated for Titagarh Wagons, limiting revenue diversification and annuity streams. A relatively small installed base in certain segments constrains recurring service income, and building a nationwide service and spares network across India takes significant time and investment. This delays margin resilience through downturns and tempers overall profitability during cycles.
Revenue dependence on government tenders (Railways capex ~₹2.6 lakh crore in Union Budget 2024) limits visibility; order-book billing stretches receivables (order book ~INR 11,500 crore, Mar 2024). Steel/energy price swings and partial pass-through compress margins. Aftermarket and service annuities remain under-penetrated, weakening cyclical resilience.
| Metric | Value |
|---|---|
| Order book (Mar 2024) | INR 11,500 crore |
| Railways capex (Budget 2024) | ~₹2.6 lakh crore |
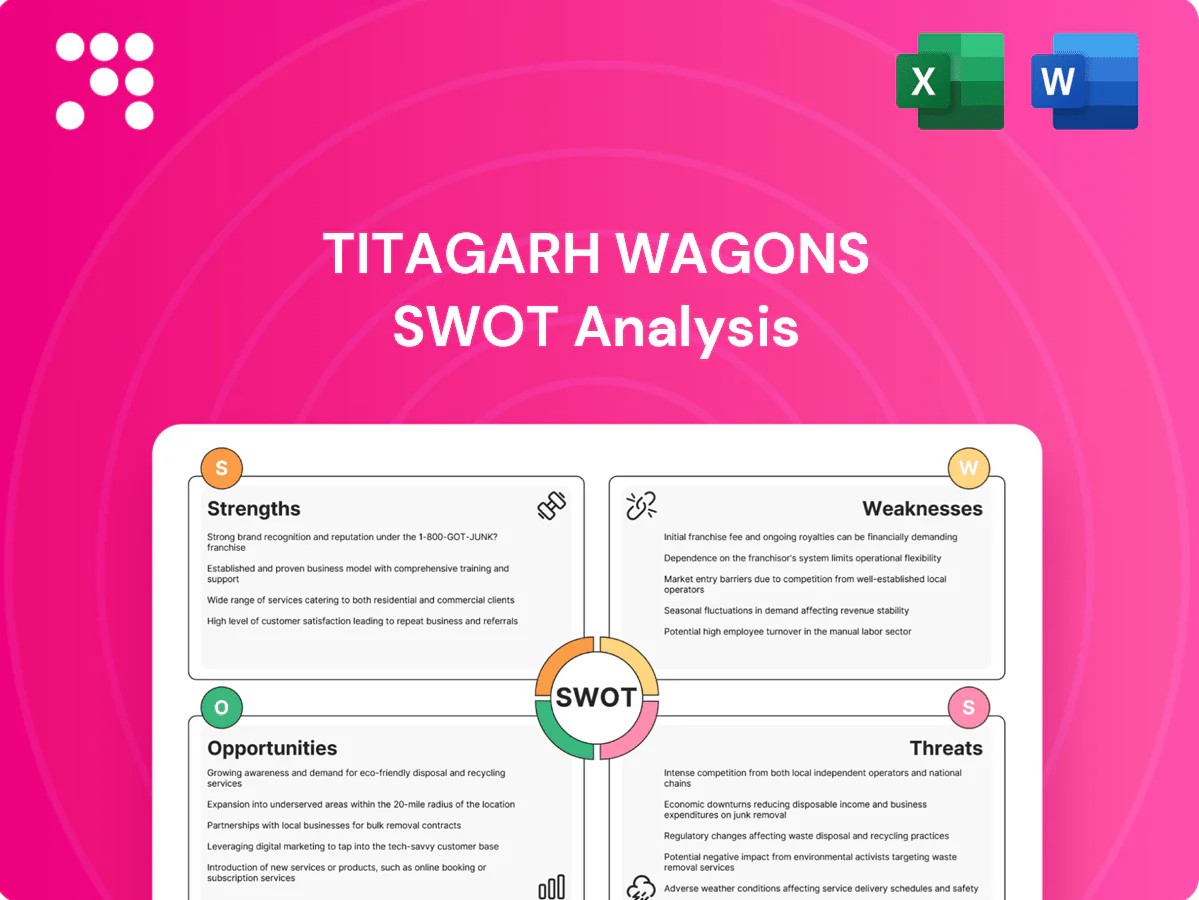
This is the actual SWOT analysis document you’ll receive upon purchase—no surprises, just professional quality. The preview below is taken directly from the full SWOT report you'll get; purchase unlocks the entire in‑depth version. You’re viewing a live preview of the Titagarh Wagons SWOT file and the complete, editable report becomes available after checkout.
India’s rail capex upcycle—with Union Budget capital outlay ~Rs 2.4 lakh crore for FY25—drives demand for wagons and rolling stock. Strong government focus on freight corridors, wagon renewal and passenger upgrades plus a 1,000+ Vande Bharat coach pipeline and metro projects across 30+ cities (~Rs 4 lakh crore) gives multi-year visibility. This sustained program enables Titagarh Wagons to plan confident capacity additions and orderbook growth.
Rapid metro proliferation across 30+ Indian cities and 40+ projects under construction creates a multi‑billion‑dollar trainset pipeline, boosting demand for Titagarh Wagons’ EMUs and metro rakes. Standardization and domestic content norms (procurement favoring high local value addition) advantage local manufacturers. Leading consortium roles enable access to larger packages and turnkey contracts. Lifecycle services—maintenance, spares and retrofits—can generate steady recurring revenue streams.
Many emerging markets seek cost-effective, reliable rolling stock, and Titagarh Wagons can leverage India’s lower manufacturing base to compete with Western OEMs in price-sensitive tenders.
Financing via EXIM Bank lines and multilateral lenders such as the World Bank and ADB has catalyzed several recent regional rail deals, de-risking buyer procurement.
Securing references across South Asia, Africa and Southeast Asia would build momentum and credibility for larger export pipelines.
Rising defense budgets—India allocated about INR 5.93 lakh crore for defence in 2024–25 and global military spending was roughly USD 2.3 trillion in 2023 (SIPRI)—plus indigenization policies boost local suppliers; Titagarh Wagons can scale specialized equipment and castings into new programs, leverage dual‑use technologies to deepen product mix, and potentially lift blended margins and revenue stability.
Aftermarket services—maintenance, spares, overhauls and upgrades—offer Titagarh Wagons recurring annuity streams and margin stability; predictive maintenance and condition monitoring can cut maintenance costs 20–40% and reduce unplanned downtime up to 50%, enabling value-added digital offerings. Long-term service agreements deepen customer ties and support lifecycle revenue. Data-led services create pricing power and differentiation in bids.
India rail capex FY25 ~Rs 2.4 lakh crore and metro pipeline ~Rs 4 lakh crore provide multi‑year wagon/trainset demand; export push to South Asia/Africa leverages India cost competitiveness. Defence budget ~INR 5.93 lakh crore and global military spend ~USD 2.3T open specialist-castings and dual‑use opportunities. Aftermarket services and predictive maintenance (savings 20–40%) create recurring revenue and higher margins.
| Opportunity | Key metric | 2024/25 |
|---|---|---|
| Rail capex | Union Budget | Rs 2.4L crore |
| Metro pipeline | Project value | Rs 4L crore |
| Defence | Budget | INR 5.93L crore |
Domestic peers and global OEMs aggressively compete on large tenders as Indian Railways set a capex target of INR 2.40 lakh crore for 2024–25, intensifying bid competition. Persistent price undercutting in such auctions can materially erode margins for Titagarh Wagons. Rising technical and financial qualification thresholds increase entry costs and favor scale players. Differentiation in engineering, aftermarket services and compliance must outpace commoditization to protect margins.
Land, approvals or funding bottlenecks can stall projects in Titagarh Wagons’ ~₹8,000 crore order book (2024), pushing completion timelines and raising costs by an estimated 10–20% on delayed contracts. Such overruns strain working capital and can inflate receivable cycles, increasing borrowing needs and interest expense. Penalty clauses, often up to ~5% of contract value, directly hit margins, while repeated delays damage reputation and jeopardize future bid wins.
Changes in localization norms or stricter safety standards can shift project economics for Titagarh Wagons, especially as steel and components—which can represent about 60% of input costs—face higher domestic sourcing requirements. Import/export policy shifts and tariffs affect deliveries and margins, relevant given India’s rail capex (circa INR 240,000 crore planned for 2024–25). Rising compliance burdens raise overheads and policy reversals could stall expansion plans.
Global shocks strain supplies of steel, electronics and critical components, with global container freight volatility remaining elevated through 2024 and components lead times often stretching beyond 20 weeks, delaying Titagarh Wagons deliveries and project timelines.
Supplier distress, seen in increased defaults across smaller OEMs in 2023–24, threatens continuity; maintaining buffer inventories mitigates risk but raises carrying costs and working capital needs.
Export exposure creates currency risk on Titagarh Wagons revenues and imported inputs, while interest-rate swings increase working-capital financing costs; hedging reduces but does not eliminate these risks and incurs premiums, and FX/ rate volatility complicates pricing and margin visibility on long-tenor rail contracts.
Intense bidding as Indian Railways capex at INR 2.40 lakh crore (2024–25) risks margin erosion from price undercutting and higher technical quals favoring large players. Delays in the ~₹8,000 crore order book can add 10–20% cost, trigger ~5% penalties and stretch working capital. Input steel (~60% of costs), 20+ week lead times and FX/interest volatility further compress margins.
| Threat | Key metric |
|---|---|
| AR tendering pressure | INR 2.40L cr capex |
| Order-book delays | ~₹8,000 cr; +10–20% cost |
| Input & logistics | Steel ~60%; lead times 20+ wks |


