
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
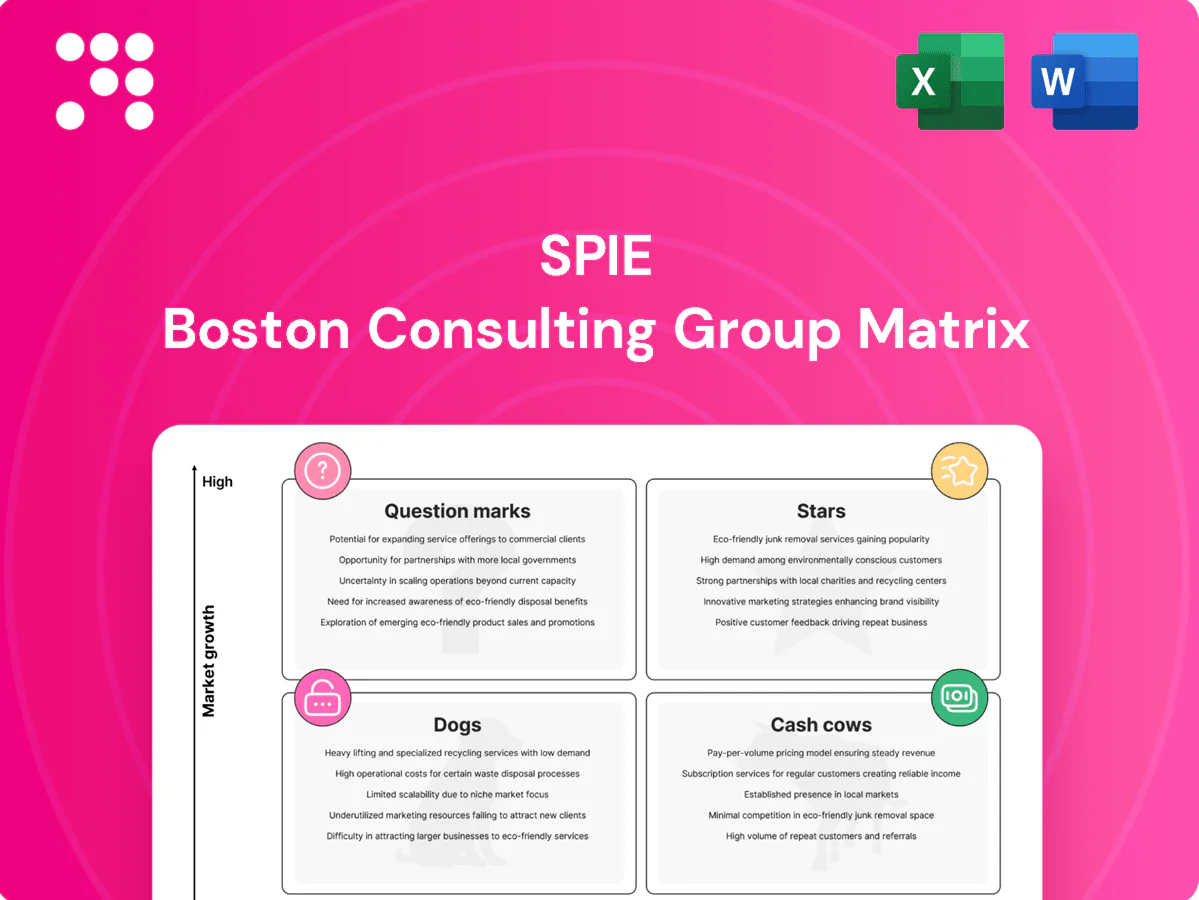
Map Stars, Cash Cows, Question Marks and Dogs.
Compare where to invest, maintain or rationalize.
Turn portfolio position into clear priorities.
Want a clear read on where this company’s products sit — Stars, Cash Cows, Dogs, or Question Marks? This preview is a taste; buy the full BCG Matrix for quadrant-by-quadrant placement, data-backed recommendations, and a ready-to-use strategic plan. Purchase now and get a detailed Word report plus a high-level Excel summary so you can present, prioritize, and act fast.
High market growth and SPIE holds a strong share with deep HVAC/electrical know‑how. Demand keeps climbing as clients chase fast paybacks (typically 3–7 years) and ESG targets; buildings account for about 30% of global final energy use (IEA). It needs stepped-up marketing and delivery capacity to keep pace, but the retrofit flywheel is spinning. Maintain share now and this converts into a massive long-term annuity.
Exploding market for solar, EV charging and microgrids positions SPIE as a Star, with the company winning on design-to-maintain execution and high-quality pipelines despite capital-intensive, cash-hungry upfront projects. Locking multiyear O&M contracts converts installations into recurring margin and improves IRR, strengthening lifetime value. Continue investing to outpace local specialists and scale operations and service capabilities.
Demand surges as owners digitize assets and cut energy use; buildings account for about 40% of global energy consumption, driving BMS upgrades. SPIE’s deep integration across controls, metering and electrical gives it a competitive edge in end-to-end deployments. Growth consumes cash for delivery teams and platforms, but client retention is excellent, so holding share should mature this into a cash cow as growth cools.
AI and cloud buildouts drove data center demand in 2024, with hyperscale operators accounting for >70% of global data center capex and pushing strict uptime SLAs (often 99.999%). SPIE’s critical power, cooling, and maintenance expertise positions it as a go-to partner; uptime contracts are sticky and support recurring revenue. Projects are capital- and talent‑intensive, but typical critical‑infrastructure margins justify continued investment—double down to cement leadership in core European hubs.
Factories require electrification, heat recovery and process optimization now; industry still drives roughly 24% of energy-related CO2 emissions (IEA 2024). SPIE’s multi-technical stack can orchestrate complex retrofits end-to-end. Sales cycles run 12–36 months, working capital can tie up to ~20% of project value, while ticket sizes typically range €2–50M and repeat wins form steady programs.
High-growth retrofit, solar/EV and data-center markets make SPIE a Star with strong share in HVAC, electrical and controls. Buildings ~30% of global final energy (IEA 2024) and hyperscale >70% of data-center capex (2024). Invest in delivery capacity, multiyear O&M and service scale to convert growth into long-term annuity.
| Segment | 2024 stat | Priority |
|---|---|---|
| Buildings/retrofit | ~30% final energy | Scale delivery |
| Data centers | Hyperscale >70% capex | Secure SLAs |
| Solar/EV | Rapid demand | Lock O&M |
 Detailed Word Document
Concise SPIE BCG Matrix review: evaluates units as Stars, Cash Cows, Question Marks, Dogs with strategic actions.

 Customizable Excel Spreadsheet
One-page SPIE BCG Matrix that spots portfolio pain, clarifies investments and divestments for faster C-level decisions.
Electrical installation & maintenance is a mature market where SPIE leverages scale and reputation—about 46,000 employees worldwide in 2024—to secure long-term contracts and predictable volumes. Solid service margins and low promotional spend sustain cash generation, while incremental tech like remote monitoring and predictive maintenance improves uptime and reduces OPEX. Focus is on milking the base and defending key accounts through account management and digital efficiency gains.
HVAC service agreements deliver steady recurring revenue with industry renewal rates above 80% in 2024, classifying them as cash cows for SPIE. Low-cost optimization upsells—controls, filters, airflow balancing—raise service margins by ~5–15% per contract. Market growth is modest (≈2–4% CAGR) while SPIE holds high share. Invest in technician productivity and route density to increase cash flow 10–20%.
Facility O&M is a cash cow with multi-year contracts delivering over 60% recurring revenue across public and private portfolios, while cross-selling electrical, fire safety and energy-savings services boosts average contract value by about 18% in practice.
Market growth is low (circa 2% p.a.), but SPIE’s embedded presence gives strong margins; operational targets focus on maintaining quality, reducing truck rolls by ~15% and keeping churn near zero (under 1%).
Industrial maintenance frameworks are cash cows for SPIE: onsite teams handle steady workloads with predictable invoicing and 2024 renewal rates near 85%, as clients prioritize uptime over price and favor SPIE incumbency. Minimal marketing spend is needed; relationships drive renewals and digital tools lift efficiency and margin.
Telecom infrastructure maintenance (fiber & passive) remains a cash cow as rollouts cooled in 2024 while upkeep stayed steady; recurring service work reduced volatility and underpinned revenue stability in SPIE’s network services.
SPIE’s footprint across 17 countries in 2024 supports faster dispatch and stronger SLA delivery, typically meeting 24-hour field-response targets in dense markets.
Disciplined scheduling and route optimization delivered healthy maintenance margins (around 10–12% EBITDA on maintenance contracts in 2024), enabling cash harvesting and avoiding speculative buildouts.
SPIE cash cows—electrical, HVAC, facility O&M, industrial maintenance and telecom upkeep—deliver stable, recurring cash via long contracts and incumbency (46,000 employees; 17 countries in 2024). HVAC renewals >80% and facility O&M >60% recurring. Maintenance margins ~10–12% EBITDA (2024); focus on route density, digital efficiency and account defense.
| Segment | 2024 metric | Margin/notes |
|---|---|---|
| Electrical | Scale & long contracts | Stable cash |
| HVAC | Renewals >80% | +5–15% upsell margin |
| Facility O&M | >60% recurring | +18% AAV via cross-sell |
| Industrial | Renewals ~85% | Predictable invoicing |
| Telecom | Upkeep dominant | Low volatility |
The file you’re previewing is the exact SPIE BCG Matrix report you’ll receive after purchase. No watermarks or demo content—just a fully formatted, analysis-ready document crafted for strategic clarity. It’s ready to edit, print, or present to stakeholders immediately. Purchase unlocks the final file, sent to your inbox with no surprises.
Market for copper upkeep is shrinking rapidly as fiber and 5G scale — global 5G connections exceeded 2.2 billion by end-2024, accelerating copper retirements. Work is low-margin and often emergency-driven, with average margins below typical SPIE services. Cash tied in legacy skills and parts yields little return versus fiber capex. Prioritize divestment or formal sunset plans to free capital and redeploy into growth networks.
Standalone on‑prem hardware resale sits in Dogs: commodity gear, intense price wars and thin margins (distributor gross margins often 3–7% in 2024) with little differentiation unless paired with managed services. Inventory risk erodes value—holding costs and obsolescence can wipe out margins. Scale back SKUs or sell only bundled with higher‑value contracts and services.
Tiny one-off installation jobs generate low-ticket revenue but high admin overhead and unpredictable scheduling, with technician utilization in field-service firms averaging about 60% in 2023–24. They compete with local shops on price alone and soak technician time that could serve higher-margin contracts. Recommend exit or routing through vetted subcontractors to protect margins and improve schedule reliability.
Fossil-fuel boiler installs are moving to Dogs as regulation and ESG-driven client choices shift demand away from gas and oil systems, raising reputational and regulatory risk for SPIE; the service tail remains but is low-margin and shrinking, making boilers less attractive versus electrification. Prioritize heat pumps and broader electrification investments over fossil boiler offerings.
Commoditized low‑complexity cabling sits in Dogs: highly competitive with low barriers and razor‑thin margins (industry estimates show contractor net margins of roughly 2–5% in 2024). It adds little strategic value unless bundled into integrated ICT packages, while tying up crews and calendar slots that could serve higher‑margin systems.
Market for copper upkeep, commodity on‑prem hardware resale, tiny one‑off installs and fossil boiler work are Dogs: shrinking demand (global 5G connections 2.2B end‑2024), thin margins (distributor 3–7% and contractor net 2–5% in 2024), low tech utilization (~60% 2023–24) and rising ESG/regulatory risk; recommend divest/sunset and redeploy to electrification and fiber.
| Item | 2023–24 Metric |
|---|---|
| 5G reach | 2.2B connections (end‑2024) |
| Distributor margins | 3–7% (2024) |
| Contractor net margin | 2–5% (2024) |
| Tech util. | ~60% (2023–24) |
Growing interest in hydrogen-ready industrial systems accelerated in 2024 as policy packages and announced projects expanded, but current share in industrial energy mixes remains very small and tech is still maturing. SPIE can leverage its industrial integration skills, though commercial proof points are early and limited. Capital intensity is high and returns remain unclear; prioritize selective bets where clients co-fund and policy subsidies/de-risking exist.
Demand for grid-scale battery storage is rising sharply, with analysts in 2024 citing roughly 20% annual growth and forecasts pointing toward nearly 1,000 GWh cumulative deployments by 2030. Procurement remains complex and concentrated among a few entrenched suppliers, playing to SPIE’s electrical and controls DNA. Winning a few flagship projects will accelerate learning; if project margins hold, scale rapidly, otherwise partner or exit quickly.
Global AI-driven predictive maintenance market is hot, estimated around USD 7–8B in 2024 with ~24% CAGR into 2030, indicating rapid opportunity. SPIE’s share is emerging; its O&M data access is a clear competitive edge but productization requires material capex and R&D. Monetization models (subscription, outcome-based) are still settling; pilot aggressively with anchor clients, track conversion and churn metrics closely.
Smart city IoT (lighting, mobility, sensing) sits as a Question Mark for SPIE in the BCG matrix: cities demand measurable outcomes while budgets are political and lumpy, and SPIE brings strong deployment muscle but limited platform ownership; market growth is high with low current share, implying scale-up potential through co-builds with vendors and securing recurring service layers.
District heating heat-pump conversions benefit from decarbonization tailwinds—EU targets aim to cut emissions 55% by 2030—yet projects face complex engineering, fragmented municipal buyers and big capex with multi-year tenders; SPIE’s HVAC and electrical integration is well-aligned but market references remain thin, so pursuing consortia to win early and influence standards is critical.
Question Marks: high-growth, low-share opportunities (H2, grid storage, AI-PM, smart city, heat-pump district heating) where 2024 signals: hydrogen pilots rising, battery storage ~20% y/y with ~1,000 GWh by 2030, AI-PM ~7–8B USD market (2024, ~24% CAGR); pursue selective co-funded pilots, flagship wins, partner/exit if margins fail.
| Segment | 2024 metric | Action |
|---|---|---|
| Battery storage | ~20% y/y; 1,000 GWh by 2030 | Flagship wins |
| AI-PM | 7–8B USD; ~24% CAGR | Pilots, subs models |


