
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
Assess rivalry, entry, substitutes, buyers and suppliers.
See where industry profitability faces the most pressure.
Translate competitive pressure into strategic questions.
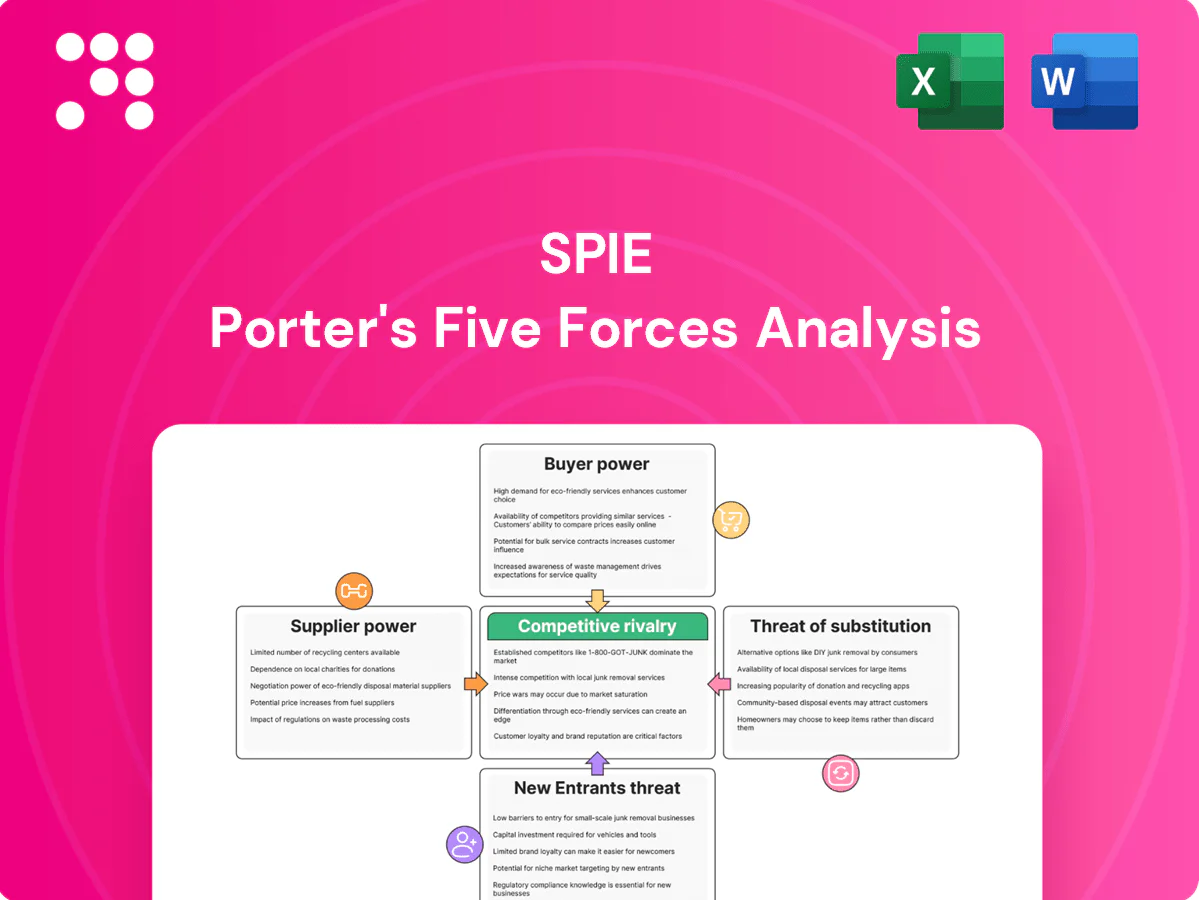
SPIE’s Porter's Five Forces snapshot outlines competitive intensity across suppliers, buyers, substitutes, entry threats and rivalry, highlighting key risks and strategic levers for growth. This brief only scratches the surface. Unlock the full Porter's Five Forces Analysis to access force-by-force ratings, visuals, and actionable recommendations.
HVAC, electrical switchgear and ICS components are concentrated among 5-7 global OEMs (Siemens, Schneider, ABB, Honeywell, Johnson Controls), creating supplier pockets of leverage. Proprietary parts and software licenses can lock SPIE into ecosystems, with specialized gear lead times of 12-24 weeks. Volume purchasing and multi-year frameworks typically secure 3-10% price concessions, but critical items still command premium terms. Dual-sourcing works for commodities, less for specialized equipment.
Certified technicians, electricians and ICT specialists are scarce across EU markets, giving supplier-like bargaining power; SPIE reported ~46,000 employees (2023 annual report) and faces wage inflation with negotiated pay rising about 4% in the euro area in 2024, while preferred subcontractor networks and training pipelines reduce risk but take years to scale and project timelines often hinge on niche certifications and availability.
Building management systems, IoT platforms and cybersecurity tools are sticky and costly, with the global security and risk management market at about $188B in 2024 and IoT platform revenues near $20B, driving material license and integration spend. API access, data portability and license models heavily influence TCO and can add 10–30% in integration and migration costs. SPIE can negotiate enterprise terms, but integration expenses raise switching barriers and vendor roadmaps and compliance create ongoing dependency.
Generic cabling, conduits and fasteners remain fragmented with low supplier power, while specialized sensors, PLCs and high-voltage components are less substitutable and exhibit greater price and availability volatility; the global industrial sensors market was about USD 23 billion in 2024 and PLCs near USD 6.5 billion in 2024, concentrating buying power. Lead-time spikes can disrupt SPIE project delivery, and buffer inventories plus framework agreements partially offset exposure.
Suppliers must meet EU sustainability and safety norms (CSRD extended in 2024 to ~50,000 firms) which narrows qualified pools and raises documentation burdens; compliance audits and reporting add measurable cost and time. SPIE’s pan‑EU scale sets procurement standards, but niche green‑tech vendors can command premiums as regulatory reclassification (EU -55% GHG by 2030 target) shifts critical sourcing.
Supplier power is medium-high: 5–7 OEMs (Siemens, Schneider, ABB, Honeywell, JCI) concentrate HVAC/ICS supply, 12–24 week lead times and typical 3–10% volume rebates. Skilled labor scarce (SPIE ~46,000 employees; euro‑area pay +4% in 2024) raising subcontractor leverage. Specialized sensors/PLCs (USD 23B and 6.5B in 2024) and sticky BMS/IoT/security (USD 188B/20B) increase switching costs and premium pricing.
| Metric | 2024 value |
|---|---|
| OEM concentration | 5–7 firms |
| Lead times | 12–24 weeks |
| Sensors market | USD 23B |
| PLCs market | USD 6.5B |
 Detailed Word Document
Concise Porter's Five Forces analysis tailored for SPIE that uncovers competitive drivers, supplier and buyer power, threat of new entrants and substitutes, and identifies disruptive forces and market dynamics affecting pricing, profitability, and strategic positioning—ready for inclusion in reports or pitch decks.

 Customizable Excel Spreadsheet
Clear, one-sheet SPIE Porter's Five Forces that condenses competitive pressures into a customizable radar—ready for decks, adjustable for new data or scenarios, and usable by non-finance teams without macros.
Public sector, utilities and blue-chip industrials buying via competitive RFPs—public procurement equals roughly 14% of EU GDP—intensify price pressure on suppliers. Framework agreements aggregate volumes and standardize SLAs, enabling buyers to enforce multi-bidder contests and extract concessions. SPIE, with group revenue about €7.7bn (2023), counters by offering bundled multi-technical proposals and firm performance guarantees to preserve margins.
Once systems are integrated and data flows set, switching is disruptive but feasible; many clients face 3–5 year maintenance contracts that create moderate switching costs. Strong interoperability and clear documentation materially reduce buyer lock-in. Demonstrated SLAs of 99.9% uptime (≈8.76 hours downtime/year) and verified energy savings support continuity at stable pricing.
Clients now demand measurable energy savings, >99.9% uptime and clear CO2 reductions (EU 2030 target: -55%), shifting focus from hours to outcomes. This raises measurement and penalty risks for providers and complicates contracts. When outcomes are comparable buyers press price; differentiated analytics and third-party verified performance metrics reduce buyer leverage.
SPIE, with ~€7.9bn 2024 revenue, leverages cross-selling of HVAC, electrical and ICT to increase wallet share and embed clients; bundles make like-for-like procurement comparisons harder, reducing pure price pressure; buyers gain convenience and fewer interfaces, though some unbundle and re-tender specific lots to capture ~5–10% cost savings.
Cyclical industrial slowdowns and tighter public budgets in 2024 have driven more contract renegotiations and project delays, with many buyers deferring capex and preferring opex-light or pay-per-use models to preserve liquidity.
Energy-price volatility continues to push demand for efficiency audits, but procurement now applies strict ROI hurdles—projects often need payback horizons under 3–5 years to pass procurement screens.
SPIE and peers increasingly use flexible contracting, EPC and ESCO structures to share performance risk and align incentives, improving win rates amid stretched buyer bargaining power.
Public procurement (~14% of EU GDP) and large utilities using framework RFPs increase price pressure; SPIE (≈€7.9bn revenue 2024) defends margins with bundled multi-technical offers and guarantees. Switching costs moderate (3–5yr contracts); unbundling can save buyers ~5–10%. Demand for >99.9% uptime and 3–5yr payback tightens ROI scrutiny; EPC/ESCO models share risk and improve win rates.
| Metric | Value |
|---|---|
| SPIE revenue (2024) | ≈€7.9bn |
| Public procurement | ≈14% EU GDP |
| Uptime target | >99.9% |
| Contract length | 3–5 yrs |
| Unbundle savings | 5–10% |
This preview displays the exact SPIE Porter's Five Forces Analysis you will receive upon purchase, with no placeholders or excerpts. The file is the final, professionally formatted document and contains the full competitive assessment, supplier and buyer dynamics, threat analyses, and strategic implications. You’ll gain instant download access to this identical file immediately after payment, ready for use in reports or presentations.
Vinci Energies, Bouygues Energies & Services/Equans and Engie Solutions compete head-to-head across Europe; their combined revenues exceeded €40bn in 2023, underscoring scale-driven intensity. Scale rivals compress margins on large tenders, often shaving 1–3 percentage points off bid margins. Differentiation hinges on sector expertise and digital offerings such as IoT and energy-as-a-service. Local share swings with project pipelines and reference wins.
Thousands of SMEs compete across niches and regions, often undercutting on price and capturing small contracts while acting as subcontractors on larger projects. This fragmented supply base forces SPIE to balance direct delivery with subcontracting strategies to protect margins and scheduling. Local client relationships and faster responsiveness frequently decide awards, especially for geographically dispersed maintenance and installation work.
Contracts are SLA-driven with uptime KPIs typically targeting >99.5% and response times that, if missed, can trigger penalties often exceeding 5% of contract value, squeezing margins. Competitors differentiate on 24/7 capabilities and safety records, commanding service premiums around 10% in bids. Continuous improvement and predictive maintenance — shown to cut unplanned downtime 20–30% in 2024 studies — are critical to defend share.
IoT, BIM, CMMS and analytics platforms are core battlegrounds for SPIE, with proprietary dashboards and remote operations demonstrably improving bid win rates and service margins; global IoT devices reached about 14.4 billion in 2024, intensifying data-driven competition. Buyers push for openness to avoid vendor lock-in, while cybersecurity credentials matter more as the global cyber market neared $200 billion in 2024, separating winners.
Ongoing consolidation in 2023–24 has increased regional density and cross-selling, with SPIE leveraging its network (≈46,000 employees in 2023) to bid larger integrated contracts. Faster integration raises bid competitiveness as post-acquisition synergies determine delivery capacity. Rivals pursue M&A to plug EV, renewables and ICT gaps; scale boosts procurement leverage and multi-project bidding capacity.
Major players (Vinci, Bouygues/Equans, Engie) drove >€40bn revenue in 2023, compressing margins on large tenders; SMEs fragment pricing and win local work. SLAs target >99.5% uptime with penalties >5%, while IoT (14.4B devices 2024) and cyber (~$200B 2024) push data-led differentiation; SPIE ≈46,000 staff (2023) uses scale and M&A to defend bids.
| Metric | Value |
|---|---|
| Large peers 2023 rev | >€40bn |
| SPIE employees (2023) | ≈46,000 |
| IoT devices (2024) | 14.4B |
| Cyber market (2024) | ~$200B |
| SLA uptime | >99.5% |
Large facilities and manufacturers increasingly internalize maintenance to control costs, with industry surveys in 2023 reporting roughly 30% of routine tasks shifted in-house. Internal crews handle preventive and basic corrective work, narrowing outsourcing scope, but complex multi-technical services still drive demand for specialists. Persistent skilled trades shortages—reported at ~40% by sector studies in 2023—limit full insourcing.
OEMs increasingly bundle maintenance, warranties and upgrades into service contracts, and in 2024 OEM-led deals accounted for over 50% of installed-base service spend in many equipment segments. OEMs claim superior parts access and technical expertise, which can crowd out third-party scopes. This displaces some SPIE opportunities on branded fleets. SPIE counters with multi-brand coverage and faster response times to retain share.
Condition-based maintenance, digital twins and AI diagnostics can cut site visits by enabling remote fixes and reducing labour intensity in service contracts; the global predictive maintenance market was valued at about USD 6.7 billion in 2023 and is growing >10% CAGR, driving clients toward lighter service models. SPIE can pivot to selling monitoring, analytics and outcome-based SLAs to capture recurring revenue and offset substitution risk.
Modular, standardized systems enable plug-and-play swaps that reduce onsite complexity and cut demand for bespoke engineering services, shifting margin pressure from installation to pre-integration work.
Simpler estates require fewer custom interventions, compressing engineering revenues while increasing the strategic value of integration planning and lifecycle optimization services.
Alternative contracting models—EPC/ESCOs, energy-as-a-service and PPA-linked solutions—reframe responsibilities, with 2024 EaaS market estimated near $60 billion and corporate PPAs exceeding ~40 GW globally, shifting execution and revenue streams away from traditional vendors. Financial intermediaries and utilities increasingly bundle delivery and operations, raising disintermediation risk for SPIE and potential loss of direct client access. Strategic partnering within these models can preserve SPIE’s role and margin by embedding services into bundled offerings.
Substitution risk rising: ~30% tasks insourced (2023) and OEM-led service >50% of installed-base spend (2024). Predictive maintenance market USD6.7B (2023, >10% CAGR) and modular systems reduce bespoke work. EaaS/PPAs ~$60B / 40GW (2024) but ~40% skilled-trade shortage sustains specialist demand.
| Metric | 2023/24 |
|---|---|
| Insourcing | ~30% |
| OEM service share | >50% |
| Predictive maintenance | USD6.7B, >10% CAGR |
| EaaS/PPAs | $60B / 40GW |
High-voltage, HVAC and industrial cyber projects commonly require ISO 45001 and IEC 62443 compliance, plus third-party safety audits and occupational certifications before bid approval. New entrants face upfront audits, performance bonds (often ~10% of contract value) and higher insurance premiums, raising initial capital needs. Without established references or security clearances, access to critical sites is restricted, delaying contracts. These barriers typically extend time-to-scale by a year or more for newcomers.
Project-based cash flows require performance bonds (commonly 5–10% of contract) and mobilization financing often equal to 10–20% of contract value, driving sizeable working capital needs. New entrants struggle to secure guarantees and finance warranties, while delayed client payments—DSO frequently 60–120 days in the sector—strain liquidity. Large-scale players obtain superior bank lines and supplier credit terms, lowering their capital burden.
Complex facilities select providers with proven uptime and compliance; many mission-critical SLAs require ≥99.9% availability, making reference sites decisive gatekeepers. Reference site portfolios and documented SLAs filter entrants, so new providers typically enter low-risk niches (pilot projects, non-critical sites). Building cross-sector credibility commonly takes 3–5 years, reinforcing high barriers to entry for SPIE-level contracts.
Multi-vendor OT/IT integration, cybersecurity hardening, and data interoperability are nontrivial barriers to entry; entrants must deploy toolchains, unified data models and skilled teams to avoid costly failures. In 2024 global cybersecurity spend topped about 200 billion USD, reflecting high investment required to meet standards. Mistakes carry heavy financial and reputational penalties and established SPIE playbooks are hard to replicate quickly.
Local entry is easy: small firms can capture neighborhood electrical or HVAC work, reflecting that SMEs make up 99.8% of EU businesses. Scaling across SPIEs 30-country footprint requires multi-jurisdiction compliance, language skills, logistics and inclusion on national procurement lists. Cross-border service delivery raises overhead while incumbents benefit from dense networks and a centralized PMO that drive margin and contract win-rate advantages.
SPIE-level projects impose ISO/IEC compliance, third-party audits and security clearances, creating high entry costs; performance bonds (5–10%) plus mobilization financing (10–20%) and higher insurance elevate capital needs. Reference sites and SLAs (≥99.9% uptime) plus 1–5 year credibility build times restrict access; 2024 cybersecurity spend reached ~200 billion USD while SMEs constitute 99.8% of EU firms.
| Barrier | Metric | Value |
|---|---|---|
| Performance bonds | % of contract | 5–10% |
| Mobilization finance | % of contract | 10–20% |
| DSO | Days | 60–120 |
| Cybersecurity spend | 2024 global | ~200B USD |
| Time-to-scale | Years | 1–5 |


