
Digital download
Access the files immediately after checkout.
Access the files immediately after checkout.
Edit, adapt and present the analysis in familiar formats.
See how the whole operating model connects.
Link the offer to segments, channels and relationships.
Review revenue streams, costs, resources and partners.
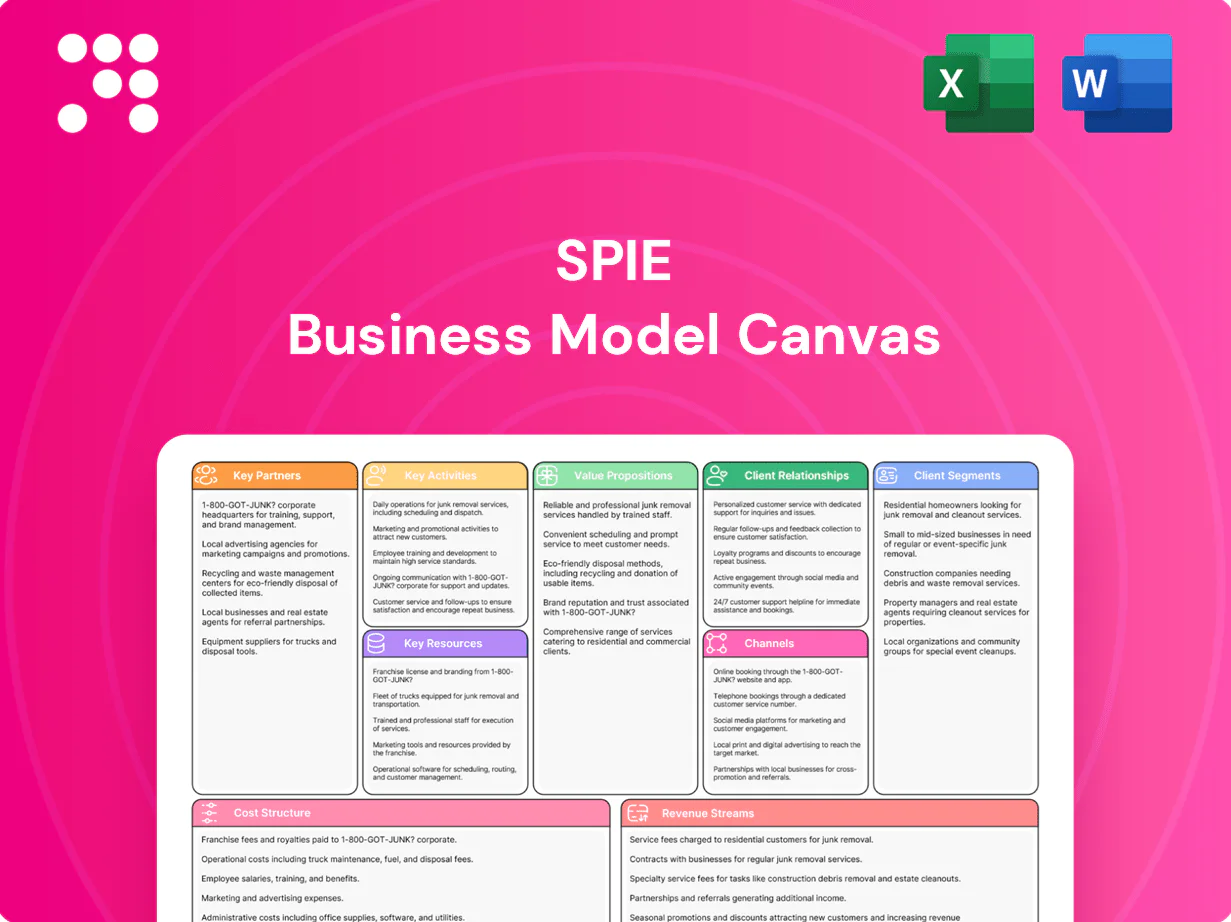
Unlock the strategic blueprint behind SPIE with our Business Model Canvas that maps customer segments, value propositions, key partners and revenue drivers. This concise, actionable snapshot reveals how SPIE captures market share and scales profitably. Purchase the full Word/Excel canvas to benchmark, plan, or present with confidence.
Strategic alliances with HVAC, electrical, automation and ICT OEMs secure certified components and up-to-date firmware, enabling compliant turnkey offers; joint development and preferred pricing speed time-to-market and strengthen bid competitiveness. Vendor training and co-marketing accelerate deployment and reduce lifecycle risk in a sector where buildings account for about 40% of global energy use (IEA). Multi-year support agreements ensure spare parts availability and uptime SLAs commonly targeted at 99.5%.
Partnerships with energy utilities and grid operators enable energy performance contracts, demand response and grid integration, with demand response proven to cut peak load by about 10–20% in practical pilots. Data sharing improves audits and decarbonization roadmaps, boosting measured savings and enabling CAPEX planning. Co-deployment of smart meters, EV chargers and DERs scales uptake; joint tenders increase credibility in public and industrial projects.
Collaborations with construction firms and EPC contractors embed SPIE as the MEP/ICT specialist in design‑build and large infrastructure projects, securing early BIM workflows where 71% of firms report active BIM use (NBS 2024). Early involvement reduces rework—often up to 10% of project costs—while risk‑sharing contracts align timelines and quality outcomes. Improved pipeline visibility enables better resource planning and wider geographic coverage.
Alliances with BMS, SCADA, IoT and cybersecurity vendors enable integrated digital services, with APIs and interoperability feeding centralized data lakes and analytics to drive insights; co-innovation accelerates digital twin, predictive maintenance and asset management rollouts, while certifications (eg IEC 62443, ISO 27001) bolster compliance in critical environments and support procurement requirements in 2024.
Engagement with municipalities, regulators and standards bodies ensures SPIE aligns with EU directives such as the Energy Performance of Buildings Directive and Fit for 55, meeting legal and safety requirements. Access to NextGenerationEU funding (€806.9 billion) and Renovation Wave programmes increases client ROI through subsidies and green financing. Participation in EU pilots delivers verifiable reference projects, while policy insight informs productization of energy-efficiency services.
Strategic OEM and vendor alliances secure certified components, preferred pricing and co‑innovation to shorten time‑to‑market and hit 99.5% uptime SLAs. Utility and DER partnerships enable demand response and energy performance contracts, cutting peak load ~10–20%. EPC, BMS, cybersecurity and public‑sector links embed SPIE in BIM workflows, access NextGenerationEU funding and deliver verifiable decarbonization pilots.
| Partner | Value | 2024 metric |
|---|---|---|
| OEMs/vendors | Turnkey offers | 99.5% SLA |
| Utilities | Demand response | 10–20% peak cut |
| Public/EPC | Funding & pilots | NextGenerationEU €806.9B |
 Detailed Word Document
A comprehensive SPIE Business Model Canvas detailing customer segments, value propositions, channels, revenue streams, key resources/partners, activities, cost structure and customer relationships across the 9 classic BMC blocks; includes SWOT, competitive advantages and polished narratives for presentations, funding and strategic decisions.

 Customizable Excel Spreadsheet
Streamlines SPIE’s complex service and engineering offerings into an editable one-page canvas, relieving time-consuming structuring and aligning cross-functional teams for faster decision-making and clear strategy communication.
Concept, basic and detailed engineering for HVAC, electrical, automation and ICT systems, delivering integrated designs and BIM/digital twin models to de-risk construction and shorten timelines. 2024 compliance focus aligns designs with NIS2 and CSRD requirements. Grid connection studies and energy models target lifecycle cost reductions and peak-demand optimization. Safety, cybersecurity and sustainability standards are embedded across all design phases.
On-site deployment of MEP, OT/IT networks and control systems ensures coordinated installation across construction, electrical and automation teams, with factory and site acceptance testing validating performance against contractual specifications. System integration harmonizes legacy assets and new equipment via protocol translation and middleware to preserve uptime. Handover includes comprehensive documentation, operator training and as-built records to support maintenance and regulatory compliance.
Preventive, predictive and corrective maintenance combine to maximize uptime, with predictive programs shown to cut maintenance costs by up to 40% and unplanned downtime by up to 50% in industry studies. 24/7 remote monitoring and rapid field-service dispatch ensure SLA targets (commonly 99.5%+ uptime) are met. Energy management ties consumption to KPIs and SLAs, enabling cost and carbon reductions. Spare-parts logistics and lifecycle refurbishment planning extend asset life and reduce capex needs.
Digital Solutions and Integration drives SPIE’s IoT sensorization, asset and facilities data integration, and analytics to enable predictive maintenance and uptime; global IoT connections reached about 18 billion in 2024 (Statista). Cybersecure OT–IT connectivity reduces attack surface while feeding dashboards, CMMS, and BMS optimization workflows to cut lifecycle costs. API-enabled services open partner and client ecosystems for scalable, modular service delivery.
Integrated engineering, BIM/digital twins and NIS2/CSRD-aligned designs de-risk projects and shorten timelines. Turnkey MEP/OT/IT deployment with FAT/SAT and training ensures compliant handover. Predictive maintenance, 24/7 monitoring and EPC shared-savings (5–15 yr) cut downtime and costs; 2024 IoT connections ~18bn.
| Metric | Value |
|---|---|
| IoT connections (2024) | 18bn |
| Typical EPC term | 5–15 yr |
The document you're previewing is the exact SPIE Business Model Canvas you’ll receive after purchase, not a mockup or sample. When you complete your order, you’ll get this same professionally formatted file—ready to edit, present, and share—in Word and Excel formats. No surprises, just the full deliverable.
SPIE relies on over 46,000 engineers, technicians, project managers and data specialists across HVAC, electrical, automation and ICT domains. Certified expertise (ISO 9001, ISO 45001) and continuous training embed a safety and compliance culture. Local teams are backed by centralized centers of excellence to scale best practices and improve project KPIs.
CMMS, BMS/SCADA stacks, remote monitoring and analytics toolkits form SPIE’s core digital platform, linked to BIM repositories and knowledge libraries to centralize asset context; industry studies in 2024 show predictive maintenance can cut unplanned downtime by up to 50% and lower maintenance costs 10–40%. Secure data infrastructure and vendor-agnostic integration connectors enable scalable, cross-vendor deployments across complex estates.
Framework agreements with OEMs, software firms and EPCs secure priority access to components and updates, supporting SPIE’s large installed-base and rapid deployment capabilities; SPIE employed about 46,000 people in 2024, enabling scale in execution. Co-innovation and joint certifications accelerate delivery and reduce integration risk. Joint go-to-market with partners expands geographic reach and boosts credibility across industrial, utilities and telecom sectors.
Operational footprint combines regional branches, service hubs and mobile fleets across Europe—SPIE is present in 28 countries and employed about 46,000 people in 2023, supporting group revenue of roughly €7.7 billion. Warehouses and spare-parts logistics are centralized to enable rapid response and minimize downtime, backed by standardized processes and QA systems certified across operations. Safety equipment and specialized commissioning tools are capitalized to meet regulatory and client requirements during complex rollouts.
SPIE is a recognized leader in multi-technical services with strong client references and maintained ISO, cybersecurity, and energy certifications in 2024. Proven track record across critical facilities and industrial sites builds trust, shortening sales cycles and enabling premium pricing. Trust and accreditations are core revenue enablers.
SPIE leverages ~46,000 engineers, technicians and specialists (2024) with ISO 9001, ISO 45001 and cybersecurity certifications (2024), supported by centers of excellence. Core digital stack (CMMS, BMS/SCADA, remote monitoring) enables predictive maintenance (up to 50% less unplanned downtime; 10–40% lower maintenance costs). Regional footprint: 28 countries; group revenue ~€7.7bn (2023).
| Metric | Value |
|---|---|
| Staff (2024) | ~46,000 |
| Revenue (2023) | €7.7bn |
| Countries | 28 |
| Certifications (2024) | ISO 9001, ISO 45001, cybersecurity |
Single partner delivery from design through operations reduces interfaces and project risk, with 2024 industry studies showing integrated providers can cut delivery time by up to 20%. Integrated MEP, automation and ICT accelerate timelines and reduce rework, enabling predictable milestones. Standard methods and tools ensure consistent quality, while one SLA simplifies governance and centralizes accountability.
Guaranteed savings via EPC and M&V frameworks typically deliver 10–30% energy reductions, with HVAC, lighting and process optimization cutting OPEX and CO2 accordingly; accessing 2024 green subsidies and concessional finance can shorten payback by up to 40%, while continuous monitoring sustains more than 85% of measured savings over time.
Proactive maintenance and remote diagnostics cut unplanned downtime—2024 industry data shows predictive maintenance reduces downtime by up to 50% and lowers maintenance spend 20–40%. OEM-grade parts and certified procedures preserve asset integrity and warranty value. Critical-environment expertise ensures operational resilience. Data-driven lifecycle planning extends asset life and smooths capex peaks.
Secure integration of OT and enterprise IT enables safe control-system connectivity, cyber-hardened architectures and compliance support; IBM reports the 2024 average cost of a data breach at $4.45 million. Real-time analytics and digital twins improve decision-making and reduce downtime. Vendor-agnostic design prevents lock-in and simplifies supplier changes.
Localized teams provide European coverage across 18 countries with 35,000 technicians in 2024, managing multi-site programs from facilities to industrial campuses; modular solutions scale from single buildings to portfolio-wide deployments. Rapid mobilization supports both brownfield and greenfield projects, while proven playbooks and standardised KPIs accelerate replication and reduce time-to-value.
Single-partner delivery cuts project risk and schedules (up to 20% faster, 2024). EPC+M&V deliver 10–30% energy savings; green subsidies can shorten payback by 40%. Predictive maintenance halves downtime and lowers maintenance 20–40%. 18-country footprint with 35,000 technicians enables rapid, scalable rollouts.
| Metric | 2024 value | Impact |
|---|---|---|
| Delivery speed | −20% | Faster ROI |
| Energy savings | 10–30% | OPEX & CO2↓ |
| Downtime | −50% | Availability↑ |
| Coverage | 18 countries, 35,000 techs | Scale & mobilization |
Multi-year maintenance and operations agreements (typically 3–7 years) include strict SLAs and quarterly/annual performance reviews to align upgrades and costs; embedded site teams build operational trust and reduce response times, with common uptime targets around 99.5%; renewal pathways are explicitly tied to outcomes and KPIs, supporting renewal rates commonly targeted above 80%.
Diagnostic audits and co-design workshops shape scope and requirements, feeding TCO and ROI models that typically target payback within 18–36 months to support investment cases. Pilot projects de-risk adoption and in 2024 shortened time-to-scale on average by reducing deployment issues. Transparent roadmaps guide phased rollouts with clear milestones and KPIs.
24/7 helpdesk and NOC/SOC coverage ensures continuous operations, with SLA-driven escalation paths for critical assets and guaranteed immediate triage for severity 1 incidents. Proactive alerts and coordinated incident response reduce resolution times and limit exposure. Clients receive periodic reporting and actionable insights, typically monthly and quarterly, to track KPIs and compliance.
Co-innovation and trials focus on POCs for digital, energy and automation use cases, with joint success criteria and sandboxing to de-risk deployments; SPIE’s 2024 organization of ~46,000 employees supports rapid field validation. Iterative feedback loops from pilots refine offers and accelerate time-to-value, while reference sites provide social proof for scaling across clients.
SPIE provides compliance and sustainability advisory aligning clients with CSRD phased reporting started in 2024 and EU taxonomy requirements, implements GHG Protocol-aligned carbon accounting and ESG reporting, navigates grants and incentives including national and EU funding streams, and readies teams for limited-assurance audits and certification prep under new assurance timelines.
Multi-year 3–7y SLAs target ~99.5% uptime with renewal pathways aiming >80% retention; embedded site teams (SPIE ~46,000 employees in 2024) cut response times. Diagnostics, co-design and pilots target payback 18–36 months and reduced time-to-scale in 2024. 24/7 NOC/SOC, monthly/quarterly KPI reports, CSRD-aligned sustainability advisory and grant navigation support compliance.
| Metric | Value (2024) |
|---|---|
| Employees | ~46,000 |
| Uptime SLA | ~99.5% |
| Renewal target | >80% |
| Payback | 18–36 months |
Industry-focused direct sales and key account teams target enterprise and public clients, managing multi-site portfolios across 30+ countries; in 2024 SPIE operated with c.46,000 employees. Relationship managers centralize complex bids and framework agreements, while local branches coordinate on-site delivery to ensure consistency and compliance.
Participation in EU and national procurement platforms gives SPIE access to a public procurement market worth about €2 trillion in 2024, roughly 14% of EU GDP. Pre-qualification on frameworks secures recurring opportunities and pipeline stability. Lot-based awards allow alignment of specialized capabilities with contract scope. Compliance-ready documentation shortens award cycles and improves conversion on tenders.
Co-selling with OEMs and EPCs on large programs drove higher penetration in 2024, with partner-led bids accounting for 42% of awarded contracts and bundled solutions lifting win rates by ~25%; access to partner marketplaces expanded addressable markets, contributing to a 17% uplift in qualified opportunities. Joint references from OEMs/EPCs increased credibility and shortened procurement cycles.
SPIE leverages the corporate website, targeted content marketing and case studies to generate qualified leads and support procurement research; 2024 industry trends show digital channels now drive over 60% of B2B buyer interactions. Self-service portals enable ticketing and reporting, cutting response cycles and support costs by up to 30%. Webinars and virtual demos for decision-makers increase engagement and shorten sales cycles; secure data rooms streamline due diligence in complex deals.
Local branches and mobile teams increase proximity to clients and support SPIE's operations across 35 countries with around 46,000 employees (2024), enabling rapid on-site response. Facility walk-throughs and audits reveal retrofit needs and drive service contracts. Trade fairs and industry events showcase capabilities and generate qualified leads, while pop-up labs demonstrate digital tools and pilot solutions.
Industry-focused direct sales, local branches and mobile teams (46,000 employees, 35 countries in 2024) manage complex bids and on-site delivery. EU/national procurement access (~€2tn public market, c.14% EU GDP) and pre-qualified frameworks secure recurring pipeline. Partner co-selling drove 42% of awards and ~25% higher win rates; digital channels now drive >60% of B2B interactions and self-service cuts support costs ~30%.
| Metric | 2024 |
|---|---|
| Employees | 46,000 |
| Countries | 35 |
| Public procurement market | €2tn |
| Partner-led awards | 42% |
| Digital B2B interactions | >60% |
Commercial and public buildings—offices, hospitals, schools and municipal assets—demand HVAC, electrical, BMS and energy retrofit services focused on comfort, regulatory compliance and cost reduction. Buildings account for ~40% of EU energy use and public procurement equals ~14% of EU GDP, so projects are often delivered via tenders and framework agreements. SPIE targets these high-value retrofit pipelines to deliver operational savings and compliance.
Industrial and manufacturing clients spanning process industries, logistics, and discrete manufacturing prioritize uptime, safety, and reducing energy intensity, driving demand for SPIE services in OT/IT integration and predictive maintenance. Multi-site rollouts favor standardized platforms to scale solutions and control lifecycle costs. McKinsey 2024 reports digitalization and OT/IT convergence can boost manufacturing productivity by 10–20%, reinforcing SPIE’s value proposition.
SPIE serves data centers, transport hubs and utilities where customers demand stringent redundancy, security and SLAs (often 99.99%+ uptime); data centers account for roughly 1% of global electricity use and target PUEs under 1.5 for efficiency. Power quality and thermal management are decisive, with Uptime Institute Tier III/IV and ISO 27001 commonly required. Rapid response (often <4-hour onsite SLAs) and certifications drive procurement decisions.
Operators and enterprise networks rely on SPIE for rollout, fiber and ICT infrastructure, targeting sub-10 ms latency and five‑nines (99.999%) reliability with hardened security SLAs; lifecycle services cover upgrades and expansions over typical 5–15 year contracts, supporting large-scale fiber and 5G deployments in 2024.
SPIE serves commercial/public buildings (buildings ~40% EU energy use) focusing on retrofits and tenders. Manufacturing and industry demand OT/IT convergence and predictive maintenance (productivity +10–20% McKinsey 2024). Data centers, transport and utilities require 99.99%+ SLAs; renewables/EVs drive energy projects (80% new capacity; EV stock >30M 2024).
| Segment | Metric | 2024 |
|---|---|---|
| Buildings | Share of EU energy | ~40% |
| Renewables/EV | New capacity/EV stock | 80% / >30M |
Salaries for engineers (~€50–60k in 2024), technicians (~€25–35k) and project staff (~€35–50k) form the largest payroll component. Ongoing certifications and safety training average ~€800–1,500 per employee annually in 2024. Travel and per diem for field teams typically run €4–6k per field employee per year. Recruitment and retention programs add roughly 8–12% to total HR costs.
Procurement of HVAC, electrical and ICT components typically represents 40–55% of project material costs, with HVAC units ranging €2,500–€15,000 and ICT subsystems averaging €20,000–€100,000 per install in 2024. Tools, vehicles and specialized instruments drive capex of €30k–€200k per region. Spare parts inventory carries roughly 18–25% annual holding cost. Rental versus depreciation for heavy machinery yields 8–15% annual rental expense compared with 10–20% straight-line depreciation.
Licenses for CMMS, BMS/SCADA and analytics drive recurring SaaS and per-seat fees tied to asset scale and uptime requirements. Cloud, cybersecurity and connectivity form the backbone of costs—public cloud services spending reached $688.5 billion in 2024 (Gartner), highlighting market price pressure. Data storage and integration add tiered OPEX for retention, ETL and API gateways. Development and maintenance of platforms require sustained R&D and DevOps budgets for releases and SLAs.
Branch operations, utilities and insurance form the backbone of SPIE's fixed overheads across its regional network, while quality, HSE and certification audits (ISO 9001/14001/45001) generate recurring compliance fees. Legal and tendering expenses raise bid-to-win costs and require specialist teams. Documentation and client/regulatory reporting demand dedicated administrative and IT resources, increasing indirect cost burdens.
SPIE should provision project warranties and performance guarantees at roughly 1–3% of contract value with typical warranty periods of 12–24 months. Provision for penalties and rework is often set between 0.5–5% depending on scope and contract clauses. In 2024 many contractors targeted currency hedges of 60–90% of exposure, held 5–15% supply‑chain buffers, and used insurance/bonding with premiums around 1–3% for large contracts.
Major costs: payroll (engineers €50–60k, techs €25–35k, project staff €35–50k), materials (procurement 40–55% of project material), and cloud/IT (public cloud spend $688.5bn 2024). Fixed overheads include branches, insurance, audits; warranty/penalty provisions ≈1–3%/0.5–5%; FX hedges 60–90%, supply buffers 5–15%.
| Metric | 2024 Range |
|---|---|
| Engineer salary | €50–60k |
| Procurement share | 40–55% |
| Cloud market | $688.5bn |
| Warranty reserve | 1–3% |
Project design and installation fees center on engineering, procurement and construction revenues, typically 60–70% of total project receipts in 2024, billed milestone-by-milestone with formal change orders; integration and commissioning deliver higher margins (about 6–10% in 2024) versus baseline EPC work; milestone billing improves cash flow while variation orders and scope expansions routinely add 5–12% incremental revenue per project.
Maintenance and Operations Contracts deliver recurring fees under SLA-backed services, combining preventive and corrective maintenance bundles with remote monitoring subscriptions and time-and-material billing for unscheduled works. In 2024 market trends accelerated demand for subscription-based remote monitoring, shifting revenue mix toward predictable, service-led income. SLAs improve retention and lifetime value while T&M covers ad hoc revenue spikes.
Guaranteed-savings contracts with M&V (IPMVP-aligned) form core revenue, converting measured energy reductions into shared cashflows; industry ESCO contracts often guarantee double-digit savings, with many programs targeting 10–20% energy reduction. Performance bonuses typically add up to 10–15% uplift for exceeding targets. Financing spreads on arranged third-party funding contribute margin (often 1–3% spread). Demand-response participation adds spot/capacity revenues, increasingly >€10/kW-year in European markets (2024).
Consulting and compliance services bundle audits, studies and permitting support with ESG and decarbonization roadmaps, generating recurring advisory fees and project-linked margins; commissioning and retro-commissioning deliver measurable energy savings, with US DOE reporting median savings of 16% from commissioning. Training and certification preparation upsell yields higher-margin, repeatable revenue and supports long-term client retention.
Core EPC/project fees represent ~60–70% of 2024 receipts, with integration/commissioning margins ~6–10% and variation orders adding 5–12% incremental revenue. Maintenance & SLA subscriptions shift revenue toward predictable service-led income; remote monitoring and SaaS growth (IoT market > $110B in 2024) boost recurring fees. M&V-guaranteed savings (10–20% targets) and DOE median 16% from commissioning monetize performance and upsells.
| Revenue Stream | 2024 Mix / Metric | Typical Margin / Note |
|---|---|---|
| EPC & design | 60–70% of receipts | Baseline; variations +5–12% |
| Integration/commissioning | Project-linked | 6–10% margin; DOE median 16% savings |
| Services & SaaS | Growing recurring share; IoT >$110B | Predictable subscription revenue |
| Performance contracts | 10–20% energy reduction targets | Shared savings +1–3% financing spread |


